

|
시장보고서
상품코드
2154511
남미의 코일드 튜빙 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)South America Coiled Tubing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
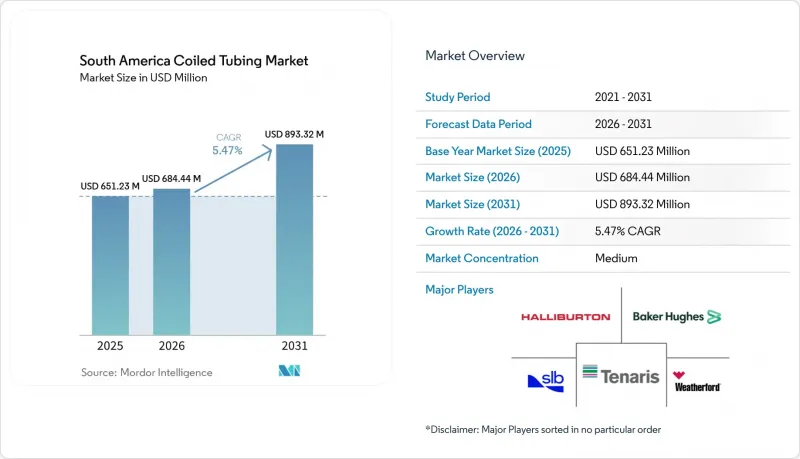
에 따르면 남미의 코일드 튜빙 시장 규모는 2025년 6억 5,123만 달러에서 2026년에는 6억 8,444만 달러로 확대되어, 2031년까지 8억 9,332만 달러에 달할 것으로 예상되며, 2026년부터 2031년까지 CAGR은 5.47%가 될 전망입니다.
남미 코일드 튜빙 시장의 동향 및 인사이트
브라질의 프레스솔트층 및 가이아나의 심해 생산 확대
브라질의 프리솔트층 생산 확대에 따라, 완공 공사, 클린아웃, 생산 지원이 필요한 유정의 수가 증가하고 있습니다. 브라질은 2025년에 하루 490만 boe의 석유·가스 생산량을 기록했으며, 이 중 프리솔트층 생산이 국내 총생산량의 79.6%를 차지했습니다. 페트로브라스는 2026년부터 2030년까지 1,200억 달러 규모의 업스트림 부문 투자를 계획하고 있으며, 2030년까지 프리솔트층 생산량이 회사 총 생산량의 최대 82%를 차지할 것으로 전망됩니다. 새로운 해저 유정마다 완공 공사가 필요하며, 생산 상황의 변화에 따라 추후 개입이 필요할 수도 있습니다. 가이아나에서는 엑슨모빌이 2025년 9월, 68억 달러 규모의 ‘해머헤드’ 프로젝트에 대해 최종 투자 결정을 내렸습니다. 이는 엑슨모빌에게 있어 7번째 스태블록 개발 프로젝트이며, 2029년에는 일일 15만 배럴 규모의 생산 시설이 가동될 전망입니다. FPSO 프로젝트의 증가는 현지에서 설비와 인력을 동원할 수 있는 서비스 제공업체에게 호재가 되고 있습니다.
바카 무에르타의 유정 개발 및 재완성 작업
바카 무에르타에서는 멀티웰 패드 개발 및 재완성 작업을 통해 남미 코일드 튜빙 시장의 육상 수요 기반이 확대되고 있습니다. 코일드 튜빙은 파쇄 공정 간의 플러그 드릴아웃에 사용될 뿐만 아니라, 측면 재진입 및 사이드트랙 작업에도 대응할 수 있습니다. 운영사가 초기 평가 작업에서 반복 가능한 패드 개발로 전환함에 따라 이러한 활동의 빈도가 높아지고 있습니다. 이러한 수요 패턴은 심해에서의 선박 기반 작업이 아닌 대규모 캠페인을 중심으로 이루어진다는 점에서 브라질의 상황과는 다릅니다. 할리버튼이 YPF와 체결한 독점적인 다년 계약인 ‘Zeus’는 비전통적 완공 공사를 대상으로 하고 있지만, 패드 개발 활동의 광범위한 확대는 계약 범위 외의 개입 작업 및 재완공 공사도 뒷받침하고 있습니다. 이로 인해 네우켄 분지에서의 반복 작업을 위해 신뢰성 높은 스트링, 유정 내 도구, 현장 작업 인력을 공급할 수 있는 서비스 제공업체에게는 시장 진입의 여지가 남아 있습니다.
높은 동원 비용과 전문 인력 비용
심해에서의 코일드 튜빙 작업에는 압력 제어 장치, 전용 선박 및 고압 작업 자격을 갖춘 인력이 필요합니다. 이러한 요건으로 인해 브라질의 프레솔트층 유전으로 장비를 수송하거나 가이아나로 수입할 때 비용이 높아집니다. 이러한 비용 장벽은 현지 서비스 거점이 제한된 지역에서 특히 두드러집니다. ANP의 안전 요건에 따르면, 운영사는 해양 유정 작업 시 압력 차단 장치의 무결성을 문서화해야 하며, 이로 인해 개입 계획에 규정 준수 관련 작업이 추가됩니다. 이미 입지를 다진 공급업체는 설비, 교육 및 규정 준수 비용을 여러 계약에 분산할 수 있으므로 경쟁 우위를 점하고 있습니다. 이로 인해 해양 분야의 수요가 확대되고 있음에도 불구하고, 소규모 공급업체의 시장 진입이 지연될 가능성이 있습니다.
부문 분석
2025년, 남미 코일드 튜빙 시장 점유율 중 유정 개입이 63.2%를 차지했습니다. 이 부문은 브라질의 성숙한 해양 자산과 캄포스 분지에서의 지속적인 개입 작업량으로부터 혜택을 받고 있습니다. 운영사들은 클린아웃, 압력 관리 작업, 자극 처리 및 기타 생산 지원 업무에 코일드 튜빙을 사용하고 있습니다. 할리버튼의 페트로브라스와의 계약에는 코일드 튜빙 서비스를 포함한 해양 개입 및 플러그 앤 어번던먼트 활동이 포함되어 있습니다. 베이커 휴즈 역시 마카에에 해양 워크오버 및 플러그 앤 어번던먼트 프로그램 전용 시설을 확보하고 있습니다. 이러한 계약들은 프로그램 기간 동안 시추공 개입 수익의 안정적인 기반을 제공하고 있습니다.
시추는 가장 빠르게 성장하는 서비스 유형이며, 이 부문에서 남미의 코일드 튜빙 시장 규모는 2026년부터 2031년까지 연평균 성장률(CAGR) 6.7%로 확대될 것으로 예측됩니다. 코일드 튜빙을 이용한 시추는 특히 바카 무에르타에서 측면 재진입 및 사이드트랙 작업을 지원합니다. 이 부문은 패드 유정의 생산 수명을 연장하고 잔존 저류층 구간에 접근하려는 증가하는 수요와 밀접한 관련이 있습니다. 또한 브라질과 가이아나에서 FPSO에 연결된 해저 개발 유정이 증가함에 따라 유정 완공 공사도 증가하고 있습니다. 질소 리프트 및 매트릭스 자극을 포함한 기타 서비스는 규모는 여전히 작지만, 성숙한 유정의 생산성 향상을 뒷받침하고 있습니다. 산타카타리나 주립대학교가 2025년에 실시한 연구에서는 생산 유도를 위한 코일드 튜빙을 이용한 질소 활용이 검토되었으며, 브라질 유정에서 이 기법의 기술적 유효성이 입증되었습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
- 조사 가정과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 공급망 분석
- Porter's Five Forces 분석
- 기술 동향
- 규제 상황
- 투자 분석
제5장 시장 규모와 성장 예측
- 서비스 유형별
- 전개 로케이션별
- 지역별
- 브라질
- 아르헨티나
- 가이아나
- 콜롬비아
- 칠레
- 기타 남미 국가
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- Aker Solutions ASA
- Altus Intervention
- Archer Limited
- Baker Hughes Company
- C&J Well Services
- Calfrac Well Services Ltd.
- Halliburton Company
- Helix Energy Solutions Group, Inc.
- Jereh Group
- Key Energy Services, LLC
- Nabors Industries Ltd.
- National Oilwell Varco(NOV) Inc.
- Oceaneering International, Inc.
- Royal IHC
- SLB(Schlumberger Limited)
- STEP Energy Services Ltd.
- Superior Energy Services, Inc.
- Tenaris S.A.
- Trican Well Service Ltd.
- Weatherford International plc
제7장 시장 기회와 향후 전망
KSM 26.10.29According to Mordor Intelligence, the South America coiled tubing market size is expected to increase from USD 651.23 million in 2025 to USD 684.44 million in 2026 and reach USD 893.32 million by 2031, at a CAGR of 5.47% over 2026-2031.
South America Coiled Tubing Market Trends and Insights
Expansion of Brazil Pre-Salt and Guyana Deepwater Production
Brazil's pre-salt output expansion increases the number of wells that need completion, cleanout, and production support. Brazil recorded 4.9 million boe/d of oil and gas output in 2025, while pre-salt production represented 79.6% of the country total. Petrobras plans USD 120 billion of upstream investment for 2026 through 2030, with pre-salt production expected to represent up to 82% of its output by 2030. Each new subsea well requires work during completion and may require later intervention as production conditions change. In Guyana, ExxonMobil made a final investment decision in September 2025 on the USD 6.8 billion Hammerhead project, its seventh Stabroek development, with a 150,000 bopd facility expected in 2029. The growing number of FPSO projects creates an opportunity for service providers that can mobilize equipment and personnel locally.
Vaca Muerta Well Development and Recompletion Activity
Vaca Muerta is widening the onshore demand base for the South America coiled tubing market through multi-well pad development and recompletion work. Coiled tubing is used for plug drill-outs between fracturing stages and can support lateral re-entries and sidetracks. These activities become more frequent when operators move from early appraisal work to repeatable pad development. The demand pattern differs from Brazil because it centers on high-volume campaigns rather than deepwater vessel-based work. Halliburton's exclusive multi-year Zeus completions contract with YPF covers unconventional completions, but the broader expansion of pad activity also supports intervention and recompletion work outside the contract scope. This leaves room for providers that can supply reliable strings, downhole tools, and field crews for repeated operations in the Neuquen Basin.
High Mobilization and Specialized Personnel Costs
Deepwater coiled tubing work requires pressure-control equipment, specialized vessels, and personnel qualified for high-pressure operations. These requirements raise the cost of sending equipment to Brazil's pre-salt fields or importing it into Guyana. The cost barrier is particularly relevant where local service bases are limited. ANP safety requirements require operators to document pressure-barrier integrity for offshore well work, which adds compliance work to intervention planning. Established providers have an advantage because they can spread equipment, training, and compliance costs across several contracts. This can slow entry by smaller providers even when offshore demand is expanding.
Other drivers and restraints analyzed in the detailed report include:
- Aging-Well Production Optimization and Life Extension
- Rigless Intervention Demand to Reduce Offshore Nonproductive Time
- Wireline, Hydraulic Workover, and Other Substitute Competition
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Well intervention accounted for 63.2% of the South America coiled tubing market share in 2025. The segment benefits from Brazil's mature offshore assets and the continuing intervention workload in the Campos Basin. Operators use coiled tubing for cleanouts, pressure-management work, stimulation, and other production support tasks. Halliburton's Petrobras contract covers offshore intervention and plug-and-abandonment activity, including coiled tubing services. Baker Hughes has also committed dedicated capacity at Macae for its offshore workover and plug-and-abandonment program. These contracts provide a stable base for well intervention revenue through the active terms of the programs.
Drilling is the fastest-growing service type and the South America coiled tubing market size for this segment is forecast to grow at a 6.7% CAGR from 2026 to 2031. Coiled tubing drilling supports lateral re-entries and sidetrack operations, particularly in Vaca Muerta. The segment is linked to a growing need to extend the productive life of pad wells and access remaining reservoir sections. Well completion activity also rises as Brazil and Guyana add subsea development wells connected to FPSOs. Other services, including nitrogen lifting and matrix stimulation, remain smaller but support production improvement in mature wells. A 2025 study from Universidade do Estado de Santa Catarina examined nitrogen use through coiled tubing for production induction, illustrating the technical relevance of this approach for Brazilian wells.
Complete Report Scope:
- By Service Type
- Well Intervention
- Drilling
- Well Completion
- Other Services
- By Location of Deployment
- Onshore
- Offshore
- By Geography
- Brazil
- Argentina
- Guyana
- Colombia
- Chile
- Rest of South America
List of Companies Covered in this Report:
- Aker Solutions ASA
- Altus Intervention
- Archer Limited
- Baker Hughes Company
- C&J Well Services
- Calfrac Well Services Ltd.
- Halliburton Company
- Helix Energy Solutions Group, Inc.
- Jereh Group
- Key Energy Services, LLC
- Nabors Industries Ltd.
- National Oilwell Varco (NOV) Inc.
- Oceaneering International, Inc.
- Royal IHC
- SLB (Schlumberger Limited)
- STEP Energy Services Ltd.
- Superior Energy Services, Inc.
- Tenaris S.A.
- Trican Well Service Ltd.
- Weatherford International plc
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of Brazil Pre-Salt and Guyana Deepwater Production
- 4.2.2 Vaca Muerta Well Development and Recompletion Activity
- 4.2.3 Aging-Well Production Optimization and Life Extension
- 4.2.4 Rigless Intervention Demand to Reduce Offshore Nonproductive Time
- 4.2.5 Real-Time Downhole Diagnostics and Automated Coiled Tubing
- 4.2.6 Integrated Workover and Plug-and-Abandonment Campaigns
- 4.3 Market Restraints
- 4.3.1 High Mobilization and Specialized Personnel Costs
- 4.3.2 Wireline, Hydraulic Workover, and Other Substitute Competition
- 4.3.3 Fatigue, Corrosion, and Sour-Service Qualification Limits
- 4.3.4 Local-Content, Permitting, and Cross-Border Logistics Friction
- 4.4 Supply-Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Service Type
- 5.1.1 Well Intervention
- 5.1.2 Drilling
- 5.1.3 Well Completion
- 5.1.4 Other Services
- 5.2 By Location of Deployment
- 5.2.1 Onshore
- 5.2.2 Offshore
- 5.3 By Geography
- 5.3.1 Brazil
- 5.3.2 Argentina
- 5.3.3 Guyana
- 5.3.4 Colombia
- 5.3.5 Chile
- 5.3.6 Rest of South America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Aker Solutions ASA
- 6.4.2 Altus Intervention
- 6.4.3 Archer Limited
- 6.4.4 Baker Hughes Company
- 6.4.5 C&J Well Services
- 6.4.6 Calfrac Well Services Ltd.
- 6.4.7 Halliburton Company
- 6.4.8 Helix Energy Solutions Group, Inc.
- 6.4.9 Jereh Group
- 6.4.10 Key Energy Services, LLC
- 6.4.11 Nabors Industries Ltd.
- 6.4.12 National Oilwell Varco (NOV) Inc.
- 6.4.13 Oceaneering International, Inc.
- 6.4.14 Royal IHC
- 6.4.15 SLB (Schlumberger Limited)
- 6.4.16 STEP Energy Services Ltd.
- 6.4.17 Superior Energy Services, Inc.
- 6.4.18 Tenaris S.A.
- 6.4.19 Trican Well Service Ltd.
- 6.4.20 Weatherford International plc
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


