

|
시장보고서
상품코드
2154517
적층 제조용 수지 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Additive Manufacturing Resins - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
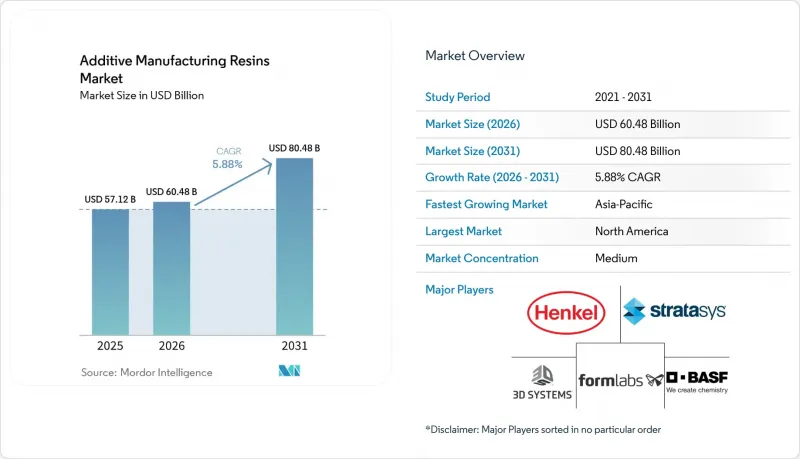
에 따르면 적층 제조용 수지 시장 규모는 2025년에 571억 2,000만 달러로 평가되며, 2026년 604억 8,000만 달러에서 2031년까지 804억 8,000만 달러에 달할 것으로 예측되며, 예측 기간(2026-2031년) 동안 CAGR은 5.88%가 될 전망입니다.
전 세계 적층 제조용 수지 시장의 동향 및 인사이트
환자 맞춤형 의료용 부품에 대한 수요
맞춤형 의료 제조는 적층 제조용 수지 시장의 장기적인 수요를 뒷받침하고 있습니다. 이는 임상용 부품에 명확한 재료 성능과 관리된 제조 기록이 요구되기 때문입니다. 국제표준화기구(ISO) 10993 시리즈의 생체적합성 규격은 환자와의 반복적인 접촉을 목적으로 하는 제품을 포함하여 의료용 수지 제품의 적합성 기준을 점점 더 명확하게 정의하고 있습니다. Stratasys사의 ‘P3 MED Silicone 25A’는 ISO 10993-5, ISO 10993-10, 및 ISO 10993-23 인증을 획득했으며, 환자 맞춤형 착용형 의료기기를 위한 미국 식품의약국(FDA) 마스터 파일로 뒷받침되고 있습니다. FDA 및 유럽연합 의료기기 규정(EU MDR)의 시판 후 감시 요건에서는 검증된 공급망, 추적 가능한 로트 기록, 확립된 문서화 프로세스를 갖춘 공급업체가 우선적으로 고려됩니다. 제조업체는 각 임상 용도에 사용되는 검증된 프로세스를 보호해야 하므로, 이러한 요건은 수년에 걸친 공급 계약을 뒷받침할 수 있습니다. 일본에서는 2025년에 3D 프린팅 방식의 총의치용 재료가 국민건강보험 적용 대상이 되었으며, 2026년 6월에는 적용 대상인 의치의 종류가 확대되었습니다.
프로토타이핑에서 기능성 수지 부품으로의 전환
산업 사용자들이 프로토타입에서, 프린팅 후에도 일관되게 기능해야 하는 실용 부품으로 전환함에 따라 적층 제조용 수지 시장의 지지가 확대되고 있습니다. 이러한 전환으로 인해 구매 우선순위는 기본적인 프린팅 적합성에서 피로, 굽힘 거동, 치수 정밀도 등 운영 조건 하에서의 성능으로 변화하고 있습니다. 기능적인 용도에는 일관된 기계적 특성, 보관 안정성, 재현성 있는 배치 성능, 그리고 이미 도입된 프린터 군에 적합한 가공 특성을 갖춘 수지가 요구됩니다. Formlabs는 사출 성형된 폴리프로필렌에 필적하는 피로 강도와 굽힘 성능을 실현하기 위해 2025년 3월 ‘Tough 1500 Resin’을 출시했습니다. 이 회사는 2025년 11월, ‘Tough 1000 Resin’ 및 개선된 버전인 ‘Tough 2000 Resin’을 발표하며, 내충격성 및 표면 품질 향상이 요구되는 조립용 기능성 소재 라인업을 확충했습니다. 양산 현장에서는 인증을 받은 수지가 지속적인 속도로 소비되며, 프로토타이핑 환경보다 더 엄격한 유변학 제어가 요구되기 때문에 검증된 배합은 사용자에게 더 높은 가치를 제공합니다.
인증된 엔지니어링 수지 및 생체적합성 수지의 높은 비용
높은 인증 비용은 적층 제조용 수지 시장에서 채택을 제약하는 요인이 되고 있으며, 특히 대량 생산을 통해 인증 비용을 분산시킬 수 없는 중소규모 의료·치과 분야 사용자에게는 큰 장벽이 되고 있습니다. ISO 10993에 기반한 세포 독성, 자극성, 감작성 시험에서는 수지가 인체 접촉 용도로 사용되기 전에 검증된 프로토콜, 기술 문서 및 관리된 후처리가 요구됩니다. Stratasys사의 ‘Somos BioClear’는 의료기기 용도로 ISO 10993-5, ISO 10993-10 및 미국 약전(USP) 클래스 VI 시험을 거쳤습니다. 인증된 등급은 표준 프로토타이핑용 등급에 비해 2-5배의 비용이 들 수 있어, 연구소나 비용에 민감한 제조 현장에서는 뚜렷한 가격 차이가 발생하고 있습니다. 헨켈 AG & Co. KGaA는 식품 모의 물질을 사용한 이온 이동 및 추출 시험을 거쳐, ‘Loctite 3D IND3785’에 대해 유럽연합(EU)의 10/2011호 식품 접촉 요건 준수를 목표로 했습니다. 유럽의 규정 준수 요건은 상용화까지의 일정을 장기화시킬 가능성이 있어, 대규모 규제 대응 팀, 검증된 시험 방법, 확립된 품질 시스템을 갖춘 공급업체에게 유리하게 작용합니다.
부문 분석
2025년 시점에서 광경화성 수지는 적층 제조용 수지 시장 점유율의 56.34%를 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 6.45%로 확대될 것으로 예측됩니다. 이러한 위상은 치과, 의료, 산업 용도로 사용되는 스테레오리소그래피(SLA), DLP, CLIP 플랫폼과의 폭넓은 호환성을 반영한 것으로, 공급업체는 관련 화학 플랫폼 및 용도 특화 배합을 통해 다양한 용도에 대응할 수 있게 되었습니다. 열가소성 수지는 용융 적층 방식(FDM) 시스템의 구조용 및 내열용도로 사용되었습니다. 이러한 소재는 50마이크론 미만의 해상도보다 유연성, 내열성 및 형상이 더 중요시되는 부품 설계에 대응했습니다. 에폭시 수지는 기계적 하중 하에서 치수 안정성이 요구되는 금형 및 복합재 적층용 맨드릴 용도에 대응했습니다.
폴리우레탄 수지는 적층 제조용 수지 시장 전체에서 엘라스토머 및 격자 구조 용도를 뒷받침했습니다. 이는 유연한 부품의 경우, 출력 후 변형을 제어해야 하기 때문입니다. 기타 수지에는 특수한 성능 요건을 충족하는 바이오 기반 및 세라믹 충전 복합재료가 포함되었습니다. Formlabs사는 40종 이상의 SLA용 소재를 제공했으며, Stratasys사는 까다로운 용도를 위해 ‘Somos BioClear’를 공급했습니다. 아르케마(Arkema)는 2025년 4월, 버지니아주 채텀과 펜실베이니아주 웨스트체스터에 위치한 서트마(Sartomer) 사업장에 대해 국제 지속가능성 탄소 인증(ISCC) PLUS 인증을 획득했습니다. 이 인증을 통해 바이오 유래 자외선 발광 다이오드(UV-LED)용 전자빔 수지 솔루션의 구현이 가능해졌습니다.
지역별 분석
2025년, 북미는 적층 제조용 수지 시장의 38.77% 점유율을 차지했습니다. 이 지역에는 생산 등급의 DLP 및 SLA 시스템 도입 기반이 깊게 자리 잡고 있으며, FDA 승인을 받은 광경화성 수지가 집중되어 있고, 디지털 기술에 뛰어난 치과 기공소가 다수 존재했습니다. 헨켈 AG & Co. KGaA는 2025년 9월 사우스다코타주 브랜든에 위치한 시설에서 3,000만 달러 규모의 확장 공사를 완료하여 해당 부지의 면적을 70,000제곱피트로 두 배로 늘렸으며, LOCTITE 브랜드 접착제 및 열 관리 소재의 생산 체계를 강화했습니다. 유럽은 계속해서 중요한 지역 거점으로서의 역할을 수행하고 있으며, 독일이 산업의 허브로 기능하고 있습니다.
독일의 규정 준수 요건은 고성능 및 문서화가 갖춰진 소재에 대한 투자를 촉진하고 있습니다. 이러한 요건에서는 추적성, 예측 가능한 가공성, 그리고 용도별 기준을 충족하는 능력이 중시되고 있습니다. 아시아태평양은 2031년까지 연평균 성장률(CAGR) 6.33%로 성장할 것으로 예측됩니다. 중국과 인도가 지역 매출을 견인하는 한편, 일본, 한국, 대만이 특수 수지 수요를 뒷받침하고 있습니다. 이러한 지역적 구성으로 인해 저비용 기능성 등급과 프리미엄 특수 배합재에 대해 서로 다른 요구 사항이 발생하고 있습니다.
일본에서는 3D 프린팅 의치용 재료에 대한 보험 적용이 2025년에 시작되어 2026년 6월에 확대되었습니다. 코베스트로(Covestro AG)는 중국 남부 주하이(珠海)에 열가소성 폴리우레탄 제조 시설을 개설했으며, 초기 연간 생산능력은 3만 메트르톤입니다. 남미, 중동 및 아프리카는 여전히 초기 단계의 시장이며, 인증 등급 소재에 대한 접근성이 제한적이어서 보급이 진전되지 않고 있습니다. 이 지역들은 수요 잠재력이 있지만, 유통 능력과 인증 비용이 여전히 큰 장벽으로 작용하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
- 조사 가정과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 밸류체인 분석
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 수지 유형별
- 최종 이용 산업별
- 지역별
- 아시아태평양
- 중국
- 인도
- 일본
- 한국
- ASEAN 국가
- 기타 아시아태평양 국가
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 북유럽 국가
- 기타 유럽 국가
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 중동 및 아프리카
- 사우디아라비아
- 남아프리카공화국
- 기타 중동 및 아프리카 국가
- 아시아태평양
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율·순위 분석
- 기업 개요
- 3D Systems, Inc.
- Arkema S.A.
- BASF
- Carbon, Inc.
- COVESTRO
- DWS S.r.l.
- Evonik Industries AG
- Formlabs
- Henkel AG & Co. KGaA
- Keystone Industries
- Photocentric Ltd
- Stratasys
- UnionTech
제7장 시장 기회와 향후 전망
KSM 26.10.29According to Mordor Intelligence, the additive manufacturing resins market size was valued at USD 57.12 billion in 2025 and is estimated to grow from USD 60.48 billion in 2026 to reach USD 80.48 billion by 2031, at a CAGR of 5.88% during the forecast period (2026-2031).
Global Additive Manufacturing Resins Market Trends and Insights
Demand for Patient-Specific Medical Components
Personalized medical manufacturing supports long-term demand for the additive manufacturing resins market because clinical parts require defined material performance and controlled production records. International Organization for Standardization (ISO) 10993-series biocompatibility standards increasingly define the qualification threshold for medical resin products, including products intended for repeated patient contact. Stratasys' P3 MED Silicone 25A is certified against ISO 10993-5, ISO 10993-10, and ISO 10993-23, and it is supported by a Food and Drug Administration (FDA) Master File for patient-specific wearable medical devices. FDA and European Union Medical Device Regulation (EU MDR) post-market surveillance requirements favor suppliers with validated supply chains, traceable batch records, and established documentation processes. These requirements can support multiyear supply arrangements because manufacturers must protect the validated process used for each clinical application. Japan included 3D-printed complete denture materials in national insurance coverage in 2025 and expanded the applicable denture types in June 2026.
Shift From Prototyping to Functional Resin Parts
The additive manufacturing resins market is gaining support as industrial users shift from prototypes toward functional parts that must work consistently after printing. This transition changes purchasing priorities from basic printability toward performance under operational conditions, including fatigue, flex behavior, and dimensional reliability. Functional applications require resins with consistent mechanical properties, shelf stability, repeatable batch performance, and processing characteristics that suit the installed printer base. Formlabs launched Tough 1500 Resin in March 2025 to address fatigue and flex performance comparable with injection-molded polypropylene. The company introduced Tough 1000 Resin and an improved Tough 2000 Resin in November 2025, extending its functional materials range for assemblies that require impact resistance and improved surface quality. Production operations consume qualified resin at sustained rates and require tighter rheological control than prototyping environments, making validated formulations more valuable to users.
High Cost of Certified Engineering and Biocompatible Resins
High certification costs constrain adoption in the additive manufacturing resins market, particularly among smaller medical and dental users who cannot spread qualification expenses across high production volumes. ISO 10993 cytotoxicity, irritation, and sensitization testing requires validated protocols, technical documentation, and controlled post-processing before a resin can serve body-contact applications. Stratasys' Somos BioClear underwent ISO 10993-5, ISO 10993-10, and United States Pharmacopeia Class VI testing for medical device applications. Certified grades can cost 2-5 times more than standard prototyping grades, creating a clear price gap for laboratories and cost-sensitive manufacturing operations. Henkel AG & Co. KGaA pursued European Union 10/2011 food-contact requirements for Loctite 3D IND3785 after migration and extraction testing across food simulants. European compliance requirements can lengthen commercialization schedules and favor suppliers with larger regulatory teams, proven testing methods, and established quality systems.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Production-Grade Dental Workflows
- Adoption of High-Throughput DLP and CLIP Platforms
- Proprietary Printer-Resin Qualification Lock-In
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Photopolymer resins held 56.34% of the additive manufacturing resins market share in 2025 and are projected to advance at a 6.45% CAGR through 2031. Their position reflected broad compatibility with stereolithography (SLA), DLP, and CLIP platforms used in dental, medical, and industrial applications, allowing suppliers to address multiple uses with related chemistry platforms and application-specific formulations. Thermoplastic resins served structural and high-temperature uses on fused deposition modeling (FDM) systems. These materials supported part designs where flexibility, temperature resistance, and geometry were more important than sub-50-micron resolution. Epoxy resins addressed tooling and composite lay-up mandrel applications that required dimensional stability under mechanical loading.
Polyurethane resins supported elastomeric and lattice applications across the additive manufacturing resins market because flexible components require controlled deformation after printing. Other resins included bio-based and ceramic-filled composites that addressed specialized performance requirements. Formlabs offered more than 40 SLA materials, while Stratasys supplied Somos BioClear for demanding applications. Arkema obtained International Sustainability and Carbon Certification (ISCC) PLUS certification for Sartomer sites in Chatham, Virginia, and West Chester, Pennsylvania, in April 2025. The certification enabled bio-attributed ultraviolet light-emitting diode electron beam resin solutions.
Complete Report Scope:
- By Resin Type
- Photopolymer Resins
- Thermoplastic Resins
- Epoxy Resins
- Polyurethane Resins
- Other Resins
- By End-Use Industry
- Healthcare
- Automotive
- Aerospace and Defense
- Industrial Manufacturing
- Consumer Goods
- Other End-Use Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
North America held 38.77% of the additive manufacturing resins market share in 2025. The region had a deep installed base of production-grade DLP and SLA systems, a high concentration of FDA-cleared photopolymer materials, and digitally advanced dental laboratories. Henkel AG & Co. KGaA completed a USD 30 million expansion of its Brandon, South Dakota, facility in September 2025, doubling the site to 70,000 square feet for LOCTITE-branded adhesives and thermal management materials Europe continued to serve as a significant regional base, with Germany acting as an industrial hub.
German compliance requirements support investment in materials with advanced performance and documentation. These requirements place emphasis on traceability, predictable processing, and the ability to meet application-specific standards. Asia-Pacific is projected to advance at a 6.33% CAGR through 2031. China and India support regional revenue, while Japan, South Korea, and Taiwan support specialty resin demand. The regional mix creates different requirements for lower-cost functional grades and premium specialty formulations.
Japan's insurance coverage of 3D-printed denture materials began in 2025 and expanded in June 2026. Covestro AG opened a thermoplastic polyurethane facility in Zhuhai, South China, with an initial annual capacity of 30,000 metric tons. South America, the Middle East, and Africa remain early-stage markets where access to certified-grade materials limits adoption. These regions have demand potential, but distribution capacity and certification costs remain significant barriers.
- 3D Systems, Inc.
- Arkema S.A.
- BASF
- Carbon, Inc.
- COVESTRO
- DWS S.r.l.
- Evonik Industries AG
- Formlabs
- Henkel AG & Co. KGaA
- Keystone Industries
- Photocentric Ltd
- Stratasys
- UnionTech
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of Production-Grade Dental Workflows
- 4.2.2 Shift From Prototyping to Functional Resin Parts
- 4.2.3 Demand for Patient-Specific Medical Components
- 4.2.4 Adoption of High-Throughput DLP and CLIP Platforms
- 4.2.5 Printer-Qualified Open Material Ecosystems
- 4.3 Market Restraints
- 4.3.1 High Cost of Certified Engineering and Biocompatible Resins
- 4.3.2 Proprietary Printer-Resin Qualification Lock-In
- 4.3.3 Photoinitiator and Oligomer Supply Concentration
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Resin Type
- 5.1.1 Photopolymer Resins
- 5.1.2 Thermoplastic Resins
- 5.1.3 Epoxy Resins
- 5.1.4 Polyurethane Resins
- 5.1.5 Other Resins
- 5.2 By End-Use Industry
- 5.2.1 Healthcare
- 5.2.2 Automotive
- 5.2.3 Aerospace and Defense
- 5.2.4 Industrial Manufacturing
- 5.2.5 Consumer Goods
- 5.2.6 Other End-Use Industries
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 ASEAN Countries
- 5.3.1.6 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 NORDIC Countries
- 5.3.3.6 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 3D Systems, Inc.
- 6.4.2 Arkema S.A.
- 6.4.3 BASF
- 6.4.4 Carbon, Inc.
- 6.4.5 COVESTRO
- 6.4.6 DWS S.r.l.
- 6.4.7 Evonik Industries AG
- 6.4.8 Formlabs
- 6.4.9 Henkel AG & Co. KGaA
- 6.4.10 Keystone Industries
- 6.4.11 Photocentric Ltd
- 6.4.12 Stratasys
- 6.4.13 UnionTech
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


