

|
시장보고서
상품코드
2154742
산업용 탈지제 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Industrial Degreaser - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
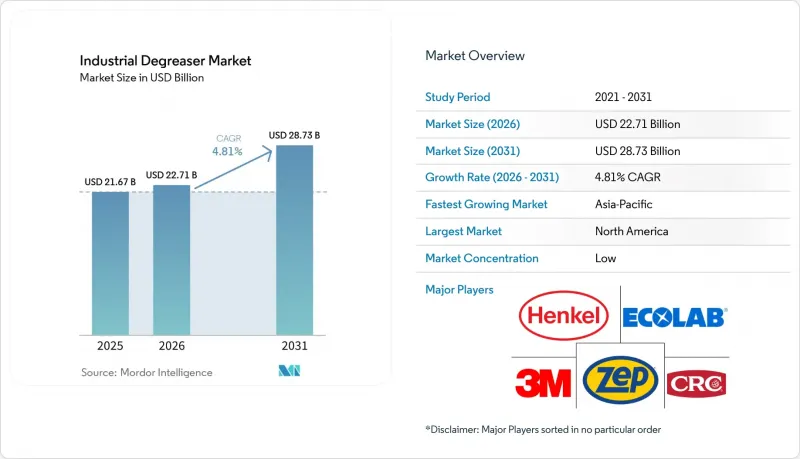
에 따르면 산업용 탈지제 시장 규모는 2025년에 216억 7,000만 달러로 평가되며, 2026년 227억 1,000만 달러에서 2031년까지 287억 3,000만 달러에 달할 것으로 예측되며, 예측 기간(2026-2031년) 동안 CAGR은 4.81%가 될 전망입니다.
세계 산업용 탈지제 시장의 동향 및 인사이트
산업용 설비의 유지보수 및 가동 중단 시간 단축
정기적인 탈지 작업은 주조소, 프레스 공장, 해상 에너지 시설 및 화학 처리 시설에서 예방 정비 활동의 역할을 합니다. 그리스나 기름의 침전물은 베어링의 마모를 가속화하고 마찰 손실을 증가시키며, 회전 장비의 열적 고장의 원인이 될 수 있습니다. 2025년에는 산업 분야의 에너지 효율화 투자액이 연간 2,000억 달러를 넘어설 것으로 예상되며, 에너지 손실이 적고 가동 중단 횟수가 적은 설비에 대한 관심이 높아지고 있습니다. IoT(사물인터넷)를 활용한 예측 유지보수 플랫폼을 통해 계측 기기가 도입된 시설 전체의 설비 상태에 대한 가시성이 높아지고 있습니다. 이러한 시스템은 실시간 경보를 발령하여 보다 정확하게 계획된 세척 작업을 지원합니다. 따라서 각 유지보수 작업에서 사용되는 세척액의 양이 일정하더라도, 시설의 유지보수 빈도가 높아지면 산업용 탈지제 시장은 그 혜택을 누리게 될 것입니다.
자동차 생산 및 부품 정비
자동차 생산에서는 화이트 바디 제조, E-코팅(전착도장) 표면 처리, 파워트레인 조립, 그리고 변속기 부품 세척 시 탈지 처리가 필요합니다. 2023년 전 세계 자동차 생산 대수는 9,300만 대를 넘어섰으며, 이러한 회복세는 2024년과 2025년에도 이어졌습니다. 퀘이커 호튼(Quaker Horton)사는 잔류물이 적고 진공 건조에 적합한 용도를 위해 ‘QUAKERCLEAN 680 Verband der Automobilindustrie(VDA)’를 개발했으며, 이 제품은 자동차 OEM 각 사로부터 승인을 획득했습니다. 애프터마켓 및 유지보수·수리·운영(MRO) 분야도 수요를 뒷받침하고 있습니다. 이는 노후 차량 차량군에서 부품 세척이나 엔진 세척이 필요하기 때문입니다. 전기자동차(EV) 생산은 탈지 필요성을 없애는 것이 아니라, 배터리 모듈 및 파워 일렉트로닉스에 대한 세척 요건을 추가하게 되어 산업용 탈지제 시장을 뒷받침하고 있습니다. 2025년 7월 VDA 19.1 개정판에는 배터리 모듈 하우징 및 파워 일렉트로닉스에 적용되는 기술적 청정도 요건이 포함되었습니다.
화학제품의 등록, 시험 및 문서화 부담
산업용 탈지제 시장의 신제품은 유럽연합(EU)의 화학제품 규제, 미국의 유해물질 규제법(TSCA), 중국의 GB/T 규격 및 기타 국가의 화학제품 목록에 기반한 중복되는 요건을 충족해야 합니다. 이러한 규제 체계에서는 독성학적 자료 제출 및 생분해성 시험이 요구됩니다. 또한, 미세 플라스틱과 퍼플루오로알킬 물질(PFAS) 및 폴리플루오로알킬 물질(PFAS)에 대한 대응도 점점 더 중요해지고 있습니다. 중규모 배합 제조업체의 경우, 각 SKU(재고 관리 단위)별 등록 비용은 신제품 출시 활동을 제한하고 대응 가능한 시장을 좁히는 요인이 될 수 있습니다. BASF는 등록 비용을 광범위한 제품 포트폴리오와 여러 지역에 분산시킬 수 있지만, 지역 밀착형 배합 제조업체는 단일 바이오 기반 제품에 대해 막대한 시험 비용을 부담하게 됩니다. 이러한 차이로 인해 규정 준수 대응 자원이 풍부한 기업에 신제품 출시가 집중되어, 특수 용도에서의 선택지가 줄어들 가능성이 있습니다.
부문 분석
2025년 기준, 수성 제품은 산업용 탈지제 시장 규모의 56.16%를 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 5.56%로 확대될 것으로 예측됩니다. 이러한 위상을 뒷받침하는 것은 단순한 환경 고려뿐만 아니라 규제 요건 때문입니다. 미국 환경보호청(EPA)의 규제 기술 지침은 산업용 세정 용매에서 발생하는 휘발성 유기 화합물(VOC) 배출을 규제하고 있습니다. 또한, 수성 제품은 환경 인증 및 OEM(주문자 상표 생산) 사양과 연계된 조달 요건도 충족하고 있습니다. 산업용 탈지제 시장은 수성 스프레이 세정 시스템을 널리 도입하고 있는 자동차 조립 공장으로부터도 혜택을 받고 있으며, 수성 화학제품에 대해 장기적으로 안정적인 설비 기반이 형성되고 있습니다.
용제계 제품은 속건성, 정전기 공정과의 호환성, 혹은 복잡한 형상에 대한 침투성이 요구되는 상황에서는 여전히 중요한 역할을 수행하고 있습니다. 규제로 인해 특정 용제군이 상업적 용도에서 배제되면 그 적용 범위는 좁아집니다. 산업용 탈지제 업계는 검증된 공정 조건을 훼손하지 않으면서도 더 낮은 휘발성 유기 화합물(VOC) 배출 기준을 충족하는 제품으로 계속해서 전환하고 있습니다. 이러한 성장은 다국적 OEM 제조업체들이 공급망 전반에 걸쳐 일관된 세정 사양을 적용하고 있는 아시아태평양의 수출 지향적 제조 환경에 집중되어 있었습니다.
지역별 분석
2025년, 북미는 산업용 탈지제 시장 규모의 38.05%를 차지했습니다. 이 지역에는 고강도 세정 공정을 채택하는 자동차 OEM, 중장비 제조업체, 제약 회사, 항공우주 기업이 포함됩니다. 캘리포니아주에서는 에어로졸형 탈지제에 대해 주 내에서 판매되는 제품의 휘발성 유기 화합물(VOC) 함량을 10% 미만으로 제한하는 요건이 마련되어 있습니다. 미국 전역에 걸쳐 광범위한 유통을 목표로 하는 공급업체는 이 요건을 고려해야 합니다. 멕시코의 자동차 제조 회랑은 통합된 북미 공급망 전반에 걸친 유지보수, 수리 및 운영(MRO) 수요를 뒷받침하고 있습니다.
유럽 산업용 탈지제 시장의 수요는 독일, 영국, 프랑스, 이탈리아에 집중되어 있으나, 유럽연합(EU)의 화학제품 규제로 인해 2020년부터 2025년까지 할로겐화 및 염소화 용제계 제품의 적용 범위가 축소되었습니다. Henkel AG & Co. KGaA는 2026년 2월, 기존 공정 온도인 60℃-65℃에 비해 35℃-40℃에서 침지 세척용으로 ‘본데라이트 C-AD 20202’를 출시했습니다. AGCO/펜트사는 2025년 5월, 아스바흐-바우멘하임 공장에서 해당 제품을 도입하여 인산아연도금의 품질을 유지하면서도 하루 1,000킬로와트시(kWh)의 에너지 절감을 실현했습니다. 스웨덴 뫼르비에 위치한 토요타 자재관리 시설에서는 2025년 초 호스 세척용 저온 수성 탈지제로 전환한 결과, 에너지 소비량을 40% 절감했다고 보고되었습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 5.74%로 확대될 것으로 예측됩니다. 중국, 인도, 한국 및 동남아시아 국가 연합(ASEAN)의 제조 허브는 자동차, 전자기기, 기계, 배터리 생산을 통해 산업용 탈지제 시장의 수요를 뒷받침하고 있습니다. 중국의 자동차 및 전자기기 제조 규모가 절대적인 소비량을 뒷받침하는 한편, 인도의 제조업 투자는 자동차, 제약, 전자기기 생산 분야의 수요를 지탱하고 있습니다. 한국의 반도체 및 배터리 제조 거점에서는 국제반도체장비재료협회(SEMI)의 요건을 충족하는 초고순도 수성 세정제가 요구되고 있습니다. 남미는 브라질과 아르헨티나를 중심으로 하며, 자동차 산업 및 농업 기계의 유지보수가 수요를 뒷받침하고 있습니다. 반면, 중동 및 아프리카는 석유·가스 장비의 유지보수에 크게 의존하고 있습니다. BASF와 Brenntag가 체결한 2026년 판매 계약은 남아프리카공화국, 나이지리아, 가나, 케냐, 우간다, 탄자니아, 에티오피아의 세정 제품을 대상으로 합니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
- 조사 가정과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 밸류체인 분석
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 유형별
- 등급별
- 용도별
- 지역별
- 아시아태평양
- 중국
- 인도
- 일본
- 한국
- 기타 아시아태평양 국가
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 기타 유럽 국가
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 중동 및 아프리카
- 사우디아라비아
- 남아프리카공화국
- 기타 중동 및 아프리카 국가
- 아시아태평양
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율·순위 분석
- 기업 개요
- 3M
- A.W. Chesterton Company
- BASF
- Bio-Circle Surface Technology GmbH
- Callington Haven Pty Ltd
- CRC Industries
- Dow
- Ecolab Inc.
- Henkel AG & Co. KGaA
- ITW Pro Brands
- NCH Corporation
- Quaker Houghton
- Stepan Company
- WD-40 Company
- Zep Inc.
제7장 시장 기회와 향후 전망
KSM 26.10.29According to Mordor Intelligence, the industrial degreaser market size was valued at USD 21.67 billion in 2025 and is estimated to grow from USD 22.71 billion in 2026 to reach USD 28.73 billion by 2031, at a CAGR of 4.81% during the forecast period (2026-2031).
Global Industrial Degreaser Market Trends and Insights
Industrial Equipment Maintenance and Downtime Reduction
Regular degreasing serves as a preventive maintenance activity in foundries, stamping plants, offshore energy facilities, and chemical processing sites. Grease and oil deposits can accelerate bearing wear, increase friction losses, and contribute to thermal failures in rotating equipment. Industrial energy-efficiency investment exceeded USD 200 billion annually in 2025, placing greater attention on equipment that runs with lower energy losses and fewer stoppages. Internet of Things (IoT)-enabled predictive maintenance platforms are increasing the visibility of equipment conditions across instrumented facilities. These systems can issue real-time alerts and support more precisely scheduled cleaning interventions. The industrial degreaser market, therefore, benefits when facilities perform more frequent maintenance events, even if the fluid volume used in each event remains stable.
Automotive Production and Component Servicing
Vehicle production requires degreasing during body-in-white fabrication, e-coat surface preparation, powertrain assembly, and transmission component cleaning. Global motor vehicle production exceeded 93 million units in 2023, and the recovery continued through 2024 and 2025. Quaker Houghton developed QUAKERCLEAN 680 Verband der Automobilindustrie (VDA) for low-residue and vacuum-drying applications, and the product carries automotive original equipment manufacturer approvals. Aftermarket and maintenance, repair, and operations channels also support demand because older vehicle fleets require parts washing and engine cleaning. Electric vehicle production adds cleaning requirements for battery modules and power electronics rather than removing the need for degreasing, supporting the industrial degreaser market. The July 2025 update to VDA 19.1 covered technical cleanliness requirements that apply to battery module housings and power electronics.
Chemical Registration, Testing and Documentation Burden
New products in the industrial degreaser market must meet overlapping requirements under the European Union regulation on chemicals, the Toxic Substances Control Act in the United States, GB/T standards in China, and country-level chemical inventories elsewhere. These frameworks require toxicological dossiers and biodegradability testing. They increasingly address microplastics and per- and polyfluoroalkyl substances (PFAS). For mid-sized formulators, registration expenses for each stock-keeping unit can limit product launch activity and narrow the markets they can serve. BASF can spread registration spending over a broad portfolio and multiple regions, while a regional formulator may bear substantial testing costs for a single bio-based product. This difference can concentrate new product launches among companies with stronger compliance resources and reduce choice in specialized applications.
Other drivers and restraints analyzed in the detailed report include:
- VOC and Hazardous-Solvent Substitution
- EV and Semiconductor Contamination-Control Requirements
- Feedstock and Specialty-Solvent Price Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Water-based held 56.16% of the industrial degreaser market size in 2025 and is projected to advance at a 5.56% CAGR through 2031. Regulatory requirements, rather than environmental preference alone, supported this position. U.S. Environmental Protection Agency control techniques guidelines address volatile organic compound emissions from industrial cleaning solvents. Water-based formats also fit procurement requirements tied to environmental certifications and original equipment manufacturer specifications. The industrial degreaser market also benefits from automotive assembly plants that widely use aqueous spray-wash systems, creating a long-lived equipment base for water-based chemistry.
Solvent-based products remain relevant where fast drying, compatibility with electrostatic processes, or penetration into complex geometries is required. Their addressable use narrows when regulation removes solvent classes from commercial use. The industrial degreaser industry continues to shift toward products that meet lower volatile organic compound requirements without disrupting validated process conditions. This growth was concentrated in Asia-Pacific export-oriented manufacturing environments where multinational original equipment manufacturers apply consistent cleaning specifications across supply chains.
Complete Report Scope:
- By Type
- Water-Based
- Solvent-Based
- By Grade
- Liquid-Based
- Petroleum-Based
- Bio-Based
- Other Grades
- By Application
- Automotive
- Manufacturing and Industrial Machinery
- Pharmaceutical
- Aerospace
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
North America held 38.05% of the industrial degreaser market size in 2025. The region includes automotive original equipment manufacturers, heavy machinery producers, pharmaceutical manufacturers, and aerospace companies that use high-intensity cleaning processes. California requirements for aerosol degreasers limit volatile organic compound content to below 10% for products sold in the state. Suppliers seeking broad U.S. distribution must account for this requirement. Mexico's automotive manufacturing corridor supports maintenance, repair, and operations demand across integrated North American supply chains.
Europe's industrial degreaser market demand is centered on Germany, the United Kingdom, France, and Italy, while the European Union chemicals framework reduced the addressable use of halogenated and chlorinated solvent-based products between 2020 and 2025. Henkel AG & Co. KGaA launched Bonderite C-AD 20202 in February 2026 for dip-process cleaning at 35 °C to 40 °C, compared with conventional process temperatures of 60 °C to 65 °C. AGCO/Fendt adopted the product in May 2025 at its Asbach-Baumenheim site and saved 1,000 kilowatt-hours (kWh) per day while maintaining zinc phosphate coating quality. A Toyota Material Handling facility in Mjolby, Sweden, reported a 40% energy reduction after changing to a low-temperature aqueous degreaser for hose cleaning in early 2025.
Asia-Pacific is projected to advance at a 5.74% CAGR through 2031. China, India, South Korea, and the Association of Southeast Asian Nations manufacturing corridor support the industrial degreaser market demand through automotive, electronics, machinery, and battery production. China's scale in automotive and electronics manufacturing supports absolute consumption, while India's manufacturing investment supports demand in automotive, pharmaceutical, and electronics production. South Korea's semiconductor and battery manufacturing base requires ultra-high-purity aqueous cleaners that meet Semiconductor Equipment and Materials International requirements. South America is centered on Brazil and Argentina, where automotive activity and agricultural equipment maintenance support demand, while the Middle East and Africa depend materially on oil and gas equipment maintenance. BASF's 2026 distribution agreement with Brenntag covers cleaning products in South Africa, Nigeria, Ghana, Kenya, Uganda, Tanzania, and Ethiopia.
- 3M
- A.W. Chesterton Company
- BASF
- Bio-Circle Surface Technology GmbH
- Callington Haven Pty Ltd
- CRC Industries
- Dow
- Ecolab Inc.
- Henkel AG & Co. KGaA
- ITW Pro Brands
- NCH Corporation
- Quaker Houghton
- Stepan Company
- WD-40 Company
- Zep Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Industrial Equipment Maintenance and Downtime Reduction
- 4.2.2 Automotive Production and Component Servicing
- 4.2.3 VOC and Hazardous-Solvent Substitution
- 4.2.4 Pharmaceutical and High-Purity Manufacturing Expansion
- 4.2.5 Low-Temperature Degreasing for Energy and Carbon Reduction
- 4.2.6 EV and Semiconductor Contamination-Control Requirements
- 4.3 Market Restraints
- 4.3.1 Chemical Registration, Testing and Documentation Burden
- 4.3.2 Feedstock and Specialty-Solvent Price Volatility
- 4.3.3 Validation Risk When Replacing Solvents in Critical Processes
- 4.3.4 Wastewater Load and Effluent-Treatment Constraints
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Water-Based
- 5.1.2 Solvent-Based
- 5.2 By Grade
- 5.2.1 Liquid-Based
- 5.2.2 Petroleum-Based
- 5.2.3 Bio-Based
- 5.2.4 Other Grades
- 5.3 By Application
- 5.3.1 Automotive
- 5.3.2 Manufacturing and Industrial Machinery
- 5.3.3 Pharmaceutical
- 5.3.4 Aerospace
- 5.3.5 Other Applications
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 3M
- 6.4.2 A.W. Chesterton Company
- 6.4.3 BASF
- 6.4.4 Bio-Circle Surface Technology GmbH
- 6.4.5 Callington Haven Pty Ltd
- 6.4.6 CRC Industries
- 6.4.7 Dow
- 6.4.8 Ecolab Inc.
- 6.4.9 Henkel AG & Co. KGaA
- 6.4.10 ITW Pro Brands
- 6.4.11 NCH Corporation
- 6.4.12 Quaker Houghton
- 6.4.13 Stepan Company
- 6.4.14 WD-40 Company
- 6.4.15 Zep Inc.
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


