

|
시장보고서
상품코드
2154783
치과용 압전 초음파 장치 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Dental Piezoelectric Ultrasonic Unit - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
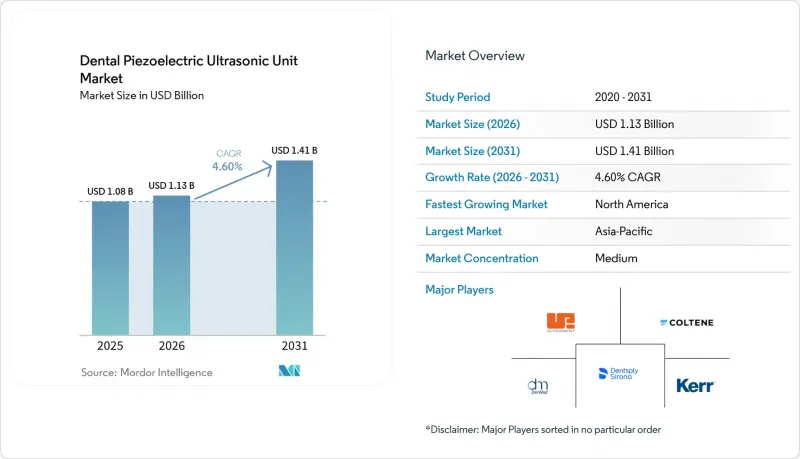
에 따르면 치과용 압전 초음파 장치 시장 규모는 2025년 10억 8,000만 달러에서 2026년에는 11억 3,000만 달러로 확대되어, 2026년부터 2031년까지 CAGR 4.60%를 기록하며 2031년까지 14억 1,000만 달러에 달할 것으로 예측됩니다.
전 세계 치과용 압전 초음파 장치 시장의 동향 및 인사이트
치주질환 치료 건수의 증가
2021년에는 전 세계적으로 10억 7,000만 명이 중증 치주염을 앓고 있었으며, 치주 조직의 데브리드먼트는 치과용 압전 초음파 기기 시장에서 여전히 핵심적인 위치를 차지하고 있습니다. 세계보건기구(WHO)는 ‘2023년부터 2030년까지의 세계 구강보건 행동 계획’에 따라 보고 목표를 설정했습니다. 이러한 목표는 각국의 정부 부처에 예방적 구강보건 서비스 강화를 촉구하는 것입니다. 따라서 질병 부담이 큰 국가에서는 공립 클리닉이나 대학 부속 병원이 더 중요한 장비 구매 주체가 될 가능성이 있습니다. 이러한 기관의 대규모 구매에서는 고급 통합형 시스템보다 중저가대의 탁상형 장비가 선호되는 경향이 있습니다. 2021년, 남아시아에서는 3억 1,000만 건의 중증 치주염 사례가 확인되었으며, 인도와 중국은 공공 및 민간 치과 장비 투자 분야에서 중요한 시장으로 부상하고 있습니다. 2040년까지의 전망에 따르면, 질병 부담은 계속해서 증가할 것으로 예상되며, 이는 단순한 장비 교체 주기를 넘어서는 수요를 뒷받침하는 요인이 될 것입니다.
임플란트 치료 및 골 관리 시술의 확대
임플란트학의 발전에 따라, 치과용 압전 초음파 기기 시장은 일상적인 예방 처치의 범위를 넘어 확대되고 있습니다. 압전식 절삭은 인접한 연조직이나 신경·혈관 구조와의 접촉을 최소화하면서 석회화 조직을 처리할 수 있기 때문에 외과적 시술의 준비 단계에서 활용되고 있습니다. 이에 따라 상악동 거상술, 치조골 증대술 및 임플란트 주변 수술에서의 사용이 촉진되고 있습니다. Neocis사는 2025년 11월, 최소침습 임플란트 수술용 FDA 승인 ‘Yomi S’ 시스템을 출시했습니다. 임플란트 식립 시 정밀도가 향상됨에 따라, 이에 선행하는 외과적 시술의 정밀도에 대한 기대도 높아지고 있습니다. ‘구강외과 및 임플란트학’ 시장은 2031년까지 연평균 성장률(CAGR) 6.1%로 성장할 것으로 예측되며, 이는 시장 전체 성장률인 4.6%를 상회하는 수치입니다. 아시아태평양에서는 고령화, 가처분 소득 증가, 민간 클리닉 수 확대가 맞물려 임플란트 시술 수요를 뒷받침하고 있습니다.
소규모 진료소의 높은 초기 투자 비용
치과용 압전 초음파 장치 시장에서 자본 비용은 독립형 및 지방 치과 병원에 여전히 큰 장벽으로 작용하고 있습니다. 일부 신흥 시장에서는 대출이나 리스 옵션이 제한적입니다. 고성능 다기능 시스템은 이익률이 낮은 소규모 치과 병원의 구매 능력을 초과할 수 있습니다. DSO(치과 진료소 운영 조직)가 사업 규모를 확대하고 있음에도 불구하고, 많은 현역 치과 병원은 여전히 독립적인 형태를 유지하고 있습니다. 비용 압박으로 인해 수요가 완전히 사라지는 것이 아니라, 저가형 중국산 스케일러로 전환되는 경우가 많습니다. 이로 인해 초급 수준의 수요는 유지되지만, 고성장 지역에서 프리미엄 공급업체가 확보할 수 있는 시장 점유율은 제한됩니다. 트레이드인 프로그램이나 소모품과 연계된 구매 플랜은 가격에 민감한 구매자에게 더 이용하기 쉬운 지속적인 거래 관계를 구축할 수 있습니다.
부문 분석
2025년, 압전식 초음파 스케일러는 치과용 압전식 초음파 기기 시장 점유율의 48.6%를 차지했습니다. 이는 치주 치료 체계를 구축하는 클리닉이나 그룹 진료소에 있어 여전히 주요 설비 투자 대상입니다. ‘핸드피스 및 팁’ 시장은 2031년까지 연평균 성장률(CAGR) 5.8%로 성장할 것으로 예측됩니다. 이 성장률은 시장 전체의 예측치 및 자본 설비에 기대되는 성장률을 상회합니다. 제어 유닛이 1대 추가 도입될 때마다 향후 핸드피스 및 팁 교체 수요가 발생합니다. 따라서 진료소가 유닛 전체 교체를 미루더라도 소모품 구매는 계속됩니다. 주요 공급업체들은 이러한 교체 주기를 강화하기 위해 폭넓은 독자적인 팁 라이브러리를 활용하고 있습니다.
치과용 압전 초음파 장치 시장도 제품과 치료 플랫폼의 경계에서 변화하고 있습니다. 초음파 기능이 에어 폴리싱이나 레이저 모듈과 결합되는 사례가 늘고 있습니다. 이를 통해 조달 담당자는 단일 스케일러가 아닌 예방 치료 시스템 전체를 평가할 수 있게 됩니다. 이러한 추세로 인해 일부 설비 투자가 보다 광범위한 플랫폼 범주로 이동할 가능성이 있습니다. 각 임상 모드에는 해당 용도에 특화된 팁이 필요하기 때문에 핸드피스와 팁은 여전히 중요한 위치를 차지하고 있습니다. 치은 하부, 치은 상부, 치내 치료 및 외과적 시술에는 각각 서로 다른 팁 설계가 필요할 수 있습니다. 액세서리 및 유지보수 도구는 여전히 가장 규모가 작은 제품군입니다. 또한, 독자적인 사양의 호환성 요건으로 인해 범용 액세서리 공급업체가 진입할 수 있는 여지는 좁아지고 있습니다.
2025년, 치과 클리닉은 치과용 압전 초음파 장치 시장의 52.4%를 차지했습니다. 치과 클리닉은 여전히 치주 치료를 제공하는 주요 장소입니다. 그룹 치과 진료소는 2031년까지 연평균 성장률(CAGR) 5.6%로 확대될 것으로 예측됩니다. 이는 구매 결정권이 개별 치과의사로부터 여러 진료소를 보유한 치과 조직으로 이동하고 있음을 반영합니다. DSO(치과 서비스 조직)는 통합된 처방 목록을 활용하여 각 진료소 간 브랜드와 기종을 표준화하고 있습니다. 이를 통해 네트워크가 장비 표준을 변경할 때 교체 주기를 단축할 수 있습니다. 또한, 확고한 입지를 갖춘 공급업체가 기업용 서비스 지원을 제공할 때도 경쟁 우위를 확보할 수 있습니다.
병원, 외래 수술 센터 및 학술 기관은 규모가 작은 최종사용자 그룹입니다. 이들은 복잡한 시술, 연구 및 임상의 연수를 뒷받침하고 있으므로 전략적으로 중요한 존재로 남아 있습니다. 학술 기관은 진료소나 DSO의 구매 결정을 좌우하는 근거를 제시할 수 있습니다. 초음파 기기의 비교 연구는 여전히 임상 프로토콜 선택에 영향을 미치고 있습니다. 제조사는 당장의 매출 규모가 작더라도 연구용 기기 제공이나 학술 기관과의 제휴를 놓고 경쟁을 벌이는 경우가 있습니다. 이러한 관계는 향후 치료 관행이나 보험 적용 품목 선정에 영향을 미칠 가능성이 있습니다. 따라서 치과용 압전식 초음파 기기 업계는 일상적인 임상 수요와 학술적 근거 구축 모두에 의존하고 있습니다. 그룹 진료소의 확대는 독립 진료소의 역할을 배제하는 것은 아니지만, 주요 구매 결정이 이루어지는 장소를 변화시킵니다.
지역별 분석
2025년, 북미는 치과용 압전 초음파 장치 시장의 40.8%를 차지했습니다. 미국은 민간 치과 네트워크가 밀집해 있고, 훈련된 임상 인력을 보유하고 있으며, DSO 통합이 진행되고 있어 지역 수요를 주도하고 있습니다. 구매 동향은 개별 치과에서 그룹 차원의 처방 관리로 전환되고 있습니다. 하트랜드 덴탈이 2025년 12월 기업용 실험실 관리 시스템으로 덴티라를 선정한 배경에는, 해당 기업의 임상 용품 조달에 대한 협력 관계가 있었습니다. 캐나다는 성숙한 치주병 치료 기반을 갖추고 있습니다. 멕시코는 규모는 작지만 발전 중인 시장이며, 민간 클리닉의 확장이 지방의 공공 시설에 대한 투자를 상회하고 있습니다. 2031년까지의 지역적 성장은 신규 도입보다는 주로 장비 교체에 기인할 것으로 예상됩니다.
유럽은 치과용 압전식 초음파 기기 분야에서 2위 지역 시장입니다. 독일, 영국, 프랑스, 이탈리아, 스페인이 이 지역의 수요 대부분을 차지하고 있습니다. 독일은 민간 진료소의 밀집된 분포와 확립된 보험 환급 체계의 혜택을 받고 있습니다. 이 지역에는 오스트리아의 W&H와 이탈리아의 Mectron과 같은 주요 공급업체도 존재합니다. 이러한 입지 조건은 장비 유통과 서비스 제공을 뒷받침하고 있습니다. 규제 요건은 확립된 적합성 문서를 보유한 브랜드에 유리하게 작용할 수 있습니다. ISO 18397:2025에는 전동 스케일러 및 그 팁에 관한 최신 요건이 추가되었습니다. 동유럽 시장에서는 진료소 인프라 투자가 증가함에 따라 성장이 나타나고 있습니다. 이 지역의 동향은 서유럽의 성숙한 수요와 신흥 진료소 네트워크의 발전 중인 수요가 결합된 결과입니다. 진료소는 핸드피스 및 팁에 대한 적시 지원에 의존하고 있으므로 서비스망 구축이 중요합니다. 따라서 현지 기반 판매 대리점은 브랜드 선정에 영향을 미칠 수 있습니다. 규제 준수 및 유통 역량은 지역 간 경쟁에서 상호 작용합니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 5.3%로 성장할 것으로 예측되며, 치과용 압전 초음파 장치 시장에서 가장 높은 지역 성장률을 보이고 있습니다. 중국에서는 민간 클리닉이 수입 장비와 국산 장비를 모두 구매하고 있어, 가장 큰 판매량 기회가 기대됩니다. 중국에서는 2030년까지 8만 대의 새로운 치과용 의자가 도입될 계획입니다. 인도 역시 치주질환에 대한 인식 제고, 중산층 확대, 공공 구강 보건에 대한 투자로 인해 시장이 확대되고 있습니다. 일본에서는 고령화가 진행되고 고령층에 치주질환이 만연함에 따라 유지 관리 및 스케일링 수요가 뒷받침되고 있습니다. 한국과 호주에서는 임플란트 치료의 보급과 치과의사들의 고정밀 장비 투자를 통해 프리미엄 제품에 대한 수요가 지지를 받고 있습니다. 중동 및 아프리카 및 남미는 여전히 규모가 작고 서비스가 충분히 제공되지 않는 지역이지만, 브라질과 멕시코가 국가 차원에서 중요한 성장 동력이 되고 있습니다. 이러한 지역에서는 장비의 가격 경쟁력이 특히 중요합니다. 공급업체는 가격, 현지 서비스, 소모품의 입수 용이성 간의 균형을 수시로 고려해야 합니다. 프리미엄 플랫폼 도입 자금 조달이 어려운 시장에서는 엔트리 레벨 제품을 통해 도입 대수를 확대할 수 있습니다. 진료소 인프라가 정비됨에 따라, 이러한 시장에서는 보다 광범위한 치료 시스템에 대한 수요도 발생할 가능성이 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
- 조사 가정과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 가치 및 공급망 분석
- 규제 상황
- 기술 전망
- Porter's Five Forces 분석
- 가격 분석
- 시장 위험 분석
제5장 시장 규모와 성장 예측
- 제품 유형별
- 최종사용자별
- 기술별
- 휴대성별
- 용도별
- 지역별
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 스페인
- 기타 유럽 국가
- 아시아태평양
- 중국
- 일본
- 인도
- 한국
- 호주
- 기타 아시아태평양 국가
- 중동 및 아프리카
- GCC
- 남아프리카공화국
- 기타 중동 및 아프리카 국가
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 북미
제6장 경쟁 구도
- 시장 집중도
- 시장 점유율 분석
- 기업 개요
- EMS Electro Medical Systems S.A.
- Acteon Group
- Dentsply Sirona Inc.
- mectron S.p.A.
- NSK Nakanishi Inc.
- W&H Dentalwerk Burmoos GmbH
- Ultradent Products, Inc.
- COLTENE Group
- BonART Co., Ltd.
- Woodpecker Medical Instrument Co., Ltd.
- Brasseler U.S.A. Dental, LLC
- Flight Dental Systems
- Kerr Corporation
- Den-Mat Holdings, LLC
- APOZA Enterprise Co., Ltd.
- Being Foshan Medical Equipment Co., Ltd.
- Osada Electric Co., Ltd.
- Coxo Medical Instrument Co., Ltd.
- Techdent SAS
- Aseptico, Inc.
- TPC Advanced Technology, Inc.
제7장 시장 기회와 향후 전망
KSM 26.10.29According to Mordor Intelligence, the dental piezoelectric ultrasonic unit market size is expected to grow from USD 1.08 billion in 2025 to USD 1.13 billion in 2026 and is forecast to reach USD 1.41 billion by 2031 at 4.60% CAGR over 2026-2031.
Global Dental Piezoelectric Ultrasonic Unit Market Trends and Insights
Rising Periodontal Disease Treatment Volumes
Severe periodontitis affected 1.07 billion people globally in 2021, keeping periodontal debridement central to the dental piezoelectric ultrasonic unit market. The World Health Organization set reporting milestones under the Global Oral Health Action Plan 2023 to 2030. These milestones encourage ministries to strengthen preventive oral health services. Public clinics and teaching hospitals can therefore become more important equipment buyers in countries with high disease burden. Their larger purchases tend to favor mid-range benchtop units over premium integrated systems. South Asia had 310 million cases of severe periodontitis in 2021, making India and China important volume markets for public and private dental equipment investment. Projections through 2040 indicate that the disease burden will continue to rise, supporting demand that is not tied only to replacement cycles
Expansion of Implantology and Bone-Management Procedures
Implantology broadens the dental piezoelectric ultrasonic unit market beyond routine prophylaxis. Piezoelectric cutting is used in surgical preparation because it can work on mineralized tissue while limiting contact with adjacent soft tissue and neurovascular structures. This supports use in sinus lifts, ridge augmentation, and peri-implant procedures. Neocis launched the FDA-cleared Yomi S system for minimally invasive implant surgery in November 2025. Greater precision at implant placement can raise expectations for precision during the surgical preparation that precedes it. Oral Surgery & Implantology is forecast to grow at 6.1% CAGR through 2031, above the overall 4.6% rate. Asia Pacific brings together an aging population, higher disposable income, and an expanding private clinic base, which supports implant procedure demand.
High Upfront Capital Cost in Small Practices
Capital cost remains a major barrier for independent and rural practices in the dental piezoelectric ultrasonic unit market. Financing and leasing options are limited in several emerging markets. Premium multi-function systems can exceed the purchase capacity of small practices operating with narrow margins. Many active dental practice sites remain independent, even as DSOs expand their footprint. Cost pressure often shifts demand toward lower-priced Chinese scalers rather than removing it completely. This protects entry-level demand but limits the share available to premium suppliers in high-growth geographies. Trade-in programs and consumable-linked acquisition plans can create a more accessible recurring relationship for price-sensitive buyers.
Other drivers and restraints analyzed in the detailed report include:
- Demand for Minimally Invasive and Patient-Comfort-Oriented Care
- Replacement of Aging Scaler and Handpiece Fleets
- Shortage of Trained Piezoelectric Technique Users
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Piezoelectric Ultrasonic Scalers held 48.6% of the dental piezoelectric ultrasonic unit market share in 2025. They remain the main capital purchase for clinics and group practices building periodontal treatment capacity. Handpieces & Tips is forecast to grow at a 5.8% CAGR through 2031. This rate exceeds the overall market forecast and the rate expected for capital equipment. Each additional installed control unit creates future demand for replacement handpieces and tips. Consumable purchases can therefore continue even when clinics defer a complete unit replacement. Leading suppliers use broad proprietary tip libraries to reinforce this replacement cycle.
The dental piezoelectric ultrasonic unit market is also changing at the boundary between products and treatment platforms. Ultrasonic functions are increasingly combined with air polishing and laser modules. Procurement teams can then evaluate a prophylaxis system rather than a standalone scaler. This may move some capital purchases into broader platform categories. Handpieces & Tips remain important because each clinical mode requires its own application-specific tip. Subgingival, supragingival, endodontic, and surgical work can require different tip designs. Accessories & Maintenance Tools remain the smallest product group. Proprietary compatibility requirements also narrow the opening for generic accessory suppliers.
Dental Clinics accounted for 52.4% of the dental piezoelectric ultrasonic unit market share in 2025. They remain the principal setting for periodontal treatment delivery. Group Dental Practices is forecast to expand at a 5.6% CAGR through 2031. This reflects the transfer of buying authority from individual dentists to multi-location dental organizations. DSOs use centralized formularies to standardize brands and models across their locations. This can shorten replacement cycles when a network changes its equipment standard. It also gives established suppliers an advantage when they offer enterprise service support.
Hospitals, ambulatory surgical centers, and academic institutes are smaller end-user groups. They remain strategically important because they support complex procedures, research, and clinician training. Academic institutions can generate evidence that shapes purchasing decisions in clinics and DSOs. Comparative studies of ultrasonic devices continue to inform clinical protocol choices. Manufacturers may compete for research placements and academic partnerships, even when the immediate sale is smaller. These relationships can influence future treatment practice and formulary selection. The dental piezoelectric ultrasonic unit industry therefore depends on both routine clinical demand and academic evidence development. Group practice growth does not remove the role of independent clinics, but it changes where major purchasing decisions are made.
Complete Report Scope:
- By Product Type
- Piezoelectric Ultrasonic Scalers
- Handpieces & Tips
- Accessories & Maintenance Tools
- By End User
- Dental Clinics
- Hospitals & Ambulatory Surgical Centers
- Group Dental Practices
- Academic & Research Institutes
- By Technology
- Piezoelectric Ceramic Technology
- Digital Control Technology
- Integrated Laser-Piezo Systems
- By Portability
- Benchtop Units
- Portable & Handheld Units
- By Application
- Periodontal Treatment
- Endodontic Treatment
- Oral Surgery & Implantology
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 40.8% of the dental piezoelectric ultrasonic unit market share in 2025. The United States leads regional demand because of its dense private practice network, trained clinical workforce, and DSO consolidation. Purchasing is moving from individual practices toward group-level formulary management. Heartland Dental's December 2025 selection of Dentira for enterprise lab management built on its clinical supplies procurement relationship. Canada has a mature periodontal care base. Mexico is a smaller but developing market where private clinic expansion is outpacing rural public facility investment. Regional growth through 2031 is expected to come mainly from fleet replacement rather than first-time adoption.
Europe is the second-largest regional market for dental piezoelectric ultrasonic units. Germany, the United Kingdom, France, Italy, and Spain account for much of the regional demand. Germany benefits from a high density of private practices and established reimbursement frameworks. The region also includes major suppliers such as W&H in Austria and Mectron in Italy. Their location supports equipment distribution and service availability. Regulatory requirements can favor brands with established conformity documentation. ISO 18397:2025 adds updated requirements for powered scalers and their tips. Eastern European markets are growing as clinic infrastructure investment increases. The regional pattern combines mature demand in Western Europe with developing demand in newer clinic networks. Service coverage matters because practices depend on timely handpiece and tip support. Established local distributors can therefore influence brand selection. Regulatory compliance and distribution capability work together in regional competition.
Asia Pacific is forecast to grow at a 5.3% CAGR through 2031, the highest regional rate in the dental piezoelectric ultrasonic unit market. China offers the largest volume opportunity as private clinics purchase both imported and domestic equipment. The country plans 80,000 new dental chairs by 2030. India is also expanding through greater periodontal awareness, a growing middle class, and public oral health investment. Japan supports maintenance-scaling demand because its population is older and periodontal disease is prevalent among older adults. South Korea and Australia support premium demand through implantology adoption and clinician investment in high-precision equipment. Middle East and Africa and South America remain smaller, underserved regions, with Brazil and Mexico serving as important country-level growth engines. Equipment affordability is especially important in these regions. Suppliers must often balance price, local service, and consumable access. Entry-level products can expand the installed base where premium platforms are harder to finance. As clinic infrastructure improves, these markets can also create demand for broader treatment systems.
- EMS Electro Medical Systems S.A.
- Acteon Group
- Dentsply Sirona
- mectron S.p.A.
- NSK Nakanishi Inc.
- W&H Dentalwerk Burmoos GmbH
- Ultradent Products, Inc.
- COLTENE Group
- BonART Co., Ltd.
- Woodpecker Medical Instrument Co., Ltd.
- Brasseler U.S.A. Dental, LLC
- Flight Dental Systems
- Kerr
- Den-Mat Holdings, LLC
- APOZA Enterprise Co., Ltd.
- Being Foshan Medical Equipment Co., Ltd.
- Osada Electric Co., Ltd.
- Coxo Medical Instrument Co., Ltd.
- Techdent SAS
- Aseptico, Inc.
- TPC Advanced Technology, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.1.1 Market Definition and Inclusion Criteria
- 4.1.2 Market Evolution from Ultrasonic Scaling to Multi-Application Piezo Systems
- 4.1.3 Market Size Snapshot and 2026 Outlook
- 4.2 Market Drivers
- 4.2.1 Rising Periodontal Disease Treatment Volumes
- 4.2.2 Expansion of Implantology and Bone-Management Procedures
- 4.2.3 Demand for Minimally Invasive and Patient-Comfort-Oriented Care
- 4.2.4 Replacement of Aging Scaler and Handpiece Fleets
- 4.2.5 Integration of Smart Frequency and Irrigation Control
- 4.2.6 Procurement Shift Toward Autoclavable, Workflow-Ready Platforms
- 4.3 Market Restraints
- 4.3.1 High Upfront Capital Cost in Small Practices
- 4.3.2 Shortage of Trained Piezoelectric Technique Users
- 4.3.3 Tip Wear, Compatibility and Reprocessing Complexity
- 4.3.4 Regulatory and Clinical-Evidence Burden for New Entrants
- 4.4 Value and Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porters Five Forces Analysis
- 4.7.1 Competitive Rivalry
- 4.7.2 Supplier Bargaining Power
- 4.7.3 Buyer Bargaining Power
- 4.7.4 Threat of New Entrants
- 4.7.5 Threat of Substitutes
- 4.8 Pricing Analysis
- 4.9 Market Risk Analysis
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Product Type
- 5.1.1 Piezoelectric Ultrasonic Scalers
- 5.1.2 Handpieces & Tips
- 5.1.3 Accessories & Maintenance Tools
- 5.2 By End User
- 5.2.1 Dental Clinics
- 5.2.2 Hospitals & Ambulatory Surgical Centers
- 5.2.3 Group Dental Practices
- 5.2.4 Academic & Research Institutes
- 5.3 By Technology
- 5.3.1 Piezoelectric Ceramic Technology
- 5.3.2 Digital Control Technology
- 5.3.3 Integrated Laser-Piezo Systems
- 5.4 By Portability
- 5.4.1 Benchtop Units
- 5.4.2 Portable & Handheld Units
- 5.5 By Application
- 5.5.1 Periodontal Treatment
- 5.5.2 Endodontic Treatment
- 5.5.3 Oral Surgery & Implantology
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East and africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East and Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 EMS Electro Medical Systems S.A.
- 6.3.2 Acteon Group
- 6.3.3 Dentsply Sirona Inc.
- 6.3.4 mectron S.p.A.
- 6.3.5 NSK Nakanishi Inc.
- 6.3.6 W&H Dentalwerk Burmoos GmbH
- 6.3.7 Ultradent Products, Inc.
- 6.3.8 COLTENE Group
- 6.3.9 BonART Co., Ltd.
- 6.3.10 Woodpecker Medical Instrument Co., Ltd.
- 6.3.11 Brasseler U.S.A. Dental, LLC
- 6.3.12 Flight Dental Systems
- 6.3.13 Kerr Corporation
- 6.3.14 Den-Mat Holdings, LLC
- 6.3.15 APOZA Enterprise Co., Ltd.
- 6.3.16 Being Foshan Medical Equipment Co., Ltd.
- 6.3.17 Osada Electric Co., Ltd.
- 6.3.18 Coxo Medical Instrument Co., Ltd.
- 6.3.19 Techdent SAS
- 6.3.20 Aseptico, Inc.
- 6.3.21 TPC Advanced Technology, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment
- 7.2 Future Outlook


