

|
시장보고서
상품코드
2154848
남미의 자가혈당측정 시장 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)South America Self-Blood Glucose Monitoring - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
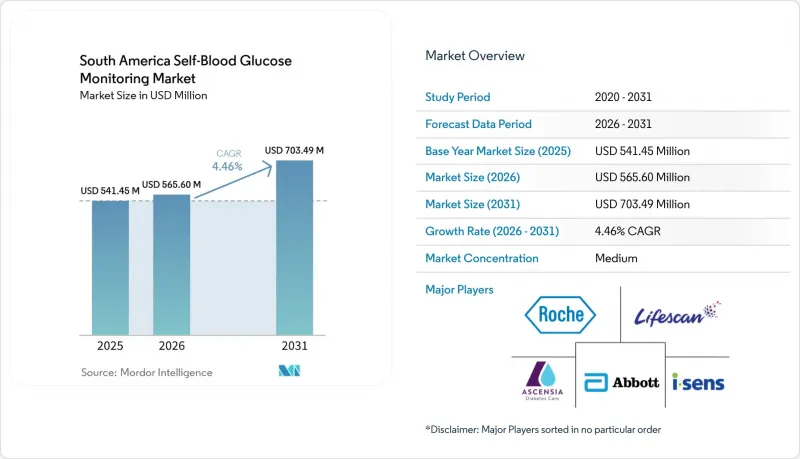
에 따르면 남미의 자가혈당측정 시장 규모는 2025년 5억 4,145만 달러에서 2026년에는 5억 6,560만 달러로 확대하며, 2031년까지 7억 349만 달러에 달할 것으로 예상되고 있으며, 2026-2031년에 CAGR 4.46%로 성장할 것으로 전망되고 있습니다.
남미 자가혈당측정 시장의 동향 및 인사이트
당뇨병 유병률 상승과 미진단 환자 수
남미 자가혈당측정 시장은 진단을 받지 못한 채 당뇨병을 앓으며 생활하는 수많은 성인이 존재함으로써 지탱되고 있습니다. 국제당뇨병연맹(IDF)의 기록에 따르면 2024년 기준 남미 및 중남미에는 3,540만 명의 성인 당뇨병 환자가 있었습니다. 또한 1,070만 명의 성인이 미진단 상태이며, 이는 성인 당뇨병 환자의 30.4%에 해당한다고 보고되고 있습니다. 이 사람들은 선별 검사를 통해 병세가 확인될 경우, 보급형 혈당 측정기나 소모품이 필요할 수 있습니다. 2024년 기준, 브라질의 당뇨병 환자 수는 1,700만 명에 달하여 해당 지역에서 환자 수요의 가장 큰 원천이 되었습니다. 선별 검사를 통해 그동안 혈당 수치를 측정하지 않았던 사람들이 정기적인 검사가 필요한 사람들로 전환되지만, 본인 부담 비용이 검사 빈도를 제한할 가능성이 있습니다.
SMBG 소모품의 공공 제공 및 환급
공적 환급 제도를 통해 남미의 자가혈당측정 시장에는 예측 가능한 공적 판매 채널이 확립되어 있습니다. 브라질의 공적 의료제도에서는 2007년 이후, 제2.583호 정령에 따라 인슐린 의존 환자에게 혈당 측정기와 테스트 스트립을 무상으로 제공하고 있습니다. 이러한 입찰의 제품 사양은 어떤 공급업체가 공공 계약을 경쟁할 수 있는지에 영향을 미칩니다. 아르헨티나의 ‘오브라스 소시알(Obras Sociales)’과 PAMI도 자가 측정 용품에 대한 접근을 지원하고 있지만, 통화 약세로 인해 조달 비용이 상승하고 있습니다. 브라질의 국가 의료 기술 평가 절차는 2025년 1월 권고안에서 플래시 CGM을 공공 의료제도에 포함시키지 않았기 때문에 대상 환자들에게는 기존의 모니터링 용품이 여전히 중요합니다. 입찰에 참여함으로써 공급업체는 소매 판매만으로는 얻을 수 없는 수년에 걸친 판매량에 대한 가시성을 확보할 수 있습니다.
인슐린 사용자의 CGM 도입 촉진: 손가락 채혈 빈도 감소
CGM 도입을 통해 남미의 자가혈당측정 시장에서 인슐린 의존 환자들 사이에서 빈번하게 이루어지는 손가락 채혈 검사의 수요를 줄일 수 있습니다. 이 환자들은 검사 빈도가 높기 때문에 대부분의 경우 가장 많은 검사 스트립을 소비하고 있습니다. 칠레에서는 2025년 12월, 제1형 당뇨병을 앓는 18세 미만 환자 및 임산부를 대상으로 CGM의 보험 적용 범위를 확대했습니다. 브라질에서는 ‘Consulta Publica 63/2026’을 통해 제1형 당뇨병에 대한 실시간 CGM의 보험 적용에 대한 검토가 진행되고 있습니다. 브라질의 실세계 연구에 따르면 플래시 CGM 이용자의 87.6%가 제1형 당뇨병 환자인 것으로 밝혀졌습니다. 2025년 1월 브라질의 플래시 CGM 관련 결정은 공적 의료제도 내에서의 전환이 여전히 단계적으로 진행되고 있음을 보여줍니다.
부문 분석
2025년, 남미 자가혈당측정 시장에서 테스트 스트립은 82.31%의 점유율을 차지했으며, 2031년까지의 연평균 성장률(CAGR)은 5.58%를 기록했습니다. 이러한 선도적인 위상은 측정기를 도입한 후에도 스트립이 반복적으로 사용된다는 점을 반영합니다. 측정할 때마다 호환되는 소모품이 필요하므로 지속적인 구매 주기가 형성됩니다. 혈당 측정기의 경우, 접근성을 높이기 위해 보조금 지원 대상에 포함시키거나 환급 프로그램에 편입하는 것이 가능합니다. 이러한 접근 방식을 통해 공급업체 고유의 테스트 스트립 규격 도입 대수를 늘릴 수 있습니다. 테스트 스트립은 반복적으로 사용되므로, 안정적인 공급은 약국, 공공 구매자, 그리고 환자에게 최우선 과제입니다.
란셋은 일반적으로 판매 시점에 다른 제품과 세트로 판매됩니다. 란셋을 단독으로 구매하기로 결정할 가능성은 낮습니다. 하지만 그 품질은 검사 빈도에 영향을 미칠 수 있으며, 특히 소아 사용자의 경우 통증이 적을수록 사용이 촉진됩니다. IDF 기록에 따르면 2024년 남미 및 중남미에서 임신 중 고혈당의 영향을 받은 출생 건수는 96만 7,187건이었습니다. 이러한 임신 기간 중는 집중적인 모니터링이 필요한 명확한 시기가 발생합니다. 이러한 수요가 임신성 당뇨병을 관리하는 환자들 사이에서 테스트 스트립 사용을 지원하고 있습니다.
2025년, 제2형 당뇨병은 매출 점유율의 89.24%를 차지했습니다. 이 높은 점유율은 해당 지역의 모든 소득 계층에 걸쳐 제2형 당뇨병이 널리 퍼져 있는 현실과 일치합니다. 대부분의 제2형 당뇨병 환자는 지속적인 모니터링보다는 정기적인 혈당 수치를 확인해야 합니다. 이러한 치료 패턴은 소매 약국 및 병원 조달을 통한 판매를 지원하고 있습니다. 환자 기반이 넓기 때문에 공급업체는 안정적인 판매량 기반을 확보하고 있습니다. 또한 정기적인 검사에서는 합리적인 가격과 재구매의 용이성이 중요한 요소가 됩니다.
임신성 당뇨병 시장은 2031년까지 연평균 성장률(CAGR) 7.22%로 확대될 것으로 예측됩니다. 2024년 부에노스아이레스의 한 병원에서 실시된 조사에 따르면 임신 사례의 9%에서 임신성 당뇨병이 확인되었습니다. 한 주립 산부인과 센터에서는 감도가 더 높은 진단 프로토콜을 도입한 후, 발생률이 2021년 16.8%에서 2023년에는 37.1%로 상승했다고 보고되었습니다. 브라질과 콜롬비아에서 선별 검사가 확대됨에 따라 임신 중에 더 많은 환자가 확인될 것으로 예상됩니다. 이러한 환자들에게는 제한된 치료 기간 중 집중적인 모니터링이 필요합니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 공급망 분석
- 규제 상황
- 기술 전망
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 컴포넌트별
- 당뇨병 유형별
- 유통 채널별
- 최종사용자별
- 국가별
- 브라질
- 아르헨티나
- 콜롬비아
- 칠레
- 페루
- 기타 남미 국가
제6장 경쟁 구도
- 시장 집중도
- 시장 점유율 분석
- 기업 개요
- Abbott Laboratories
- ACON Laboratories, Inc.
- AgaMatrix, Inc.
- ARKRAY, Inc.
- Ascensia Diabetes Care Holdings AG
- Beurer GmbH
- Bionime Corporation
- Embecta Corp.
- F. Hoffmann-La Roche AG
- i-SENS, Inc.
- LifeScan IP Holdings, LLC
- Nipro Corporation
- Nova Biomedical
- Rossmax International Ltd.
- Sinocare Inc.
- Terumo Corporation
- Trividia Health, Inc.
제7장 시장 기회와 향후 전망
KSA 26.10.28According to Mordor Intelligence, the South America Self-Blood glucose monitoring market size is expected to increase from USD 541.45 million in 2025 to USD 565.60 million in 2026 and reach USD 703.49 million by 2031, growing at a CAGR of 4.46% over 2026-2031.
South America Self-Blood Glucose Monitoring Market Trends and Insights
Rising Diabetes Prevalence and Undiagnosed Burden
The South America self-blood glucose monitoring market is supported by the large number of adults who live with diabetes without a diagnosis. The IDF recorded 35.4 million adults with diabetes in South and Central America in 2024. It also reported that 10.7 million adults were undiagnosed, representing 30.4% of adults with diabetes. These individuals may require entry-level meters and supplies when screening identifies their condition. Brazil had 17 million people with diabetes in 2024, which made it the region's largest source of patient demand. Screening activity converts a previously unmonitored population into people who need regular testing, although out-of-pocket costs can limit testing frequency.
Public Provision and Reimbursement of SMBG Supplies
Public reimbursement gives the South America self-blood glucose monitoring market a predictable institutional sales channel. Brazil's public health system has provided glucometers and test strips without charge to insulin-dependent patients under Portaria n0 2.583 since 2007. Product specifications in these tenders influence which suppliers can compete for public contracts. Argentine obras sociales and PAMI also support access to self-monitoring supplies, although currency depreciation raises procurement costs. Brazil's national health technology assessment process did not add flash CGM to the public system in its January 2025 recommendation, leaving conventional monitoring supplies relevant for covered patients. Tender access can give suppliers multiyear volume visibility that is not available through retail sales alone.
Accelerating CGM Adoption Among Insulin Users: Reducing Fingerstick Frequency
CGM adoption can reduce demand for frequent fingerstick testing among insulin-dependent patients in the South America self-blood glucose monitoring market. These patients often consume the highest volumes of test strips because they test more often. Chile expanded CGM coverage in December 2025 for people under 18 and pregnant women with Type 1 diabetes. Brazil is evaluating real-time CGM coverage for Type 1 diabetes through Consulta Publica 63/2026. The Brazilian real-world study found that 87.6% of flash CGM users had Type 1 diabetes. Brazil's January 2025 decision on flash CGM indicates that the transition in the public system remains gradual.
Other drivers and restraints analyzed in the detailed report include:
- Shift to Home-Based Diabetes Self-Management and Digital Enablement
- Expansion of Retail and E-Pharmacy Fulfillment
- Import Dependence, Foreign-Exchange Volatility, and Price Caps
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Test strips held 82.31% of the South America self-blood glucose monitoring market share in 2025 and recorded a 5.58% CAGR through 2031. Their leading position reflects the repeated use of strips after a meter is placed. Each test requires a compatible consumable, which creates a continuing purchase cycle. Meters can be subsidized or included in reimbursement programs to encourage access. That approach can increase the installed base for a supplier's proprietary strip format. The recurring nature of strips makes a stable supply a priority for pharmacies, public buyers, and patients.
Lancets are usually bundled with other products at the point of sale. They are less likely to make a purchase decision on their own. Their quality can still affect testing regularity, especially for pediatric users, where lower pain can support use. The IDF recorded 967,187 live births affected by hyperglycemia in pregnancy in South and Central America during 2024. These pregnancies create a defined period when intensive monitoring may be needed. This demand supports the use of strips among patients managing gestational diabetes.
Type 2 diabetes held 89.24% revenue share in 2025. Its large share aligns with the broad prevalence of Type 2 diabetes across income groups in the region. Many people with Type 2 diabetes require periodic glucose checks rather than continuous monitoring. This care pattern supports sales through retail pharmacies and hospital procurement. The high patient base gives suppliers a broad volume foundation. It also leaves affordability and refill access central to regular testing.
Gestational diabetes is forecast to grow at a 7.22% CAGR through 2031. A 2024 Buenos Aires hospital study recorded gestational diabetes in 9% of pregnancies. A provincial maternity center reported an incidence rising from 16.8% in 2021 to 37.1% in 2023 after it adopted more sensitive diagnostic protocols. Wider screening in Brazil and Colombia is expected to identify more patients during pregnancy. These patients need intensive monitoring for a limited care period.
Complete Report Scope:
- By Component
- Glucometer Devices
- Test Strips
- Lancets
- By Diabetes Type
- Type 1 Diabetes
- Type 2 Diabetes
- Gestational Diabetes
- By Distribution Channel
- Business-to-Business
- Retail Pharmacies
- Online Pharmacies
- Other Distribution Channels
- By End-User
- Homecare Settings
- Hospitals and Clinics
- Diagnostic Centers
- Other End Users
- By Country
- Brazil
- Argentina
- Colombia
- Chile
- Peru
- Rest of South America
List of Companies Covered in this Report:
- Abbott Laboratories
- Acon Laboratories
- AgaMatrix, Inc.
- Arkray
- Ascensia Diabetes Care Holdings AG
- Beurer
- Bionime
- Embecta Corp.
- Roche
- I-Sens
- LifeScan IP Holdings, LLC
- Nipro
- Nova Biomedical
- Rossmax
- Sinocare
- Terumo
- Trividia Health, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Diabetes Prevalence and Undiagnosed Burden
- 4.2.2 Public Provision and Reimbursement of SMBG Supplies
- 4.2.3 Shift to Home-Based Diabetes Self-Management and Digital Enablement
- 4.2.4 Expansion of Retail and E-Pharmacy Fulfillment
- 4.2.5 Meter-Strip Ecosystem Lock-In Sustaining Recurring Strip Volumes
- 4.2.6 Omnichannel Pharmacy Programs Improving Adherence
- 4.3 Market Restraints
- 4.3.1 Accelerating CGM Adoption Among Insulin Users Reducing Fingerstick Frequency
- 4.3.2 Import Dependence, Foreign-Exchange Volatility, and Price Caps
- 4.3.3 Regulatory Suspensions and Quality Interdictions Disrupting Public Tenders
- 4.3.4 Counterfeit and Substandard Strips on Informal Channels Eroding Trust
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Component
- 5.1.1 Glucometer Devices
- 5.1.2 Test Strips
- 5.1.3 Lancets
- 5.2 By Diabetes Type
- 5.2.1 Type 1 Diabetes
- 5.2.2 Type 2 Diabetes
- 5.2.3 Gestational Diabetes
- 5.3 By Distribution Channel
- 5.3.1 Business-to-Business
- 5.3.2 Retail Pharmacies
- 5.3.3 Online Pharmacies
- 5.3.4 Other Distribution Channels
- 5.4 By End-User
- 5.4.1 Homecare Settings
- 5.4.2 Hospitals and Clinics
- 5.4.3 Diagnostic Centers
- 5.4.4 Other End Users
- 5.5 By Country
- 5.5.1 Brazil
- 5.5.2 Argentina
- 5.5.3 Colombia
- 5.5.4 Chile
- 5.5.5 Peru
- 5.5.6 Rest of South America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 Abbott Laboratories
- 6.3.2 ACON Laboratories, Inc.
- 6.3.3 AgaMatrix, Inc.
- 6.3.4 ARKRAY, Inc.
- 6.3.5 Ascensia Diabetes Care Holdings AG
- 6.3.6 Beurer GmbH
- 6.3.7 Bionime Corporation
- 6.3.8 Embecta Corp.
- 6.3.9 F. Hoffmann-La Roche AG
- 6.3.10 i-SENS, Inc.
- 6.3.11 LifeScan IP Holdings, LLC
- 6.3.12 Nipro Corporation
- 6.3.13 Nova Biomedical
- 6.3.14 Rossmax International Ltd.
- 6.3.15 Sinocare Inc.
- 6.3.16 Terumo Corporation
- 6.3.17 Trividia Health, Inc.
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


