

|
시장보고서
상품코드
2154854
산업용 촉매 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Industrial Catalysts - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
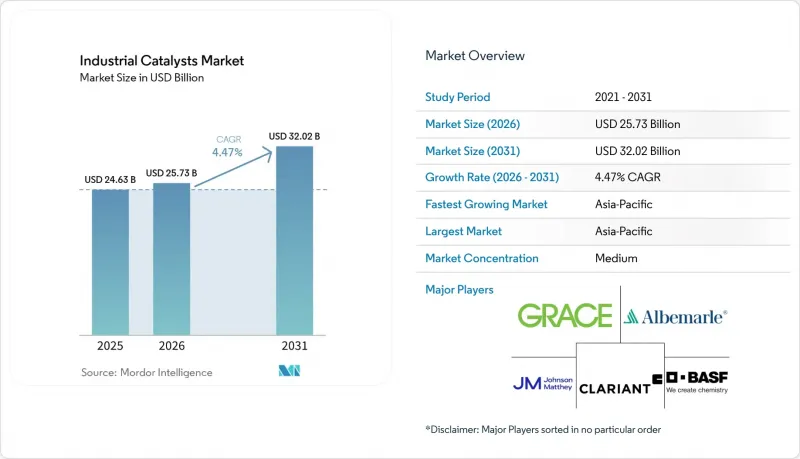
에 따르면 산업용 촉매 시장 규모는 2025년에 246억 3,000만 달러로 평가되며, 2026년 257억 3,000만 달러에서 2031년까지 320억 2,000만 달러에 달할 것으로 예측되고 있으며, 예측 기간(2026-2031년)에 CAGR은 4.47%에 달할 전망입니다.
세계 산업용 촉매 시장의 동향 및 인사이트
정유소 및 석유화학 플랜트의 생산 능력 확대
신규 그린필드 플랜트는 각 공정 유닛이 가동 시작시 새로운 촉매를 충전해야 하므로 산업용 촉매 시장을 지원하고 있습니다. 또한 이러한 플랜트는 플랜트 가동 기간 중 이루어지는 재생 및 교체 주기를 통해 지속적인 수요를 창출합니다. 중국, 인도 및 걸프 지역 국가들의 프로젝트에서는 유동 접촉 분해, 수소화 처리, 수소화 분해 및 프로필렌 생산을 위한 촉매 시스템이 필요합니다. 하네웰 인터내셔널은 2026년 4월, 단고테의 레키 콤플렉스를 대상으로 연간 75만 메트릭톤의 프로필렌 생산 능력을 커버하는 촉매 및 기술 계약을 체결했습니다. 프로필렌 수율을 극대화하도록 설계된 석유화학 통합 정유소는 기존의 가솔린 생산을 주요 목적으로 하는 운영에 비해 원료 단위당 촉매 사용량이 더 많습니다. 이 때문에 현재의 프로젝트 파이프라인은 산업용 촉매 시장에서 지속적인 수요의 중요한 원천이 되고 있습니다.
연료 및 산업 배출 기준의 강화
배출 규제의 강화로 인해 산업용 설비 및 연료 처리 시스템에 필요한 촉매 충전량이 증가하고 있습니다. 미국 환경보호청(EPA)은 2026년 1월 9일, 고정식 연소 터빈에 관한 ‘신규 배출원 성능 기준(NSPS)’ 개정을 최종 확정하고, 특정 터빈 하위 범주에서 질소산화물(NOx) 통제를 위해 선택적 촉매 환원(SCR) 도입을 의무화했습니다. 국제해사기구(IMO)는 2026년 5월 1일, 북대서양 북동부를 질소산화물, 황산화물 및 미세먼지 배출 규제 구역으로 지정했습니다. 이러한 요건으로 인해 선택적 촉매 환원(SCR) 및 관련 배기가스 처리 기술에 대한 수요가 확대되고 있습니다. 사업자는 도입 비용이 급등하는 상황에서도 성능 기준을 충족해야 합니다. 이러한 규정 준수 요건은 재량적인 자본 프로젝트만큼 쉽게 지출을 미룰 수 없기 때문에 산업용 촉매 시장을 지원하는 요인이 되고 있습니다.
귀금속 및 중요 광물의 가격 변동
백금, 팔라듐, 로듐은 많은 고성능 비균질 촉매 조성물에서 필수적인 활성 성분입니다. 이러한 재료의 가격 변동은 제조 비용을 급격히 상승시켜 공급업체의 이익률에 압박을 가할 가능성이 있습니다. 존슨 매시(Johnson Massey)의 보고서에 따르면 2025년 백금 시장은 3년 연속 구조적 공급 부족이 지속된 반면, 화학, 유리, 합성 연료 분야의 산업 소비량은 완만하게 증가했습니다. 금속 가격 상승으로 인해 고객들은 재생 주기를 연장하여 교체용 제품 구매를 미룰 가능성이 있습니다. 이로 인해 선택성이 저하되고, 가동중인 플랜트에서 공정 손실의 위험이 높아질 우려가 있습니다. 이러한 영향으로 인해 구매 결정이 단기적인 투입 비용에 민감해짐에 따라 산업용 촉매 시장은 위축될 것입니다.
부문 분석
2025년, 금속은 수소화 처리, 수증기 메탄 개질 및 촉매 개질에서의 역할에 힘입어 산업용 촉매 시장의 38.23%를 차지했습니다. 니켈, 코발트, 몰리브덴 및 백금족 금속은 연속 산업 공정에서 요구되는 활성과 안정성을 제공합니다. 제올라이트는 전환율과 생성물 분포를 결정짓기 때문에 유동 접촉 분해 및 수소화 분해에서 중요한 역할을 수행하고 있습니다. 제올리스트 인터내셔널의 수소 분해 촉매 포트폴리오는 전 세계 수소 분해 촉매 수요의 30%를 충족하고 있으며, 이 회사의 ‘오팔 리뉴(Opal Renew)’ 제올라이트는 재생 가능 디젤 및 지속가능한 항공 연료 용도로 활용되고 있습니다. 화학 화합물은 산 촉매에 의한 알킬화 및 이성질화를 지원하지만, 이러한 화합물의 교체 시기는 플랜트의 경제성에 크게 좌우됩니다.
유기금속 소재는 2031년까지 연평균 성장률(CAGR) 5.32%로 확대될 것으로 예측됩니다. 이 소재에 대한 수요는 의약품 유효 성분의 합성, 특수 폴리머 및 이산화탄소 활용 경로와 밀접하게 관련되어 있습니다. 2025년 'Journal of the American Chemical Society'에 게재된 라이프니츠 촉매 연구소, 루르 대학교 보훔, 에보닉 인더스트리즈 AG의 연구진이 수행한 연구에 따르면 이산화탄소와 그린 수소를 화학 중간체로 직접 변환하는 이리듐-팔라듐 바이메탈 촉매가 보고되었습니다. 유미코어(Yumicore)사는 오클라호마주 카투사에 그라브스 촉매 생산 시설을 건설 중이며, 2027년 초 생산 개시를 목표로 하고 있습니다. 혼합 금속 산화물 및 바이메탈계 촉매 역시 전기화학 분야와 환경 분야에서의 용도에서 중요한 역할을 수행하고 있습니다.
지역별 분석
아시아태평양은 2025년 산업용 촉매 시장의 35.67%를 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 5.45%로 확대될 것으로 예측됩니다. 중국의 대규모 정제 시스템이 유동 접촉 분해, 수소화 처리, 개질용 촉매의 수요를 지원하고 있습니다. 인도의 정유소 및 석유화학 산업의 확장은 처리용 촉매 수요를 끌어올리고 있습니다. Topsoe는 2025년 아시아태평양에서 견고한 촉매 매출을 기록했다고 보고했으며, 인도가 주요 성장 동력으로 부상하고 있는 한편, 중국에서는 3건의 지속가능한 항공 연료 프로젝트를 수주했습니다. 한국, 일본, 베트남, 인도네시아에서는 석유화학 클러스터, 연료 품질 요건, 그리고 정유소의 자급자족 프로그램을 통해 수요가 확대되고 있습니다.
북미와 유럽은 교체용 촉매, 저유황 연료 처리 및 환경 제어 시스템 분야에서 주요 수요 기반을 형성하고 있습니다. 북미에서는 복잡한 정유소 구성으로 인해 특수한 수소화 분해 및 수소화 처리용 배합에 대한 지속적인 수요가 발생하고 있습니다. 또한 저탄소 수소 및 암모니아에 대한 인센티브로 인해 기존 정유소 운영 이외의 분야에서도 촉매 수요가 발생하고 있습니다. 유럽에서는 바이오 유래 원료의 공동 처리 및 정유소와 석유화학의 통합을 통해 산업의 탄소 집약도 저감에 주력하고 있습니다. 두 지역 모두에서 산업용 촉매 시장은 대규모 신규 정유소 건설보다는 촉매 교체, 규제 준수 및 공정 업그레이드를 통해 형성되고 있습니다.
남미, 중동 및 아프리카는 산업용 촉매 시장에서 규모는 작지만 독자적인 위치를 차지하고 있습니다. 브라질에서는 사탕수수 유래 에탄올 처리 및 수소화 처리된 식물성 오일 생산을 위한 특수한 솔루션이 요구되고 있습니다. 탑소(Topsoe)사는 사우디아라비아의 얌부(Yamb) 그린 수소 프로젝트를 지원하고 있으며, 한편, 하네웰 인터내셔널(Honeywell International)사의 단고트(Dangote) 레키(Lekki) 복합 단지에 대한 계약으로 인해 나이지리아의 석유화학용 촉매 수요가 증가하고 있습니다. 일부 시장의 경제 상황 변동으로 인해 조달 및 촉매 교체 주기가 지연될 가능성이 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 밸류체인 분석
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 소재별
- 유형별
- 용도별
- 지역별
- 아시아태평양
- 중국
- 인도
- 일본
- 한국
- ASEAN 국가
- 기타 아시아태평양 국가
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 북유럽 국가
- 기타 유럽 국가
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 중동 및 아프리카
- 사우디아라비아
- 남아프리카공화국
- 기타 중동 및 아프리카 국가
- 아시아태평양
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율·순위 분석
- 기업 개요
- BASF
- Albemarle Corporation
- Axens
- CLARIANT
- Evonik Industries AG
- Honeywell International Inc.
- JGC C&C
- Johnson Matthey
- NIPPON KETJEN Co.,Ltd.
- Shell plc
- Sinopec Catalyst CO.,LTD.
- Topsoe A/S
- Umicore
- W. R. Grace & Co.-Conn
- Zeolyst International
제7장 시장 기회와 향후 전망
KSA 26.10.28According to Mordor Intelligence, the industrial catalysts market size was valued at USD 24.63 billion in 2025 and is estimated to grow from USD 25.73 billion in 2026 to reach USD 32.02 billion by 2031, at a CAGR of 4.47% during the forecast period (2026-2031).
Global Industrial Catalysts Market Trends and Insights
Refinery and Petrochemical Capacity Expansion
New greenfield units support the industrial catalysts market because each process unit needs a fresh catalyst charge at start-up. Those units also create recurring demand through regeneration and replacement cycles over the life of the plant. Projects in China, India, and the Gulf require catalyst systems for fluid catalytic cracking, hydrotreating, hydrocracking, and propylene production. Honeywell International Inc secured a catalyst and technology contract for Dangote's Lekki complex in April 2026, covering 750,000 metric tons per year of propylene capacity. Petrochemical-integrated refineries designed to maximize propylene yield use more catalyst per unit of feedstock than conventional gasoline-focused operations. This makes the current project pipeline an important source of sustained demand for the industrial catalysts market.
Tightening Fuel and Industrial Emission Standards
Emission rules increase the required catalyst loading in industrial equipment and fuel-processing systems. The U.S. Environmental Protection Agency finalized amendments to New Source Performance Standards for stationary combustion turbines on January 9, 2026, requiring selective catalytic reduction for nitrogen oxide control in specified turbine subcategories. The International Maritime Organization designated the North-East Atlantic as an Emission Control Area for nitrogen oxides, sulfur oxides, and particulate matter on May 1, 2026. These requirements extend demand for selective catalytic reduction and related exhaust-treatment technologies. Operators must meet performance thresholds even when input costs are high. This compliance need supports the industrial catalysts market because spending cannot be deferred as easily as discretionary capital projects.
Precious-Metal and Critical-Mineral Price Volatility
Platinum, palladium, and rhodium are essential active components in many high-performance heterogeneous formulations. Price movements for these materials can quickly raise manufacturing costs and pressure supplier margins. Johnson Matthey reported that the platinum market remained in structural deficit for a third consecutive year in 2025, while industrial consumption in chemicals, glass, and synthetic-fuels applications grew modestly. Higher metal prices can prompt customers to extend regeneration cycles to defer replacement purchases. This may reduce selectivity and raise the risk of process losses at the operating plant. The effect restrains the industrial catalysts market by making purchasing decisions more sensitive to short-term input costs.
Other drivers and restraints analyzed in the detailed report include:
- Process Intensification and Higher Catalyst Selectivity
- Low-Carbon Hydrogen, Ammonia, and Circular Chemistry Investment
- Long Qualification and Plant-Validation Cycles
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Metals held 38.23% of the industrial catalysts market in 2025, supported by their role in hydrotreating, steam methane reforming, and catalytic reforming. Nickel, cobalt, molybdenum, and platinum-group metals provide the activity and stability required in continuous industrial processes. Zeolites are important in fluid catalytic cracking and hydrocracking because they determine conversion and product distribution. Zeolyst International's hydrocracking catalyst portfolio addresses 30% of global hydrocracking catalyst requirements, and its Opal Renew zeolites serve renewable diesel and sustainable aviation fuel applications. Chemical compounds support acid-catalyzed alkylation and isomerization, where replacement timing depends heavily on plant economics.
Organometallic materials are projected to advance at a 5.32% CAGR through 2031. Demand is linked to active pharmaceutical ingredient synthesis, specialty polymers, and carbon dioxide utilization pathways. A 2025 Journal of the American Chemical Society study by researchers from the Leibniz Institute for Catalysis, Ruhr University Bochum, and Evonik Industries AG described a bimetallic iridium-palladium system that directly converts carbon dioxide and green hydrogen into chemical intermediates. Umicore is constructing a Grubbs catalyst production facility at Catoosa, Oklahoma, with production targeted for early 2027. Mixed-metal oxides and bimetallic systems also have a role in electrochemical and environmental uses.
Complete Report Scope:
- By Material
- Metals
- Zeolites
- Chemical Compounds
- Organometallic Materials
- Other Materials
- By Type
- Heterogeneous Catalysts
- Homogeneous Catalysts
- By Application
- Petroleum Refining
- Petrochemicals
- Chemical Synthesis
- Environmental Catalysis
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 35.67% of the industrial catalysts market in 2025 and is projected to advance at a 5.45% CAGR through 2031. China's large refining system supports demand for fluid catalytic cracking, hydrotreating, and reforming catalysts. India's refinery and petrochemical expansion adds demand for processing catalysts. Topsoe reported strong Asia-Pacific catalyst sales in 2025, with India emerging as a key growth driver, and 3 sustainable aviation fuel projects secured in China. South Korea, Japan, Vietnam, and Indonesia add demand through petrochemical clusters, fuel-quality requirements, and refinery self-sufficiency programs.
North America and Europe form a major demand base for replacement catalysts, low-sulfur fuel processing, and environmental control systems. In North America, complex refinery configurations create a continued need for specialized hydrocracking and hydrotreating formulations. Incentives for low-carbon hydrogen and ammonia also create catalyst demand outside conventional refinery operations. Europe is focused on reducing industrial carbon intensity through bio-derived feedstock co-processing and refinery-petrochemical integration. The industrial catalysts market in both regions is shaped more by replacement, compliance, and process upgrades than by large new refinery construction.
South America and Middle East and Africa represent a smaller but distinct part of the industrial catalysts market. Brazil requires specialized solutions for sugarcane ethanol processing and hydrotreated vegetable oil production. Topsoe supports the Yanbu Green Hydrogen Project in Saudi Arabia, while Honeywell International Inc's contract for Dangote's Lekki complex adds petrochemical catalyst demand in Nigeria. Economic volatility in some markets can delay procurement and catalyst replacement cycles.
- BASF
- Albemarle Corporation
- Axens
- CLARIANT
- Evonik Industries AG
- Honeywell International Inc.
- JGC C&C
- Johnson Matthey
- NIPPON KETJEN Co.,Ltd.
- Shell plc
- Sinopec Catalyst CO.,LTD.
- Topsoe A/S
- Umicore
- W. R. Grace & Co.-Conn
- Zeolyst International
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Refinery and Petrochemical Capacity Expansion
- 4.2.2 Tightening Fuel and Industrial Emission Standards
- 4.2.3 Process Intensification and Higher Catalyst Selectivity
- 4.2.4 Low-Carbon Hydrogen, Ammonia, and Circular Chemistry Investment
- 4.2.5 Digital Catalyst Monitoring and Performance-Based Services
- 4.3 Market Restraints
- 4.3.1 Precious-Metal and Critical-Mineral Price Volatility
- 4.3.2 Long Qualification and Plant-Validation Cycles
- 4.3.3 Deactivation Risk from Variable Biofeeds and Co-Processing Streams
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Material
- 5.1.1 Metals
- 5.1.2 Zeolites
- 5.1.3 Chemical Compounds
- 5.1.4 Organometallic Materials
- 5.1.5 Other Materials
- 5.2 By Type
- 5.2.1 Heterogeneous Catalysts
- 5.2.2 Homogeneous Catalysts
- 5.3 By Application
- 5.3.1 Petroleum Refining
- 5.3.2 Petrochemicals
- 5.3.3 Chemical Synthesis
- 5.3.4 Environmental Catalysis
- 5.3.5 Other Applications
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 NORDIC Countries
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 BASF
- 6.4.2 Albemarle Corporation
- 6.4.3 Axens
- 6.4.4 CLARIANT
- 6.4.5 Evonik Industries AG
- 6.4.6 Honeywell International Inc.
- 6.4.7 JGC C&C
- 6.4.8 Johnson Matthey
- 6.4.9 NIPPON KETJEN Co.,Ltd.
- 6.4.10 Shell plc
- 6.4.11 Sinopec Catalyst CO.,LTD.
- 6.4.12 Topsoe A/S
- 6.4.13 Umicore
- 6.4.14 W. R. Grace & Co.-Conn
- 6.4.15 Zeolyst International
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


