

|
시장보고서
상품코드
2154888
남미의 폴리프로필렌(PP) 포장 필름 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)South America Polypropylene (PP) Packaging Film - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
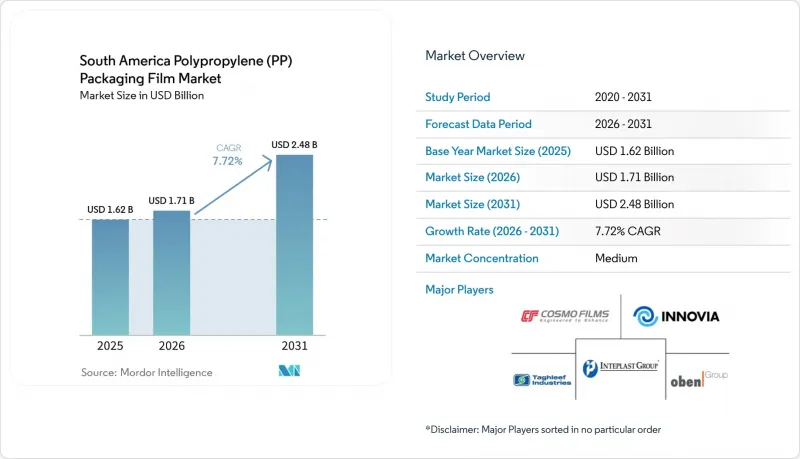
에 따르면 남미의 폴리프로필렌(PP) 포장 필름 시장 규모는 2025년에 16억 2,000만 달러로 평가되며, 2026년 17억 1,000만 달러에서 2031년까지 24억 8,000만 달러에 달할 것으로 예측되고 있으며, 예측 기간(2026-2031년)에 CAGR은 7.72%에 달할 전망입니다.
남미 폴리프로필렌(PP) 포장 필름 시장의 동향 및 인사이트
포장 식품 및 편의 식품 소비 확대
가공식품 및 편의식품은 브라질, 콜롬비아, 아르헨티나, 칠레에 걸친 남미의 폴리프로필렌(PP) 포장 필름 시장에서 계속해서 안정적인 수요원으로 자리 잡고 있습니다. 남미 및 카리브해 지역의 경제 성장률은 2024년 2.2%에 비해 2025년에는 2.5%를 기록하며, 해당 지역 전체의 포장 제품에 대한 가계 지출을 지원하고 있습니다. 브라질의 식품 가공업체들은 투명성, 밀봉 신뢰성 및 방습성이 요구되는 제빵 제품, 과자, 스낵, 유제품, 신선식품에 대해 코팅 및 비코팅 BOPP 필름을 사용하고 있습니다. 조직화된 소매 업계에서는 많은 오픈 마켓 판매와 달리, 창고 보관, 운송 및 매장 진열 과정에서 각 제품이 밀봉되고, 라벨이 부착되며, 보호되어야 합니다. 이러한 변화로 인해 소매 단위당 필름 사용량이 증가하고 있으며, 각 컨버터 업체들은 일관된 인쇄 품질, 차단 성능, 미끄럼성 제어, 그리고 신뢰할 수 있는 기계적 성능을 제공해야 할 것으로 요구받고 있습니다. 안데스 지역 스낵 및 시리얼 제조업체들은 도시 지역 소비자를 대상으로 메탈라이징 가공 및 높은 차단 성능을 갖춘 BOPP 등급을 선정하고 있으며, 이로 인해 기본적인 오버랩 포장에서 1kg당 수익성이 높고 더 엄격한 제품 사양이 요구되는 소재로의 전환이 가속화되고 있습니다.
재활용 가능한 단일 폴리프로필렌 구조로의 전환
모노폴리프로필렌 포장으로의 전환은 남미의 폴리프로필렌(PP) 포장 필름 시장에서 사업적 요건으로 자리 잡고 있습니다. 브라질의 제12,688호/2025년 정부령에 따르면 2026년 1월부터 대기업에 대해 재생재 함유율 22% 및 회수율 32%가 의무화되며, 2040년까지 각각 40% 및 50%로 목표가 상향 조정됩니다. 콜롬비아의 2024년 결의안 제803호 역시 포장재 회수, 원자재 추적 및 재생 원료 사용에 관한 요건을 규정하고 있으며, 이로 인해 기존의 다중 소재 구조에 대한 상업적 비용이 상승하고 있습니다. Vitopel사는 BOBST EXPERT K5 메탈라이저를 도입하여 메탈라이즈 필름의 생산 능력을 40% 향상시키는 동시에 재활용 가능한 단일 PP 구조의 실현을 가능하게 했습니다. 더 얇은 단일 PP 구조라면, 차단 성능을 유지하면서 1팩당 플라스틱 사용량을 줄일 수 있습니다. 이는 가공 공정에서 롤에 대한 수요가 증가하고, 각 브랜드가 재료 사용량 감축을 추구하는 상황에서도 마찬가지입니다. ABRE 및 Abiplast가 추진하는 인증 절차는 가공업체가 자사 포장이 재활용 가능성 요건을 충족함을 입증하고, 고객에게 소재 선택 이유를 문서화하며, 공식적인 규정 준수 프로그램에 대한 접근성을 개선하는 데 도움이 됩니다.
폴리프로필렌 수지 가격 변동
수지 가격 변동은 남미의 폴리프로필렌(PP) 포장 필름 시장에서 변환업체에게 여전히 직접적인 이익률 제약 요인으로 작용하고 있습니다. 2025년 5월, 브라질의 PP 호모폴리머 현물 가격은 톤당 970-1,020달러 범위에서 형성되었으며, 이후 공급 차질로 인해 현지 가격 상승 압력이 강화되었습니다. 많은 가공업체는 수지를 달러로 구매하는 반면, 완제품 필름은 현지 통화로 판매하고 있으므로 수지 가격 상승과 통화 약세라는 두 가지 요인에 동시에 노출되어 있습니다. 브라질은 2025년에 332만 메트릭톤의 플라스틱 수지를 수입했으며, 이는 가공업체들이 원자재 수요를 줄이기보다는 수입처를 계속 전환하고 있음을 시사합니다. 브라질의 PRESIQ 프로그램은 2027년부터 5년 동안 화학 산업에 연간 30억 레알(5억 8,000만 달러)의 장려금을 지급할 예정이지만, 단기적인 현물 시장의 위험을 해소해 주지는 못합니다. 이익률 유지를 목표로 하는 가공업체에게 있으며, 장기 수지 계약, 유연한 조달, 신중한 가격 전가, 그리고 효율적인 재고 계획은 여전히 중요한 요소로 남아 있습니다.
부문별 분석
2025년, BOPP 필름은 남미의 폴리프로필렌(PP) 포장 필름 시장에서 72.34%의 점유율을 차지했습니다. 이러한 위상은 그라비어 인쇄 및 플렉소 인쇄와의 폭넓은 호환성, 높은 가공 속도, 그리고 스낵, 커피, 유제품, 과자류 포장에 걸친 광범위한 용도에 힘입은 것입니다. 투명 등급은 제품이 잘 보이고 자동 라인에서의 처리 효율이 높기 때문에 상온 보관이 가능한 제빵 제품이나 스낵의 포장에 널리 사용되고 있습니다. 메탈라이즈드 BOPP는 Vitopel사가 2024년에 메탈라이저에 투자하여 생산 능력을 40% 확대하고, 프로세스 치즈, 분유, 지방종자 포장을 타깃으로 삼은 데 힘입어 지지를 얻었습니다. PVDC, 아크릴 또는 EVOH 층을 갖춘 코팅 등급은 더 강력한 산소 및 수분 차단 기능이 필요한 수출용 식품 포장에 사용되고 있습니다. 한편, 코팅되지 않은 BOPP는 라벨용 소재, 1차 포장 및 가성비를 중시하는 제과 용도에서 여전히 널리 사용되고 있습니다.
일반적으로 CPP라고 불리는 캐스트 폴리프로필렌은 2031년까지 연평균 성장률(CAGR) 8.16%로 성장할 것으로 예상되며, 이는 필름 유형 중 가장 높은 성장률입니다. 의약품용 뚜껑 및 블리스터 포장 용도에서는 열 안정성과 제어된 밀봉·박리 성능이 높이 평가되는 반면, 범용 등급은 다층 파우치 및 라미네이트 기재를 지원하고 있습니다. 레토르트 등급 CPP는 고온 살균 사이클 중에도 필름의 무결성을 유지해야 하는 즉석식사나 가공 식품에 사용됩니다. 메탈라이즈드 CPP는 단일 소재의 재활용성이 중요시되는 경우, 호일 기반 구조를 대체하는 것으로서 고급 커피나 스낵 포장재에서 사용이 확대되고 있습니다. 그 밖의 연신 및 캐스트 PP 변형 제품들은 남미의 폴리프로필렌(PP) 포장 필름 산업에서 특정 차단성, 밀봉성, 가공 요건을 충족하는 소규모 기술 틈새 시장을 차지하고 있습니다.
기타 장점:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 거시경제 요인이 시장에 미치는 영향
- 업계 밸류체인 분석
- 규제 상황
- 기술 전망
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 필름 유형별
- 포장 형태별
- 최종 용도 산업별
- 지역별
- 브라질
- 아르헨티나
- 칠레
- 콜롬비아
- 기타 남미 국가
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- Oben Holding Group S.A.C.
- Taghleef Industries, Inc.
- Innovia Films Limited
- Cosmo Films Limited
- Inteplast Group, Ltd.
- Toray Industries, Inc.
- UFlex Limited
- Manucor S.p.A.
- Poligal S.A.
- Vacmet India Limited
- Toppan Speciality Films Private Limited
- Altopro S.A. de C.V.
- Grupo Plastilene S.A.S.
- Vitopel do Brasil Ltda.
- Innova S.A.
- Valfilm S.A.
- Prolam S.A.
- Sigmaplast S.A.
제7장 시장 기회와 향후 전망
KSA 26.10.28According to Mordor Intelligence, the South America polypropylene (PP) packaging film market size was valued at USD 1.62 billion in 2025 and estimated to grow from USD 1.71 billion in 2026 to reach USD 2.48 billion by 2031, at a CAGR of 7.72% during the forecast period (2026-2031).
South America Polypropylene (PP) Packaging Film Market Trends and Insights
Packaged Food and Convenience Consumption Expansion
Processed and convenience food remains a stable source of demand for the South America polypropylene (PP) packaging film market across Brazil, Colombia, Argentina, and Chile. South America and the Caribbean economies grew 2.5% in 2025, compared with 2.2% in 2024, supporting household spending on packaged products across the region. Brazil's food processors use coated and uncoated BOPP film for bakery, confectionery, snacks, dairy, and fresh-produce products that require clarity, seal reliability, and moisture protection. Organized retail requires each product to be sealed, labeled, and protected during warehousing, transport, and shelf display, unlike many open-market sales. This change increases film use per retail unit and encourages converters to offer consistent printing, barrier performance, controlled slip, and dependable machine performance. Snack and cereal producers in Andean countries are selecting metalized and high-barrier BOPP grades for urban consumers, supporting a shift from basic overwrap toward materials with higher revenue per kilogram and more demanding product specifications.
Shift Toward Recyclable Mono-Polypropylene Structures
The move to mono-polypropylene packaging is becoming an operating requirement for the South America polypropylene (PP) packaging film market. Brazil's Decree No. 12,688/2025 established a 22% recycled-content requirement and a 32% recovery rate for large companies from January 2026, with targets increasing to 40% and 50% by 2040. Colombia's Resolution 803 of 2024 also set requirements for packaging collection, material tracking, and the use of recycled raw materials, raising the commercial cost of conventional multi-material structures. Vitopel installed a BOBST EXPERT K5 metallizer, which increased its metalized film capacity by 40% and enabled recyclable mono-PP structures. Thinner mono-PP structures can maintain barrier performance while lowering plastic use per pack, even as roll demand rises in converting operations and brands pursue lower material intensity. Certification pathways promoted by ABRE and Abiplast can help converters show that their packaging meets recyclability requirements, document material choices for customers, and improve access to formal compliance programs.
Volatility in Polypropylene Resin Prices
Resin price changes remain a direct margin constraint for converters in the South America polypropylene (PP) packaging film market. PP homopolymer spot prices in Brazil ranged from USD 970 to USD 1,020 per metric ton in May 2025, and subsequent supply disruptions increased local price pressure. Many converters buy resin in USD while selling finished film in the local currency, creating simultaneous exposure to resin price increases and currency depreciation. Brazil imported 3.32 million metric tons of plastic resin in 2025, showing that converters continue to replace import origins rather than reduce their material needs. Brazil's PRESIQ program is set to provide BRL 3 billion (USD 580 million) in annual chemical-industry incentives for 5 years from 2027, but it does not remove near-term spot-market risk. Long-term resin contracts, flexible sourcing, careful price pass-through, and efficient inventory planning remain important for converters seeking to protect margins.
Other drivers and restraints analyzed in the detailed report include:
- E-Commerce and Secondary Packaging Resilience Requirements
- Regional BOPP and CPP Capacity Additions
- Competition From Paper, Aluminum, and Polyethylene Structures
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
BOPP film held 72.34% of the South America polypropylene (PP) packaging film market in 2025. Its position rests on broad compatibility with gravure and flexographic printing, high processing speeds, and use across snack, coffee, dairy, and confectionery packaging. Transparent grades are widely used for shelf-stable bakery and snack wraps because they provide product visibility and work efficiently on automated lines. Metallized BOPP gained support after Vitopel's 2024 metallizer investment increased capacity by 40% and targeted processed cheese, powdered milk, and oilseed packaging. Coated grades with PVDC, acrylic, or EVOH layers serve export food formats that need stronger oxygen and moisture barriers, while uncoated BOPP remains common in label stock, primary wraps, and value-oriented confectionery applications.
Cast polypropylene, commonly called CPP, is projected to grow at an 8.16% CAGR through 2031, the fastest rate among film types. Pharmaceutical lidding and blister applications value its thermal stability and controlled seal-peel performance, while general-purpose grades support multilayer pouches and laminate substrates. Retort-grade CPP is used for ready meals and processed foods that must retain film integrity during high-temperature sterilization cycles. Metallized CPP is gaining use in premium coffee and snack packs as an alternative to foil-based structures where mono-material recyclability is important. Other oriented and cast PP variants occupy smaller technical niches in the South America polypropylene (PP) packaging film industry, serving specific barrier, sealing, and processing requirements.
Complete Report Scope:
- By Film Type
- Biaxially Oriented Polypropylene (BOPP) Film
- Coated BOPP (PVDC, Acrylic, EVOH)
- Uncoated BOPP
- Chlorinated Polypropylene (CPP) Film
- General-Purpose CPP
- Retort-Grade CPP
- Metallized CPP
- Other Film Types
- Biaxially Oriented Polypropylene (BOPP) Film
- By Packaging Format
- Wraps and Over-wraps
- Labels and Pressure-Sensitive Tapes
- Bags and Pouches
- Lidding and Flow-wrap Films
- Blister and Strip Packs
- By End-Use Industry
- Food
- Bakery and Confectionery
- Snacks and Breakfast Cereals
- Fresh Produce
- Meat, Poultry, and Seafood
- Dairy Products
- Beverages
- Non-Alcoholic Beverages
- Bottled Water
- Carbonated Drinks
- Juices
- Other Non-Alcoholic Beverages
- Alcoholic Beverages
- Beer
- Spirits
- Other Alcoholic Beverages
- Non-Alcoholic Beverages
- Pharmaceutical and Healthcare
- Personal Care and Cosmetics
- Industrial
- Other End-Use Industries
- Food
- By Geography
- Brazil
- Argentina
- Chile
- Colombia
- Rest of South America
List of Companies Covered in this Report:
- Oben Holding Group S.A.C.
- Taghleef Industries, Inc.
- Innovia Films Limited
- Cosmo Films Limited
- Inteplast Group, Ltd.
- Toray Industries, Inc.
- UFlex Limited
- Manucor S.p.A.
- Poligal S.A.
- Vacmet India Limited
- Toppan Speciality Films Private Limited
- Altopro S.A. de C.V.
- Grupo Plastilene S.A.S.
- Vitopel do Brasil Ltda.
- Innova S.A.
- Valfilm S.A.
- Prolam S.A.
- Sigmaplast S.A.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Packaged Food and Convenience Consumption Expansion
- 4.2.2 Shift Toward Recyclable Mono-Polypropylene Structures
- 4.2.3 E-Commerce and Secondary-Packaging Resilience Requirements
- 4.2.4 Regional BOPP and CPP Capacity Additions
- 4.2.5 Higher Barrier and Shelf-Life Requirements
- 4.2.6 Export-Oriented Fresh Food and Seafood Packaging Growth
- 4.3 Market Restraints
- 4.3.1 Volatility in Polypropylene Resin Prices
- 4.3.2 Competition From Paper, Aluminum and Polyethylene Structures
- 4.3.3 Limited Collection and Recycling Infrastructure
- 4.3.4 Electricity, Foreign-Exchange and Import-Cost Exposure
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Film Type
- 5.1.1 Biaxially Oriented Polypropylene (BOPP) Film
- 5.1.1.1 Coated BOPP (PVDC, Acrylic, EVOH)
- 5.1.1.2 Uncoated BOPP
- 5.1.2 Chlorinated Polypropylene (CPP) Film
- 5.1.2.1 General-Purpose CPP
- 5.1.2.2 Retort-Grade CPP
- 5.1.2.3 Metallized CPP
- 5.1.3 Other Film Types
- 5.1.1 Biaxially Oriented Polypropylene (BOPP) Film
- 5.2 By Packaging Format
- 5.2.1 Wraps and Over-wraps
- 5.2.2 Labels and Pressure-Sensitive Tapes
- 5.2.3 Bags and Pouches
- 5.2.4 Lidding and Flow-wrap Films
- 5.2.5 Blister and Strip Packs
- 5.3 By End-Use Industry
- 5.3.1 Food
- 5.3.1.1 Bakery and Confectionery
- 5.3.1.2 Snacks and Breakfast Cereals
- 5.3.1.3 Fresh Produce
- 5.3.1.4 Meat, Poultry, and Seafood
- 5.3.1.5 Dairy Products
- 5.3.2 Beverages
- 5.3.2.1 Non-Alcoholic Beverages
- 5.3.2.1.1 Bottled Water
- 5.3.2.1.2 Carbonated Drinks
- 5.3.2.1.3 Juices
- 5.3.2.1.4 Other Non-Alcoholic Beverages
- 5.3.2.2 Alcoholic Beverages
- 5.3.2.2.1 Beer
- 5.3.2.2.2 Spirits
- 5.3.2.2.3 Other Alcoholic Beverages
- 5.3.2.1 Non-Alcoholic Beverages
- 5.3.3 Pharmaceutical and Healthcare
- 5.3.4 Personal Care and Cosmetics
- 5.3.5 Industrial
- 5.3.6 Other End-Use Industries
- 5.3.1 Food
- 5.4 By Geography
- 5.4.1 Brazil
- 5.4.2 Argentina
- 5.4.3 Chile
- 5.4.4 Colombia
- 5.4.5 Rest of South America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Oben Holding Group S.A.C.
- 6.4.2 Taghleef Industries, Inc.
- 6.4.3 Innovia Films Limited
- 6.4.4 Cosmo Films Limited
- 6.4.5 Inteplast Group, Ltd.
- 6.4.6 Toray Industries, Inc.
- 6.4.7 UFlex Limited
- 6.4.8 Manucor S.p.A.
- 6.4.9 Poligal S.A.
- 6.4.10 Vacmet India Limited
- 6.4.11 Toppan Speciality Films Private Limited
- 6.4.12 Altopro S.A. de C.V.
- 6.4.13 Grupo Plastilene S.A.S.
- 6.4.14 Vitopel do Brasil Ltda.
- 6.4.15 Innova S.A.
- 6.4.16 Valfilm S.A.
- 6.4.17 Prolam S.A.
- 6.4.18 Sigmaplast S.A.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


