

|
시장보고서
상품코드
2154898
남미의 IP 카메라 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)South America IP Camera - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
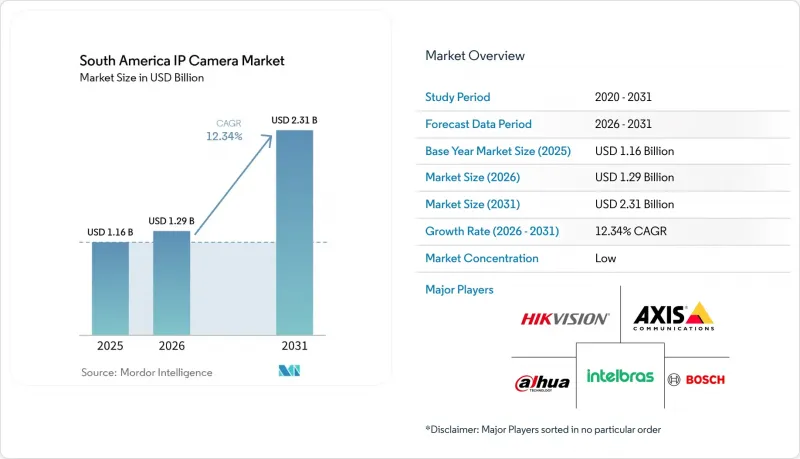
에 따르면 남미의 IP 카메라 시장 규모는 2025년에 116만 달러로 평가되며, 2026-2031년 예측 기간의 CAGR 12.34%로 확대하며, 2031년까지 231만 달러에 달할 것으로 추정되고 있습니다.
남미 IP 카메라 시장의 동향 및 인사이트
공공안전 및 도시 감시에 대한 투자 확대
남미 IP 카메라 시장에서 정부의 조달은 수요의 주요 원천으로 작용하고 있으며, 특히 각 도시가 개별 감시 툴을 공유형 관제실 시스템으로 대체하고 있는 지역에서 이러한 경향이 두드러집니다. 'O GLOBO' 신문에 따르면 리우데자네이루 주는 2026년 1월 ‘Programa Sentinela’를 시작하여 각 지자체 및 관제 센터를 대상으로 AI 카메라를 대규모로 조달하고 있습니다. 이 프로그램의 규모는 카메라, 분석 툴, 네트워크 인프라, 데이터 스토리지, 현장 설치 및 지휘 센터 서비스에 대한 수요를 지원하고 있습니다. 메데인의 C5i 지휘 센터는 2026년 7월 현재 건설 중이며, AI 영상 분석, 드론 감시, 차량 번호판 인식 장치, 전용 데이터센터 등이 도입될 예정입니다. 이러한 프로젝트에서는 개별 장비 판매가 아닌 통합 시스템을 지원하고, 여러 기술 계층을 조율할 수 있는 공급업체가 우대받습니다. 또한 프레임워크 계약을 통해 공공 부문 계약을 목표로 하는 벤더에 대한 자격 요건이 강화될 가능성이 있으며, 여기에는 현지 도입 능력 및 지속적인 서비스 제공 능력 등이 포함됩니다.
기존 설비의 아날로그에서 IP로의 교체
기존 아날로그 설비는 남미의 IP 카메라 시장에서 특히 산업 시설, 상업 빌딩, 소규모 지자체 시설에서 긴 교체 주기를 초래하고 있습니다. 우시미나스(Ushiminas)사는 기존 동축 케이블 배선을 유지하는 인코더 섀시를 사용하여 쿠바타오 시설을 아날로그에서 IP로 업그레이드함으로써, 대규모 산업 시설에서 전면적인 배선 공사의 필요성을 줄였습니다. 이러한 접근 방식을 통해 업무 차질을 최소화하고, 과거의 배선 투자를 활용하며, 레거시 장비를 갖춘 시설의 전환 기간을 단축할 수 있습니다. 또한 브라질 전자 보안 업계에서는 AI 활용이 확대되고 있으며, 이로 인해 카메라 교체와 분석 기능에 대한 수요가 연계되고 있습니다. 변환 키트의 가용성이 높아짐에 따라 물리적 변경을 최소화해야 하는 정기적인 업데이트 프로젝트에서 하드웨어 가격에 하락 압력이 가해질 가능성이 있습니다. 따라서 남미의 IP 카메라 시장에서는 소프트웨어 라이선스, 시스템 통합, 분석 기능 설정 및 서비스 계약의 가치가 높아질 가능성이 있습니다.
개인정보 보호, 사이버 보안 및 데이터 주권과 관련된 위험
개인정보 보호 규정 준수는 남미 IP 카메라 시장에서 중요한 조달 과제가 되고 있습니다. 브라질의 LGPD(일반 데이터 보호법)는 얼굴 이미지를 포함한 생체인식 데이터를 민감한 개인 데이터로 취급하며, 이를 처리하기 위해서는 법적 근거가 필요합니다. 칠레의 데이터 보호법에는 향후 몇 년 내에 시행될 예정인 새로운 의무 사항이 도입된 반면, 페루에서는 공공장소에서의 실시간 생체인식 감시를 제한하는 규정이 공포되었습니다. 국가마다 다른 규제로 인해 공급업체는 시스템 구성, 데이터 보존 정책 및 접근 제어를 이에 맞게 조정해야 합니다. 연결된 카메라는 더 광범위한 기업 네트워크로의 침입 경로가 될 수 있으므로, 사이버 보안 역시 마찬가지로 중요해지고 있습니다. CrowdStrike의 보고서에 따르면 남미 지역의 랜섬웨어 공격은 전년 대비 현저한 증가세를 보이고 있으며, 그중에서도 브라질이 가장 큰 타격을 입었습니다. 이에 따라 기기의 인증 정보, 네트워크 세분화, 소프트웨어 업데이트, 그리고 설치 후 연결된 카메라의 관리에 대한 명확한 책임 소재가 더욱 주목받고 있습니다.
부문 분석
2025년, 남미 IP 카메라 시장 점유율의 50.14%를 고정형 카메라가 차지했습니다. 이는 고정식 경계선, 입구, 복도, 소매점, 은행, 주택 등의 용도에서 대규모 설치가 필요하기 때문입니다. 간단한 운영 모델 덕분에 촬영 범위와 시야각이 안정적인 현장에 적합합니다. PTZ 카메라는 경찰, 교통 기관 및 주변 경비 팀이 방향 전환이 가능한 광학 시스템을 필요로 하므로 2031년까지 연평균 성장률(CAGR) 12.82%로 확대될 것으로 예측됩니다. PTZ 카메라 1대로 지휘 센터 용도에서 일반적으로 여러 대의 고정형 카메라가 필요한 구역을 커버할 수 있습니다. 한화비전은 2025년 8월, 리마의 산티아고 데 술코 지역에 번호판 인식 기능과 360도 멀티 센서 기능 등을 갖춘 AI 카메라 약 2,000대를 도입했습니다. 이 도입 사례는 기존의 고정형 카메라 네트워크와 병행하여 능동적이고 광범위한 감시가 가능함을 보여줍니다. 또한 단일 설계로는 상시 감시와 변화하는 활동에 대한 유연한 시야를 모두 제공할 수 없는 경우, 지자체에서 여러 형태의 카메라를 조합하여 활용할 수 있음을 보여줍니다.
배리포컬 카메라는 완전 전동식 이동 기능에 드는 비용을 피하면서도 초점 거리 조정이 필요한 상업용 건물 관리자에게 여전히 유용합니다. 따라서 남미의 IP 카메라 시장에는 고정식과 PTZ식 설계의 중간에 위치하는 실용적인 대안이 존재합니다. AI를 활용한 추적 기능으로 인해 PTZ 시스템 도입시 소프트웨어 호환성이 점점 더 중요해지고 있습니다. 상파울루의 ‘Smart Sampa’ 플랫폼과 리우데자네이루의 ‘CIVITAS’ 프로그램은 주요 공공 시스템이 분석 주도형 감시 아키텍처를 어떻게 채택하고 있는지를 보여줍니다. 추적 성능은 카메라, 영상 관리 시스템 및 분석 플랫폼이 서로 연동되어 작동하는지에 따라 좌우됩니다. 이로 인해 공공 입찰에서 인증된 통합 솔루션의 중요성이 높아지며, 소프트웨어 파트너십이 취약한 공급업체의 기회는 제한될 수 있습니다. 또한 구매자 입장에서는 기술 사양만으로 장비를 선정하는 것이 아니라, 분석 기능, 카메라 제어, 경보 기능 및 운영자의 워크플로우 신뢰성을 종합적으로 평가해야 할 실질적인 이유가 됩니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 업계 밸류체인 분석
- 거시경제 요인이 시장에 미치는 영향
- 규제 상황
- 기술 전망
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 카메라 설계 유형별
- 최종사용자 산업별
- 지역별
- 브라질
- 아르헨티나
- 칠레
- 콜롬비아
- 페루
- 기타 남미 국가
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- Hangzhou Hikvision Digital Technology Co., Ltd.
- Zhejiang Dahua Technology Co., Ltd.
- Intelbras S.A.
- Axis Communications AB
- Robert Bosch GmbH
- Hanwha Vision Co., Ltd.
- Honeywell International Inc.
- Panasonic Holdings Corporation
- Sony Group Corporation
- Motorola Solutions, Inc.
- VIVOTEK Inc.
- Zhejiang Uniview Technologies Co., Ltd.
- Tiandy Technologies Co., Ltd.
- Teledyne FLIR LLC
- Pelco, Inc.
- Genetec Inc.
- Eagle Eye Networks, Inc.
- Milestone Systems A/S
- Johnson Controls International plc
- Schneider Electric SE
제7장 시장 기회와 향후 전망
KSA 26.10.28According to Mordor Intelligence, the South America IP camera market size was valued at USD 1.16 million in 2025 and is estimated to expand to USD 2.31 million by 2031, at a CAGR of 12.34% during the forecast period 2026-2031.
South America IP Camera Market Trends and Insights
Rising Public Safety and Urban Surveillance Investment
Government procurement is a major source of volume for the South America IP camera market, especially where cities are replacing separate monitoring tools with shared control-room systems. Rio de Janeiro state launched Programa Sentinela in January 2026, involving a major procurement of AI cameras across municipalities and control centers, according to O GLOBO. The scale of the program supports demand for cameras, analytics, network infrastructure, data storage, field installation, and command-center services. Medellin's C5i command center was under construction as of July 2026 and includes AI video analytics, drone monitoring, license-plate readers, and a dedicated data center. These projects favor suppliers that can support integrated systems instead of single-device sales and coordinate several technology layers. Framework agreements may also raise the qualification requirements for vendors seeking public-sector contracts, including local implementation and continuing service capacity.
Analog to IP Replacement Across Existing Installations
Existing analog installations create a long replacement cycle for the South America IP camera market, particularly in industrial facilities, commercial buildings, and smaller municipal sites. Usiminas upgraded its Cubatao facility from analog to IP using an encoder chassis that retained existing coaxial cable runs, reducing the need for full rewiring at a large industrial site. This approach can reduce disruption, preserve earlier cabling investments, and shorten the transition for facilities with legacy equipment. The Brazilian electronic security sector is also increasing its use of AI, which links camera replacement with demand for analytics capability. As conversion kits become more available, hardware pricing may face pressure in routine replacement projects that need limited physical changes. Software licenses, system integration, analytics configuration, and service agreements could therefore carry more value in the South America IP camera market.
Privacy, Cybersecurity, and Data Sovereignty Exposure
Privacy compliance is a material procurement issue in the South America IP camera market. Brazil's LGPD treats biometric data, including facial images, as sensitive personal data and requires a legal basis for processing. Chile's data-protection law introduced new obligations that are scheduled to enter into force in the coming years, while Peru issued rules that restrict real-time biometric surveillance in public spaces. Different country rules require vendors to adapt system configurations, data retention practices, and access controls. Cybersecurity has become equally important because connected cameras can provide an entry point into wider corporate networks. CrowdStrike reported a notable year-over-year increase in ransomware attacks in South America, with Brazil the most affected country. This places greater attention on device credentials, network segmentation, software updates, and clear responsibility for managing connected cameras after installation.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Smart City and Transport Monitoring Programs
- Falling Camera, Storage, and Edge Processing Costs
- High Installation and Maintenance Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Fixed cameras held 50.14% of the South America IP camera market share in 2025 because static perimeter, entrance, corridor, retail, banking, and residential applications require large installation volumes. Their simple operating model makes them suitable for sites where coverage areas and viewing angles remain stable. PTZ cameras are projected to expand at a CAGR of 12.82% through 2031 as police, transit operators, and perimeter-security teams need redirectable optics. A PTZ device can cover areas that could otherwise require several fixed cameras in command-center applications. Hanwha Vision deployed nearly 2,000 AI cameras in Lima's Santiago de Surco district in August 2025, including license-plate recognition and 360-degree multi-sensor capabilities. The deployment shows that active and wide-area coverage can be used alongside conventional fixed camera networks. It also illustrates how municipalities can combine several camera formats when a single design cannot provide both constant coverage and flexible views of changing activity.
Varifocal cameras remain relevant for commercial building managers that need adjustable focal lengths without the cost of fully motorized movement. The South America IP camera market therefore includes a practical middle tier between fixed and PTZ designs. AI-enabled tracking is increasing the importance of software compatibility for PTZ installations. Sao Paulo's Smart Sampa platform and Rio de Janeiro's CIVITAS program illustrate how major public systems are adopting analytics-driven monitoring architectures. Tracking performance depends on the camera, video management system, and analytics platform working together. This can make certified integrations more important in public tenders and can limit opportunities for suppliers with weak software partnerships. It also gives buyers a practical reason to assess the reliability of analytics, camera control, alerting, and operator workflows together rather than selecting devices on technical specifications alone.
Complete Report Scope:
- By Camera Design Type
- Fixed
- Pan-Tilt-Zoom (PTZ)
- Varifocal
- By End-user Industry
- Residential
- Commercial
- Industrial
- Government and Law Enforcement
- By Geography
- Brazil
- Argentina
- Chile
- Colombia
- Peru
- Rest of South America
List of Companies Covered in this Report:
- Hangzhou Hikvision Digital Technology Co., Ltd.
- Zhejiang Dahua Technology Co., Ltd.
- Intelbras S.A.
- Axis Communications AB
- Robert Bosch GmbH
- Hanwha Vision Co., Ltd.
- Honeywell International Inc.
- Panasonic Holdings Corporation
- Sony Group Corporation
- Motorola Solutions, Inc.
- VIVOTEK Inc.
- Zhejiang Uniview Technologies Co., Ltd.
- Tiandy Technologies Co., Ltd.
- Teledyne FLIR LLC
- Pelco, Inc.
- Genetec Inc.
- Eagle Eye Networks, Inc.
- Milestone Systems A/S
- Johnson Controls International plc
- Schneider Electric SE
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Public-Safety and Urban-Surveillance Investment
- 4.2.2 Analog-to-IP Replacement Across Existing Installations
- 4.2.3 Expansion of Smart-City and Transport-Monitoring Programs
- 4.2.4 Falling Camera, Storage and Edge-Processing Costs
- 4.2.5 Cloud-Managed Surveillance for Distributed Sites
- 4.2.6 Localized Analytics for Unreliable Connectivity
- 4.3 Market Restraints
- 4.3.1 Privacy, Cybersecurity and Data-Sovereignty Exposure
- 4.3.2 High Installation and Maintenance Costs
- 4.3.3 Import Duties, Currency Volatility and Tax Complexity
- 4.3.4 Shortage of Certified Integrators Outside Major Cities
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Camera Design Type
- 5.1.1 Fixed
- 5.1.2 Pan-Tilt-Zoom (PTZ)
- 5.1.3 Varifocal
- 5.2 By End-user Industry
- 5.2.1 Residential
- 5.2.2 Commercial
- 5.2.3 Industrial
- 5.2.4 Government and Law Enforcement
- 5.3 By Geography
- 5.3.1 Brazil
- 5.3.2 Argentina
- 5.3.3 Chile
- 5.3.4 Colombia
- 5.3.5 Peru
- 5.3.6 Rest of South America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Hangzhou Hikvision Digital Technology Co., Ltd.
- 6.4.2 Zhejiang Dahua Technology Co., Ltd.
- 6.4.3 Intelbras S.A.
- 6.4.4 Axis Communications AB
- 6.4.5 Robert Bosch GmbH
- 6.4.6 Hanwha Vision Co., Ltd.
- 6.4.7 Honeywell International Inc.
- 6.4.8 Panasonic Holdings Corporation
- 6.4.9 Sony Group Corporation
- 6.4.10 Motorola Solutions, Inc.
- 6.4.11 VIVOTEK Inc.
- 6.4.12 Zhejiang Uniview Technologies Co., Ltd.
- 6.4.13 Tiandy Technologies Co., Ltd.
- 6.4.14 Teledyne FLIR LLC
- 6.4.15 Pelco, Inc.
- 6.4.16 Genetec Inc.
- 6.4.17 Eagle Eye Networks, Inc.
- 6.4.18 Milestone Systems A/S
- 6.4.19 Johnson Controls International plc
- 6.4.20 Schneider Electric SE
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


