

|
시장보고서
상품코드
2155563
장시간 지속형 주사제 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Long Acting Injectables - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
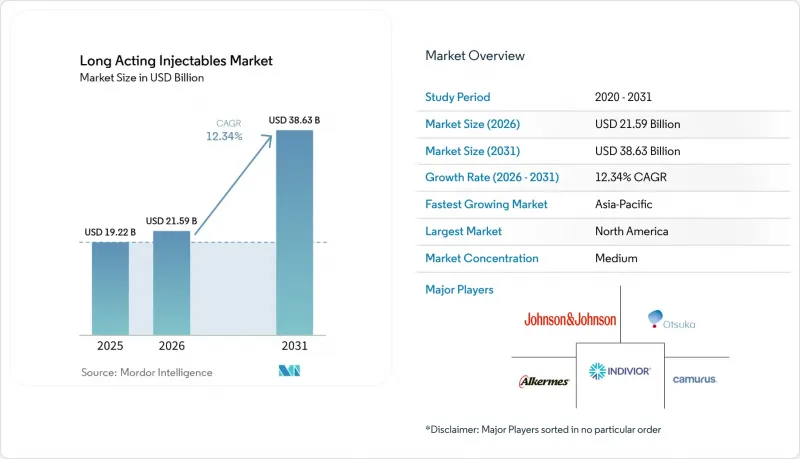
에 의하면, 장시간 지속형 주사제 시장 규모는 2025년에 192억 2,000만 달러로 평가되었고, 2026년 215억 9,000만 달러에서 2031년까지 386억 3,000만 달러에 이를 것으로 예측되며, 예측 기간(2026년-2031년) CAGR은 12.34%를 기록할 전망입니다.
세계 장시간 지속형 주사제 시장 동향 및 인사이트
만성 질환 관리에서의 복약 순응도 향상 및 재발 예방
경구용 항정신병 약물의 복약 순응도 저하는 조현병 스펙트럼 장애 환자의 거의 절반에 영향을 미치고 있으며, 정신과 입원 의료비의 대폭적인 증가 요인 중 하나였습니다. 미국정신의학회는 진단 확정 후, 보다 조기에 지속형 주사제(LAI)의 도입을 검토할 것을 권장하고 있으며, 이로 인해 경구 치료의 실패가 확인된 환자뿐만 아니라 대상 환자층이 확대되었습니다. 2026년 튀르키예에서 149명의 환자를 대상으로 실시된 미러 이미지 연구에서는 LAI 시작에 따라 이전 경구 치료 기간과 비교하여 입원 위험이 80% 감소하고 재발 위험이 83% 감소한 것으로 나타났습니다. 2025년 EULAST 임상시험 분석 결과, 초기 단계의 조현병 및 동반된 약물 사용 장애를 가진 환자에서 LAI는 경구용 항정신병 약물과 비교하여 모든 원인에 의한 치료 중단 위험을 36% 감소시키는 것으로 밝혀졌습니다.
장시간 작용형 HIV 치료 및 노출 전 예방(PrEP)의 확대
장시간 작용형 HIV 치료제는 복약 순응도를 지원하기 위한 특수한 해결책에서 확립된 임상적 선택지로 진화했습니다. FDA는 2025년 6월, 길리어드사의 연 2회 투여제인 ‘Yeztugo(레나카파비르)’를 노출 전 예방(PrEP)제로 승인했습니다. 이는 참가자의 최소 99.9%가 HIV 음성 상태를 유지한 PURPOSE 1 및 PURPOSE 2 임상시험 결과를 바탕으로 한 것입니다. ViiV 헬스케어의 LATITUDE 3상 임상시험에서는 복약 순응도에 어려움을 겪는 환자군에서 카베누바(Cabenuva)가 치료 요법 실패의 누적 위험을 22.8%로 낮춘 반면, 매일 경구 투여하는 치료법의 경우 41.2%로 나타났습니다. CDC의 2025년 임상 권고안과 133개국을 아우르는 ViiV 헬스케어의 의약품 특허 풀(MPP) 라이선스 확대는 사하라 이남 아프리카 및 남아시아 지역의 접근성 및 임상 역량 향상을 지원했습니다.
높은 도입 비용과 보험 급여의 복잡성
강력한 임상적 근거가 있음에도 불구하고, 새로운 장기 작용형 주사제(LAI)는 규제 당국의 승인이 일상적인 보험 적용을 보장하는 것은 아니기 때문에 보급이 지연될 가능성이 있습니다. 예즈투고의 미국 내 연간 정가는 2만 8,218달러로, 이로 인해 약제 목록 등재 결정 및 환자의 접근성에 대한 관심이 높아지고 있습니다. CVS 케어마크는 협상 과정에서 당초 예즈투고를 자사의 상업용 및 ACA(환자 보호 및 의료비 부담 적정화법)에 따른 약제 목록에서 제외했기 때문에 치료 시작이 지연되었습니다. 인플레이션 억제법에 따른 메디케어 파트 D 급여 제도의 재검토로 인해, 고비용 LAI 항정신병 약물에 대한 보험 플랜의 인센티브가 변경되어 사전 승인 및 단계적 치료의 이용이 증가했을 가능성이 있습니다. 파모산 올란자핀의 REMS에서는 인증된 시설에서 주사 후 3시간 동안의 모니터링이 의무화되어 투여 비용이 증가했으나, TEV-749는 REMS가 필요 없는 설계로 이를 회피하는 것을 목표로 했습니다.
부문 분석
2025년, 중추신경계(CNS) 질환은 장기 작용형 주사제 시장의 45.23%를 차지했습니다. 이는 조현병, 조현정동장애 및 양극성 I형 장애에 대한 항정신병 LAI의 확립된 사용에 힘입은 결과입니다. 팔리페리돈 팔미테이트는 PP1M, PP3M, PP6M 제형이 이용 가능하며, 1개월, 3개월, 6개월마다의 치료 간격에 대응합니다. 오츠카 제약과 알케르메스사의 아리피프라졸 LAI 제품군 또한 확립된 정신과 치료 대상 환자층을 대상으로 합니다. 이러한 제품들은 증상 안정화부터 장기 유지 요법에 이르기까지 환자 관리를 지원합니다.
감염병 분야는 HIV 치료 및 예방을 주축으로 2026년부터 2031년에 걸쳐 연평균 성장률(CAGR) 14.53%를 나타낼 것으로 예측됩니다. 2026년 4월 현재, FDA는 ‘카베누바’를 1-2개월마다 투여하는 방식, ‘산렌카’를 6개월마다 투여하는 방식, ‘예즈투고’를 연 2회 투여하는 PrEP(노출 전 예방) 옵션으로 승인했습니다. 이러한 투여 간격의 확대로 인해 환자와 임상의의 선택지가 넓어졌으며, LAI(장시간 지속형 주사제)의 용도가 정신과 치료의 범위를 넘어 확대되고 있습니다. 대사·내분비 질환은 전립선암이나 유방암의 호르몬 관리를 위한 LHRH 작용제의 저장제 제제에 힘입어 안정적인 치료 분야로 자리 잡고 있습니다. 카무라스(Kamuras)사는 2025년 말, 아크로메갈리아 치료제로월1회 피하 투여형 옥트레오타이드 ‘CAM2029’를 독일에서 출시했습니다.
2025년 시점에서 장시간 지속형 주사제 시장의 78.55%를 저분자 의약품이 차지하고 있었습니다. 이러한 주도적인 지위는 서방형 제제 개발 분야에서 항정신병제, 항레트로바이러스제 및 LHRH 작용제가 성숙 단계에 접어들었음을 반영합니다. PLGA 마이크로스피어와 나노결정 현탁액은 많은 유효 성분에서 확립되어 있지만, 규제상의 선례에 있어서는 새로운 생물학적 제제의 데포 제제보다 저분자 LAI가 더 잘 정비되어 있습니다.
생물학적 제제는 2026년부터 2031년까지 연평균 성장률(CAGR) 14.67%를 나타낼 것으로 예측됩니다. 이러한 전망을 뒷받침하는 것은 HIV 광범위 중화 항체 프로그램과 새롭게 등장하고 있는 자가면역 질환용 LAI 프로그램입니다. ViiV 헬스케어의 제IIb상 EMBRACE 임상시험에서 로티비바트를월1회 카보테그라빌 근육 내 투여와 병용한 경우, 정맥 내 투여군의 94%, 피하 투여군의 82%에서 바이러스 억제가 유지된 것으로 나타났습니다. 이러한 연구 결과는 생물학적 제제의 전달 기술이 여러 투여 경로를 통해 지속적인 약동학적 활성을 뒷받침할 수 있음을 보여줍니다.
지역별 분석
2025년, 북미는 지속형 주사제 시장의 41.67%를 차지했습니다. 이 지역은 확립된 전문 약국 인프라, 메디케어 파트 B에 기반한 ‘구매 및 청구(buy-and-bill)’ 방식의 환급 제도, 그리고 지원적인 규제 환경의 혜택을 받고 있습니다. FDA는 2025년 6월, HIV 노출 전 예방(PrEP) 용도로 연 2회 투여하는 ‘Yeztugo’를 승인했으며, 2026년 2월에는 지속형 주사제인 올란자핀 제제 ‘TEV-749’의 신약 승인 신청을 접수했습니다. 캐나다에서는 2025년 1월 ‘ABILIFY ASIMTUFII’가 승인되어, 조현병 및 양극성 I형 장애에 대한 2개월마다 투여하는 아리피프라졸 제제의 선택지가 도입되었습니다.
유럽은 두 번째로 큰 지역으로, 독일, 영국, 프랑스, 이탈리아, 스페인이 주요 상업 시장이 되었습니다. 유럽연합 집행위원회는 HIV 예방약 ‘Yeytuo’를 승인하여 유럽연합(EU) 회원국, 노르웨이, 아이슬란드, 리히텐슈타인에서의 사용을 확대했습니다. Camurus사는 2025년 11월, 독일에서월1회 투여하는 피하 투여형 옥트레오티드 제제 ‘Oczyesa(CAM2029)’를 출시했습니다. 한편, 유럽의약품청(EMA)은 2026년 5월 TEV-749의 판매 승인 신청을 접수했습니다. 사전 승인 지연, 파트 D 제도 개편, 그리고 치료상의 이점과 안전성 입증을 요구하는 지불자 측의 요건은 선진국 시장 전반에 걸쳐 여전히 중요한 과제로 남아 있었습니다.
아시아태평양은 2026년부터 2031년에 걸쳐 연평균 성장률(CAGR) 14.22%를 나타낼 것으로 예측됩니다. 중국에서는 바이오시밀러 및 혁신적인 LAI(장시간 지속형 주사제)의 개발에 힘입어 의료 인프라와 국내 생산 능력이 확대되었습니다. 한편, 일본에서는 고령화의 진행과 외래 정신과 의료에 대한 집중으로 인해 치료 간격이 길어지는 현상이 가속화되었습니다. 2026년 연구에서는 PP3M의 지속률이 임상시험 결과와 일치하는 것으로 보고되었으며, 호주에서는 2026년 1월 HIV 예방 투여(PrEP) 약물로 ‘Yeytuo’가 승인되었습니다. 한국에서는 지역 내 LAI 생산이 지원될 가능성이 있으며, 중동 및 아프리카 및 남미에서는 접근성 프로그램, 호르몬계 LAI, 항정신병 약물의 제네릭 저장형 제제를 통해 추가적인 기회가 기대됩니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사의 전제조건과 시장의 정의
- 조사 범위
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 밸류·공급망 분석
- 규제 상황
- 기술 전망
- Porter의 Five Forces 분석
제5장 시장 규모와 성장 예측
- 치료 영역별
- 분자 유형별
- 기술별
- 투여 경로별
- 최종사용자별
- 지역별
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 스페인
- 기타 유럽 국가
- 아시아태평양
- 중국
- 인도
- 일본
- 호주
- 한국
- 기타 아시아태평양 국가
- 중동 및 아프리카
- GCC
- 남아프리카공화국
- 기타 중동 및 아프리카 국가
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 북미
제6장 경쟁 구도
- 시장 집중도
- 시장 점유율 분석
- 기업 개요
- Alkermes plc
- Amneal Pharmaceuticals, Inc.
- Aurobindo Pharma Limited
- Camurus AB
- Dr. Reddy's Laboratories Limited
- H. Lundbeck A/S
- Indivior PLC
- Johnson & Johnson
- Lupin Limited
- Luye Pharma Group Ltd.
- Mapi Pharma Ltd.
- MedinCell S.A.
- Novartis AG
- Otsuka Pharmaceutical Co., Ltd.
- Pharmathen S.A.
- Sun Pharmaceutical Industries Limited
- Teva Pharmaceutical Industries Ltd.
- Tolmar, Inc.
- Viatris Inc.
- ViiV Healthcare Limited
- Zydus Lifesciences Limited
제7장 시장 기회와 향후 전망
LSH 26.10.29According to Mordor Intelligence, the Long-Acting injectables market size was valued at USD 19.22 billion in 2025 and is estimated to grow from USD 21.59 billion in 2026 to reach USD 38.63 billion by 2031, at a CAGR of 12.34% during the forecast period (2026-2031).
Global Long Acting Injectables Market Trends and Insights
Improved Adherence and Relapse Prevention in Chronic Disease Management
Oral antipsychotic nonadherence affected nearly half of individuals with schizophrenia spectrum disorders and contributed significantly to inpatient psychiatric spending. The American Psychiatric Association recommended considering long-acting injectables (LAIs) earlier after a confirmed diagnosis, expanding the eligible patient population beyond those with documented oral treatment failure. A 2026 mirror-image study of 149 patients in Turkey associated LAI initiation with an 80% reduction in hospitalization hazard and an 83% reduction in relapse hazard compared with prior oral treatment periods. A 2025 EULAST trial analysis found that LAIs reduced the risk of all-cause discontinuation by 36% versus oral antipsychotics among individuals with early-phase schizophrenia and comorbid substance use disorder.
Expansion of Long-Acting HIV Treatment and Pre-Exposure Prophylaxis
Long-acting HIV therapies evolved from specialized adherence solutions into established clinical options. The FDA approved Gilead's twice-yearly Yeztugo (lenacapavir) for pre-exposure prophylaxis (PrEP) in June 2025, following the PURPOSE 1 and PURPOSE 2 trials, in which at least 99.9% of participants remained HIV-negative. ViiV Healthcare's LATITUDE Phase III trial found that Cabenuva reduced the cumulative risk of regimen failure to 22.8%, compared with 41.2% for daily oral therapy among individuals with adherence challenges. The CDC's 2025 clinical recommendation and ViiV Healthcare's expanded Medicines Patent Pool license covering 133 countries supported access and clinical capacity development in Sub-Saharan Africa and South Asia.
High Acquisition Cost and Reimbursement Complexity
New LAIs may experience slow uptake despite strong clinical evidence, as regulatory approval does not ensure routine coverage. Yeztugo had a U.S. annual list price of USD 28,218, increasing focus on formulary decisions and patient access. CVS Caremark initially excluded Yeztugo from its commercial and ACA formularies during negotiations, delaying treatment initiation. The Medicare Part D benefit redesign under the Inflation Reduction Act changed plan incentives for high-cost LAI antipsychotics and may have increased the use of prior authorization or step therapy. The olanzapine pamoate REMS required 3-hour post-injection monitoring at a certified facility, increasing delivery costs, which TEV-749 aimed to avoid through its REMS-free design.
Other drivers and restraints analyzed in the detailed report include:
- Rising Need for Extended-Release Therapies in Opioid Use Disorder
- Formulation Platforms Enabling Monthly-to-Six-Month Dosing Intervals
- Manufacturing Scale-Up Risk for Sterile Suspensions and Complex Depots
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
CNS disorders accounted for 45.23% of the long-acting injectables market in 2025, supported by the established use of antipsychotic LAIs for schizophrenia, schizoaffective disorder, and bipolar I disorder. Paliperidone palmitate is available in PP1M, PP3M, and PP6M formulations, supporting 1-, 3-, and 6-month treatment intervals. Otsuka's and Alkermes' aripiprazole LAI portfolios also serve the established psychiatric treatment population. These products support patient management from stabilization through long-term maintenance.
Infectious diseases are forecast to grow at a CAGR of 14.53% between 2026 and 2031, driven by HIV treatment and prevention. As of April 2026, the FDA had approved Cabenuva for administration every 1 to 2 months, Sunlenca every 6 months, and Yeztugo as a twice-yearly PrEP option. These dosing intervals expand patient and clinician options and extend LAI use beyond psychiatric treatment. Metabolic and endocrine disorders remain a stable therapeutic area, supported by LHRH agonist depots for hormone management in prostate and breast cancer. Camurus launched monthly subcutaneous octreotide, CAM2029, in Germany in late 2025 for acromegaly.
Small molecules accounted for 78.55% of the long-acting injectables market in 2025. Their leadership reflects the maturity of antipsychotics, antiretrovirals, and LHRH agonists in controlled-release formulation development. PLGA microspheres and nanocrystal suspensions are well established for many active ingredients, while regulatory precedents remain more developed for small-molecule LAIs than for newer biologic depots.
Biologics are forecast to grow at a CAGR of 14.67% from 2026 to 2031. HIV broadly neutralizing antibody programs and emerging autoimmune LAI programs support this outlook. ViiV Healthcare's Phase IIb EMBRACE study found that lotivibart, combined with monthly intramuscular cabotegravir, maintained viral suppression in 94% of intravenous recipients and 82% of subcutaneous recipients. These findings indicate that biologic delivery can support durable pharmacokinetic activity across multiple administration routes.
Complete Report Scope:
- By Therapeutic Area
- Central Nervous System Disorders
- Infectious Diseases
- Metabolic and Endocrine Disorders
- Oncology and Supportive Care
- Substance Use Disorders
- Autoimmune and Inflammatory Diseases
- Reproductive Health and Contraception
- Other Therapeutic Areas
- By Molecule Type
- Small Molecules
- Biologics
- By Technology
- Polymer-Based Depot Systems
- Microsphere-Based Formulations
- In-Situ-Forming Depots
- Nanoformulations and Nanocrystal Suspensions
- Liposomal Systems
- Others
- By Route of Administration
- Intramuscular
- Subcutaneous
- Intradermal and Other Routes
- By End User
- Hospitals
- Specialty Clinics and Community Mental-Health Centers
- Ambulatory Care and Physician Offices
- Homecare Settings
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America accounted for 41.67% of the long-acting injectables market share in 2025. The region benefited from established specialty pharmacy infrastructure, buy-and-bill reimbursement under Medicare Part B, and a supportive regulatory environment. The FDA approved Yeztugo for twice-yearly HIV pre-exposure prophylaxis (PrEP) in June 2025 and accepted the new drug application for TEV-749, a long-acting injectable olanzapine formulation, in February 2026. Canada approved ABILIFY ASIMTUFII in January 2025, introducing a bimonthly aripiprazole option for schizophrenia and bipolar I disorder.
Europe was the second-largest geography, with Germany, the United Kingdom, France, Italy, and Spain serving as key commercial markets. The European Commission authorized Yeytuo for HIV prevention, extending access across European Union member states, Norway, Iceland, and Liechtenstein. Camurus launched Oczyesa, CAM2029, a monthly subcutaneous octreotide treatment, in Germany in November 2025, while the EMA accepted the marketing authorization application for TEV-749 in May 2026. Prior authorization delays, the Part D redesign, and payer requirements for demonstrated administration or safety benefits remained relevant across developed markets.
Asia-Pacific is forecast to grow at a CAGR of 14.22% from 2026 to 2031. China expanded healthcare infrastructure and domestic manufacturing capabilities, supported by biosimilar and innovative LAI development, while Japan's aging population and outpatient psychiatric care focus supported longer treatment intervals. A 2026 study reported PP3M continuation rates consistent with clinical trial findings, and Australia approved Yeytuo for HIV PrEP in January 2026. South Korea may support regional LAI production, while the Middle East and Africa and South America offer incremental opportunities through access programs, hormonal LAIs, and generic antipsychotic depot formulations.
- Alkermes plc
- Amneal Pharmaceuticals
- Aurobindo Pharma
- Camurus AB
- Dr. Reddy's Laboratories
- H. Lundbeck
- Indivior
- Johnson & Johnson
- Lupin
- Luye Pharma Group Ltd.
- Mapi Pharma Ltd.
- MedinCell S.A.
- Novartis
- Otsuka
- Pharmathen S.A.
- Sun Pharmaceuticals Industries
- Teva Pharmaceutical Industries
- Tolmar, Inc.
- Viatris
- ViiV Healthcare Limited
- Zydus Lifesciences Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Improved Adherence and Relapse Prevention in Chronic Disease
- 4.2.2 Expansion of Long-Acting HIV Treatment and Pre-Exposure Prophylaxis
- 4.2.3 Rising Need for Extended-Release Therapies in Opioid Use Disorder
- 4.2.4 Increasing Evidence for Lower Dosing Burden and Reduced Hospitalization
- 4.2.5 Formulation Platforms Enabling Monthly-to-Six-Month Dosing
- 4.2.6 Provider Workflow and Injection-Visit Infrastructure as a Commercial Adoption Lever
- 4.3 Market Restraints
- 4.3.1 High Acquisition Cost and Reimbursement Complexity
- 4.3.2 Injection-Site Reactions, Administration Burden, and Limited Reversibility
- 4.3.3 Manufacturing Scale-Up Risk for Sterile Suspensions and Complex Depots
- 4.3.4 Missed-Dose, Bridging, and Pharmacokinetic Tail-Management Complexity
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE, USD)
- 5.1 By Therapeutic Area
- 5.1.1 Central Nervous System Disorders
- 5.1.2 Infectious Diseases
- 5.1.3 Metabolic and Endocrine Disorders
- 5.1.4 Oncology and Supportive Care
- 5.1.5 Substance Use Disorders
- 5.1.6 Autoimmune and Inflammatory Diseases
- 5.1.7 Reproductive Health and Contraception
- 5.1.8 Other Therapeutic Areas
- 5.2 By Molecule Type
- 5.2.1 Small Molecules
- 5.2.2 Biologics
- 5.3 By Technology
- 5.3.1 Polymer-Based Depot Systems
- 5.3.2 Microsphere-Based Formulations
- 5.3.3 In-Situ-Forming Depots
- 5.3.4 Nanoformulations and Nanocrystal Suspensions
- 5.3.5 Liposomal Systems
- 5.3.6 Others
- 5.4 By Route of Administration
- 5.4.1 Intramuscular
- 5.4.2 Subcutaneous
- 5.4.3 Intradermal and Other Routes
- 5.5 By End User
- 5.5.1 Hospitals
- 5.5.2 Specialty Clinics and Community Mental-Health Centers
- 5.5.3 Ambulatory Care and Physician Offices
- 5.5.4 Homecare Settings
- 5.5.5 Others
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 India
- 5.6.3.3 Japan
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East and Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 Alkermes plc
- 6.3.2 Amneal Pharmaceuticals, Inc.
- 6.3.3 Aurobindo Pharma Limited
- 6.3.4 Camurus AB
- 6.3.5 Dr. Reddy's Laboratories Limited
- 6.3.6 H. Lundbeck A/S
- 6.3.7 Indivior PLC
- 6.3.8 Johnson & Johnson
- 6.3.9 Lupin Limited
- 6.3.10 Luye Pharma Group Ltd.
- 6.3.11 Mapi Pharma Ltd.
- 6.3.12 MedinCell S.A.
- 6.3.13 Novartis AG
- 6.3.14 Otsuka Pharmaceutical Co., Ltd.
- 6.3.15 Pharmathen S.A.
- 6.3.16 Sun Pharmaceutical Industries Limited
- 6.3.17 Teva Pharmaceutical Industries Ltd.
- 6.3.18 Tolmar, Inc.
- 6.3.19 Viatris Inc.
- 6.3.20 ViiV Healthcare Limited
- 6.3.21 Zydus Lifesciences Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


