

|
시장보고서
상품코드
2155579
남미의 상업용 항공기 객실 인테리어 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)South America Commercial Aircraft Cabin Interior - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
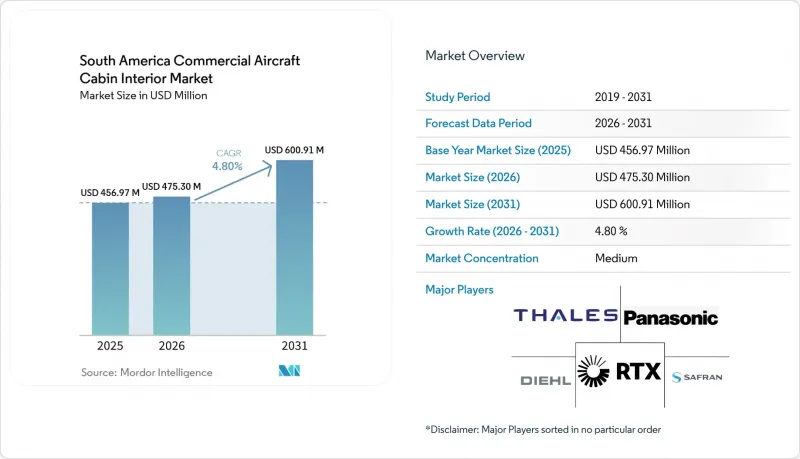
에 의하면, 남미의 상업용 항공기 객실 인테리어 시장 규모는 2025년에 4억 5,697만 달러로 평가되었고, 2026년 4억 7,530만 달러에서 2031년까지 6억 91만 달러로 확대되어 예측 기간(2026년-2031년)에 CAGR 4.80%를 기록할 전망입니다.
남미 상업용 항공기 객실 인테리어 시장 동향 및 인사이트
팬데믹 이후 여객 수 회복
2025년, 남미 민간 항공 부문은 지속적인 성장을 이어가며 기내 인테리어 공급업체들에게 비즈니스 기회를 제공했습니다. 아르헨티나에서는 여객 수가 전년 대비 13.2% 증가한 3,330만 명을 기록했으며, 국내선은 9.1%, 국제선은 18.2% 증가했습니다. 각 항공사는 기단 확충에 더해 객실 설비에 대한 투자도 진행하고 있습니다. 2025년 4월, 아줄 항공은 새로 도입하는 에어버스 A330 기종에 RECARO사의 비즈니스 클래스용 좌석 ‘CL6710’ 및 이코노미 클래스용 좌석 ‘CL3710’을 채택했으며, 2025년부터 납품이 시작될 예정입니다. 이러한 움직임에 따라 객실 설비 도입 대수가 증가함에 따라, 남미 전역에서 좌석, 교체용 부품, 정비 및 내장재 업그레이드에 대한 지속적인 수요가 뒷받침되고 있습니다.
엠브라에르 주도의 지역 항공기 기단 갱신
브라질에 본사를 둔 엠브라엘은 2025년에 78대의 상업용 항공기를 인도하여 2024년 대비 약 6.8% 증가했습니다. 또한, 이 회사의 상업용 항공기 수주 잔고는 연말 기준 145억 달러에 달했습니다. 이 회사는 2026년에도 80-85대의 상업용 항공기 인도를 목표로 하고 있습니다. 2026년 7월, 남미 항공사인 아비앙카와 GOL의 모회사인 아브라 그룹은 E195-E2 기종 20대 구매에 합의했으며, 추가로 10대의 구매 옵션과 15대의 구매권을 보유하고 있어 잠재적 총 대수는 45대에 달할 전망입니다. 첫 인도는 2027년 4분기로 예정되어 있습니다. E195-E2 플랫폼에는 좌석, 머리 위 수납공간, 갤리, 화장실 등의 객실 설비가 포함되어 있으며, 항공사의 요구 사항에 맞추어 연결 환경을 구성할 수 있습니다. 이 계약은 남미 지역의 객실 인테리어에 대한 향후 수요 창출의 계기가 될 가능성이 있습니다.
인증 및 감항성 준수에 드는 막대한 비용
남미 지역의 민간 항공기 객실 개조는 각국의 항공 적합성 및 정비 요건을 준수해야 합니다. 브라질의 ANAC, 칠레의 DGAC, 콜롬비아의 Aerocivil, 아르헨티나의 ANAC가 각 시장의 인증 및 정비 체계를 감독하고 있습니다. 대규모 개조에는 승인된 설계 데이터나 보충 형식 인증이 필요한 경우가 있으며, 또한 적절히 인가된 기관이 정비나 개조를 수행해야 합니다. 이러한 요건으로 인해 객실 개조 프로그램과 관련된 기술 문서, 엔지니어링, 검사 및 조정의 부담이 증가합니다. 인증된 설계, 승인된 부품 및 적격한 정비 역량의 필요성은 내장 개조 비용과 복잡성을 증가시켜 시장 전체의 프로젝트 일정에 영향을 미칠 수 있습니다.
부문 분석
2025년, 남미의 상업용 항공기 객실 인테리어 시장에서 좌석은 추정 30.45%를 차지했습니다. 이 지역의 대규모 협폭기 기단이 수요를 뒷받침하고 있으며, 여기에는 개조 공사와 신조 항공기 설치가 모두 포함됩니다. 프리미엄 캐빈 프로그램으로 인해 특정 장거리 노선 항공기의 인테리어 장비가 증가하는 한편, 이코노미 클래스 설치는 계속해서 더 많은 좌석 수를 창출하고 있습니다. 2025년 8월, RECARO사는 LATAM 항공의 B787-8 및 B787-9 기종을 대상으로 한 41대 규모의 PL3530 프리미엄 컴포트 개조 프로그램을 발표했으며, 2027년 상반기부터 납품을 시작할 예정입니다. 이 프로그램은 표준 이코노미 클래스 요건에 더해, 차별화된 좌석에 대한 지속적인 투자를 보여주는 것입니다.
IFEC는 가장 빠르게 성장하는 제품 카테고리가 될 것으로 예상되며, 2026년부터 2031년까지의 연평균 성장률(CAGR)은 6.25%로 추산됩니다. 2026년 7월, SES는 향후 몇 년간 LATAM의 A320neo, A321XLR 및 E195-E2 기종 60대 이상에 멀티오빗 연결 기능을 탑재할 사업자로 선정되었습니다. LATAM은 이미 SES 연결 기능을 갖춘 항공기 250대 이상을 운항하고 있습니다. 이 프로그램은 전자 제어 안테나, 기내 네트워크 통합, 소프트웨어, 설치 및 유지보수 지원에 대한 수요를 뒷받침하고 있습니다. 갤리, 기념물, 머리 위 수납함, 조명, 인테리어 패널은 여전히 중요한 라인핏 및 레트로핏 부문이며, 항공사들이 기존의 인테리어 업그레이드와 연결된 승객 경험 시스템을 결합함에 따라 객실 설비 분야의 비즈니스 기회는 확대되고 있습니다.
2025년 남미 상업용 항공기 객실 인테리어 시장에서 협폭기(narrow-body)가 추정 68.50%를 차지했습니다. 이 점유율은 국내선 및 지역 노선에서 운항되는 방대한 도입 기수를 반영합니다. LATAM만 해도 2025년 말 기준으로 에어버스 협폭체 여객기 291대를 보유하고 있는 반면, 광폭체 항공기는 60대에 불과했습니다. 다양한 운항 모델로 인해 고밀도 레이아웃과 차별화된 프리미엄 구역에 대한 수요가 모두 증가하고 있으며, LATAM은 협폭기 기단에서 프리미엄 이코노미를 제공합니다. 이로 인해 신규 인도 기체 및 개조 프로그램을 통해 좌석, 머리 위 수납공간, 객실 비품, 연결 기기 및 기타 인테리어 시스템에 대한 지속적인 수요가 발생하고 있습니다.
본 조사에서 채택한 시장 세분화에 따르면, 리저널 제트는 2026년부터 2031년에 걸쳐 연평균 성장률(CAGR) 5.65%를 기록하며 가장 빠른 성장세를 보일 것으로 예측됩니다. 남미 지역의 E195-E2 수주 파이프라인 확대가 이러한 전망을 뒷받침하고 있습니다. LATAM은 2025년 9월, E195-E2 기종 24대를 확정 발주하고 50대에 대한 구매 옵션을 부여했습니다. 한편, Abra Group은 2026년 7월 E195-E2 기종 20대 확보에 합의했으며, 10대의 옵션 및 15대의 구매권을 보유하고 있어 잠재적 수요는 45대에 달할 전망입니다. 와이드바디 기종은 시설이 잘 갖춰진 장거리 노선을 위한 객실 구성에서 여전히 중요한 역할을 하고 있는 반면, 터보프롭 기종은 2차 지역 시장이나 외딴 지역 시장에서 계속해서 활약하고 있습니다. 따라서 기종에 관계없이 수요는 협폭기 도입 대수의 규모와 소형 E2 기종의 수주 파이프라인 확대가 맞물려 형성되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사의 전제조건과 시장의 정의
- 조사 범위
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 밸류체인 분석
- 규제 상황
- 기술 전망
- Porter의 Five Forces 분석
제5장 시장 규모와 성장 예측
- 제품 유형별
- 항공기 유형별
- 객실 클래스별
- 피트 유형별
- 소재별
- 지역별
- 브라질
- 아르헨티나
- 칠레
- 콜롬비아
- 페루
- 에콰도르
- 기타 남미 국가
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- Safran SA
- Panasonic Avionics Corporation
- Collins Aerospace(RTX Corporation)
- Diehl Stiftung & Co. KG
- RECARO Aircraft Seating GmbH & Co. KG(RECARO Holding GmbH)
- Thales Group
- Thompson Aero Seating Limited(Aviation Industry Corporation of China)
- JAMCO Corporation
- Geven S.p.A.
- Singapore Technologies Engineering Ltd.
- FACC AG
- MRO Holdings Inc.
- Astronics Corporation
제7장 시장 기회와 향후 전망
LSH 26.10.29According to Mordor Intelligence, the South America commercial aircraft cabin interior market size was valued at USD 456.97 million in 2025, and is projected to grow from USD 475.30 million in 2026 to USD 600.91 million by 2031, at a 4.80% CAGR during the forecast period (2026-2031).
South America Commercial Aircraft Cabin Interior Market Trends and Insights
Post-Pandemic Passenger Traffic Recovery
South America's commercial aviation sector continued to expand in 2025, supporting opportunities for cabin interior suppliers. Argentina recorded 33.3 million passengers, up 13.2% year on year, with domestic traffic increasing 9.1% and international traffic rising 18.2%. Airlines are also investing in cabin equipment alongside fleet development. In April 2025, Azul selected RECARO CL6710 Business Class and CL3710 Economy Class seats for its new Airbus A330 aircraft, with deliveries scheduled to begin in 2025. These developments expand the installed base of cabin equipment and support ongoing requirements for seating, replacement components, maintenance, and interior upgrades across South America.
Embraer-Led Regional Fleet Renewal
Brazil-based Embraer delivered 78 commercial aircraft in 2025, up approximately 6.8% from 2024, while its commercial aviation backlog reached USD 14.5 billion at year-end. The company continues to target 80-85 commercial aircraft deliveries in 2026. In July 2026, Abra Group, parent of South American carriers Avianca and GOL, agreed to acquire 20 E195-E2 aircraft, with 10 purchase options and 15 purchase rights, bringing the potential total to 45 aircraft. First deliveries are expected in Q4 2027. The E195-E2 platform includes cabin elements such as seating, overhead storage, galleys, and lavatories, with connectivity configurable to airline requirements. This agreement represents a potential source of future demand for cabin interiors in South America.
High Certification and Airworthiness Compliance Costs
Commercial aircraft cabin modifications in South America must comply with national airworthiness and maintenance requirements. Brazil's ANAC, Chile's DGAC, Colombia's Aerocivil, and Argentina's ANAC oversee certification and maintenance frameworks within their respective markets. Major modifications may require approved design data or supplemental type certification, while appropriately approved organizations must perform maintenance and alterations. These requirements increase the technical documentation, engineering, inspection, and coordination involved in cabin retrofit programs. The need for certified designs, approved components, and qualified maintenance capability can add cost and complexity to interior modifications and affect project schedules across the market.
Other drivers and restraints analyzed in the detailed report include:
- Airline Cabin Retrofit and Premiumization
- Rising Demand for Connected Passenger Experiences
- Import Dependence and Supply-Chain Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Seating accounted for an estimated 30.45% of the South America commercial aircraft cabin interior market in 2025. The region's large narrowbody fleet supports demand and includes both retrofit activity and installations on new aircraft. Premium cabin programs increase interior content on selected long-haul aircraft, while economy-class installations continue to generate higher seat volumes. In August 2025, RECARO announced a 41-shipset PL3530 Premium Comfort retrofit program for LATAM's B787-8 and B787-9 aircraft, with deliveries beginning in the first half of 2027. The program demonstrates continued investment in differentiated seating alongside standard economy-class requirements.
IFEC is forecast to be the fastest-growing product category, with an estimated CAGR of 6.25% from 2026 to 2031. In July 2026, SES was selected to equip more than 60 LATAM A320neo, A321XLR, and E195-E2 aircraft with multi-orbit connectivity over the coming years. LATAM already operates more than 250 SES-connected aircraft. The program supports demand for electronically steered antennas, in-cabin network integration, software, installation, and maintenance support. Galleys, monuments, overhead bins, lighting, and interior panels remain relevant line-fit and retrofit categories, broadening cabin equipment opportunities as airlines combine conventional interior upgrades with connected passenger-experience systems.
Narrowbody aircraft accounted for an estimated 68.50% of the South America commercial aircraft cabin interior market in 2025. This share reflects the large installed base operating across domestic and regional networks. LATAM alone ended 2025 with 291 Airbus narrowbody passenger aircraft, compared with 60 widebody aircraft. Varying operating models drive demand for both higher-density layouts and differentiated premium sections, with LATAM offering Premium Economy on its narrowbody fleet. This generates recurring requirements for seating, overhead storage, cabin monuments, connectivity equipment, and other interior systems across new deliveries and retrofit programs.
Regional jets are forecast to record the fastest growth, at an estimated 5.65% CAGR from 2026 to 2031, based on the market segmentation used in this study. A growing E195-E2 order pipeline in South America supports this outlook. LATAM ordered 24 firm E195-E2 aircraft with 50 purchase options in September 2025, while Abra Group agreed in July 2026 to acquire 20 E195-E2 aircraft with 10 options and 15 purchase rights, bringing its potential requirement to 45 aircraft. Widebody aircraft remain relevant for higher-content long-haul cabin configurations, while turboprops continue to serve secondary and remote regional markets. Demand across aircraft types, therefore, combines the scale of the narrowbody installed base with a growing pipeline of smaller-capacity E2 aircraft.
Complete Report Scope:
- By Product Type
- Seating
- Cabin Lighting
- In-flight Entertainment and Connectivity (IFEC)
- Galley and Monument
- Lavatory Systems
- Cabin Windows and Windshields
- Overhead Stowage Bins
- Interior Panels and Floorboards
- Others (Water and Waste Management Systems, Air Ionization and Purification System, Oxygen Systems, etc.)
- By Aircraft Type
- Narrowbody Aircraft
- Widebody Aircraft
- Regional Jets
- Turboprop Aircraft
- By Cabin Class
- First Class and Business Class
- Premium Economy Class
- Economy Class
- By Fit Type
- Original Equipment Manufacturer (OEM)
- Aftermarket
- By Material
- Composites
- Aluminum Alloys
- Steel and Other Alloys
- Advanced Thermoplastics
- By Geography
- Brazil
- Argentina
- Chile
- Colombia
- Peru
- Ecuador
- Rest of South America
List of Companies Covered in this Report:
- Safran SA
- Panasonic Avionics Corporation
- Collins Aerospace (RTX Corporation)
- Diehl Stiftung & Co. KG
- RECARO Aircraft Seating GmbH & Co. KG (RECARO Holding GmbH)
- Thales Group
- Thompson Aero Seating Limited (Aviation Industry Corporation of China)
- JAMCO Corporation
- Geven S.p.A.
- Singapore Technologies Engineering Ltd.
- FACC AG
- MRO Holdings Inc.
- Astronics Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Post-pandemic passenger traffic recovery
- 4.2.2 Embraer-led regional fleet renewal
- 4.2.3 Airline cabin retrofit and premiumization
- 4.2.4 Rising demand for connected passenger experiences
- 4.2.5 Brazilian aerospace and MRO capability expansion
- 4.2.6 Cabin localization for dense and thin South American routes
- 4.3 Market Restraints
- 4.3.1 High certification and airworthiness compliance costs
- 4.3.2 Foreign-exchange exposure in airline procurement
- 4.3.3 Import dependence and supply-chain volatility
- 4.3.4 Limited regional availability of certified cabin-interior capacity
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Seating
- 5.1.2 Cabin Lighting
- 5.1.3 In-flight Entertainment and Connectivity (IFEC)
- 5.1.4 Galley and Monument
- 5.1.5 Lavatory Systems
- 5.1.6 Cabin Windows and Windshields
- 5.1.7 Overhead Stowage Bins
- 5.1.8 Interior Panels and Floorboards
- 5.1.9 Others (Water and Waste Management Systems, Air Ionization and Purification System, Oxygen Systems, etc.)
- 5.2 By Aircraft Type
- 5.2.1 Narrowbody Aircraft
- 5.2.2 Widebody Aircraft
- 5.2.3 Regional Jets
- 5.2.4 Turboprop Aircraft
- 5.3 By Cabin Class
- 5.3.1 First Class and Business Class
- 5.3.2 Premium Economy Class
- 5.3.3 Economy Class
- 5.4 By Fit Type
- 5.4.1 Original Equipment Manufacturer (OEM)
- 5.4.2 Aftermarket
- 5.5 By Material
- 5.5.1 Composites
- 5.5.2 Aluminum Alloys
- 5.5.3 Steel and Other Alloys
- 5.5.4 Advanced Thermoplastics
- 5.6 By Geography
- 5.6.1 Brazil
- 5.6.2 Argentina
- 5.6.3 Chile
- 5.6.4 Colombia
- 5.6.5 Peru
- 5.6.6 Ecuador
- 5.6.7 Rest of South America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 Safran SA
- 6.4.2 Panasonic Avionics Corporation
- 6.4.3 Collins Aerospace (RTX Corporation)
- 6.4.4 Diehl Stiftung & Co. KG
- 6.4.5 RECARO Aircraft Seating GmbH & Co. KG (RECARO Holding GmbH)
- 6.4.6 Thales Group
- 6.4.7 Thompson Aero Seating Limited (Aviation Industry Corporation of China)
- 6.4.8 JAMCO Corporation
- 6.4.9 Geven S.p.A.
- 6.4.10 Singapore Technologies Engineering Ltd.
- 6.4.11 FACC AG
- 6.4.12 MRO Holdings Inc.
- 6.4.13 Astronics Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


