

|
시장보고서
상품코드
2155616
일회용 EEG 전극 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Disposable EEG Electrode - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
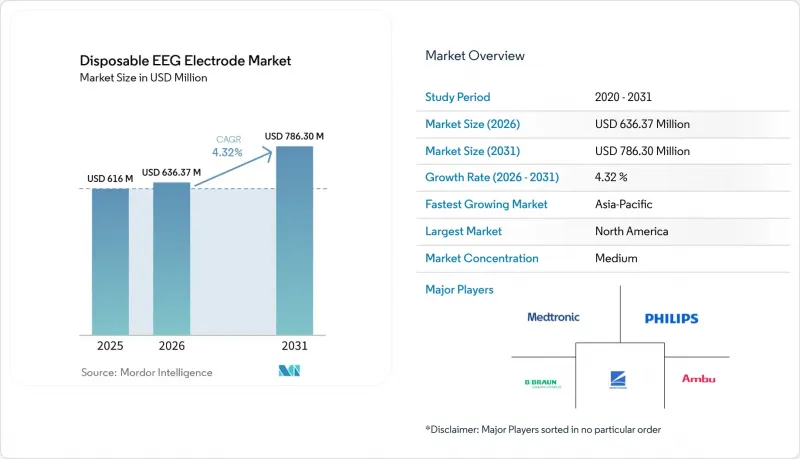
에 따르면 일회용 EEG 전극 시장 규모는 2025년에 6억 1,600만 달러로 평가되며, 2026년 6억 3,637만 달러에서 2031년까지 7억 8,630만 달러에 달할 것으로 예측되며, 예측 기간(2026-2031년) 동안 CAGR은 4.32%가 될 전망입니다.
세계 일회용 EEG 전극 시장의 동향 및 인사이트
감염 예방을 위한 일회용 전극의 도입
병원의 감염 관리 방침은 일회용 EEG 전극 시장의 견고한 수요 기반을 마련하고 있습니다. 유럽연합(EU)의 의료기기 규정(MDR)은 제17조에 따라 일회용 의료기기의 재처리를 제한하고 있으며, 회원국에서는 계속해서 국내 규정에 따라 이행 지침이 마련되고 있습니다. 이러한 요건으로 인해 구매 결정은 임상의의 선호도를 넘어섰으며, 문서화된 위생 관리 프로세스가 더욱 중요시되고 있습니다. 호주·뉴질랜드 감염 예방 및 관리 대학(ACIPC)은 감염 예방 실무에서 일회용 의료기기의 사용에 대해 언급한 2025년 견해를 발표했습니다. 이러한 환경은 급성기 및 준중증 치료 워크플로우에서 환자별 전용 전극 키트의 도입을 촉진하고 있습니다. 또한 일회용 EEG 전극 시장에서는 공급업체에 의한 표준화된 포장, 추적성 및 폐기 절차가 요구되고 있습니다.
신경 질환 및 수면 장애 모니터링 수요 증가
신경 질환에 대한 치료 수요가 증가함에 따라 일회용 EEG 전극 시장의 잠재적 모니터링 대상층이 확대되고 있습니다. 세계보건기구(WHO)는 2025년, 신경 질환이 30억 명 이상에게 영향을 미치며 매년 1,100만 명 이상의 사망 원인이 되고 있다고 보고했습니다. 또한 WHO는 회원국 중 신경 질환에 관한 국가 정책을 수립한 곳이 불과 32%에 불과하며, 보편적 의료 보장(UHC) 혜택 패키지에 신경 질환 관련 서비스를 포함시킨 곳은 25%에 그친다고 보고했습니다. 이러한 격차는 현재의 의료 접근성을 제한하는 한편, 각국이 ‘간질 및 기타 신경계 질환에 관한 부문 간 세계 행동 계획 2022-2031’의 달성을 위해 노력하는 가운데, 진단 역량 확충이 필요해지고 있습니다. 세계보건기구(WHO)에 따르면, 약 5,000만 명이 간질을 앓고 있으며, 그 중 80% 가까이가 저·중소득 국가에 거주하고 있습니다. 일회용 EEG 전극 시장은 신뢰할 수 있는 소모품을 통해 수면 검사, 발작 모니터링 및 외래 신경학적 평가를 지원할 수 있습니다.
재사용 가능한 전극에 비해 1회당 비용이 높은 점
가격에 민감한 환경에서 1회당 구매 비용이 명확하게 인식되는 것은 일회용 EEG 전극 시장에 여전히 장벽으로 작용하고 있습니다. 신경학적 모니터링을 대량으로 수행하는 병원이나 진단 센터에서는 매일 진행되는 검사를 통해 이 비용이 누적될 가능성이 있습니다. 이 문제는 신흥 시장에서 특히 심각하며, 그곳에서는 재사용 가능한 시스템의 초기 조달 비용이 낮고 현지 대체품이 더 저렴한 경우가 있습니다. 이로 인해 감염 관리나 업무 효율을 우선시하는 기관과 주로 조달 가격에 중점을 두는 기관 간에 도입 조건에 차이가 발생합니다. 세트 판매 방식의 EEG 키트나 구독형 공급 프로그램은 발주 절차를 간소화할 수 있지만, 이러한 방식의 이용은 북미와 서유럽에서 더 보편화되어 있습니다. 일회용 EEG 전극 시장에서는 예산 제약이 있는 대량 사용 시설에서 명확한 워크플로우상의 이점과 예측 가능한 공급 조건이 요구되고 있습니다.
부문 분석
2025년, 일회용 EEG 전극 시장에서 습식 EEG 전극은 57.8%의 점유율을 차지했습니다. 이 점유율은 훈련을 받은 기술자가 전도성 젤을 도포할 수 있는 병원 검사실이나 입원 환자 모니터링 유닛에서의 확고한 사용 현황을 반영하고 있습니다. 습식 전극은 관리된 임상 워크플로우에서 계속해서 신호 품질의 기준이 되고 있습니다. 젤이 미리 도포된 제품은 EEG 담당자에게 익숙한 작동 원리를 유지하면서 설정 과정을 개선합니다. 바늘 전극은 두피 접근이 제한되는 수술 중 용도로 사용됩니다. 패치형 및 접착형 전극은 기존의 컵형 전극을 부착하기 어려운 신생아 및 소아 모니터링에 유용합니다. 일회용 캡, 헤드밴드 및 부속품은 연구, 급성기 의료 및 전문 모니터링 분야의 보다 제한적인 요구 사항을 충족합니다.
드라이 EEG 전극은 2031년까지 연평균 성장률(CAGR) 5.3%를 기록할 것으로 예상되며, 가장 빠르게 성장하는 제품 카테고리가 될 것입니다. 이러한 성장은 재택 모니터링, 간질 외래 평가, 자가 부착이 필요한 뇌-컴퓨터 인터페이스(BCI)와 같은 사용 사례와의 호환성을 반영합니다. 2025년 연구에 따르면, PEDOT:PSS/PVA 코팅이 적용된 천 소재 드라이 전극은 10회의 세탁 주기를 거친 후에도 Ag/AgCl 습식 전극에 필적하는 접촉 임피던스와 EEG 신호 품질을 달성한 것으로 보고되었습니다. 이러한 연구 결과는 건식 웨어러블 방식의 기술적 방향성을 뒷받침하지만, 임상 현장에서의 도입은 여전히 검증과 규제 당국의 승인에 달려 있습니다. 복잡한 진단을 수행하는 검사실에서 습식 시스템이 널리 대체되기 전에, 가정에서의 사용이 보급될 가능성이 높다고 생각됩니다. 일회용 뇌파(EEG) 전극 시장은 기술자의 개입 없이 환자가 직접 사용할 수 있도록 밀착성, 사용 설명 및 착용 편의성을 개선한 제품 덕분에 성장할 가능성이 있습니다.
2025년에는 은/염화은 전극이 시장 점유율의 68.3%를 차지했습니다. 오랜 임상 실적, 생체적합성, 그리고 제조 규모 확대가 가능하다는 점으로 미루어 볼 때, 확립된 뇌파(EEG) 절차에서 계속해서 사용될 것으로 예상됩니다. 젤을 사용한 Ag/AgCl 시스템은 임상의들에게 친숙하며, 신호 성능의 기준으로 사용되고 있습니다. 금 전극은 재료 특성이나 장기 사용이 중요한 특정 연구 용도나 고급 용도에 사용되고 있습니다. 스테인리스강 전극은 일부 수술 중 처치를 포함한 특수한 환경에 대응하고 있습니다. 탄소계 소재는 전기적 성능과 기계적 유연성을 겸비하고 있어 웨어러블 전극으로의 활용이 검토되고 있습니다. 이러한 소재 선택지를 통해 공급업체는 임상, 연구 및 휴대용 모니터링 요구 사항에 맞춰 제품을 맞춤화할 수 있게 됩니다.
전도성 고분자 소재는 2031년까지 연평균 성장률(CAGR) 5.2%로 성장할 것으로 예측됩니다. PEDOT:PSS를 기반으로 한 설계는 신축성, 젤이 필요 없는 작동, 그리고 섬유와의 통합을 실현할 수 있습니다. 이러한 특징 덕분에 기존의 금속 박 설계로는 구현하기 어려웠던 전극 형상이 가능해집니다. 2025년에 수행된 MXene/PEDOT:PSS 표피용 건식 전극에 관한 연구에서는 생리 신호 모니터링에서 높은 전도성과 변형 영향에 영향을 받지 않는 성능이 보고되었습니다. 따라서 고분자 재료 개발의 방향성은 웨어러블 모니터링 및 장시간 사용 시의 착용감과 밀접하게 관련되어 있습니다. 이러한 소재가 임상 현장에서 널리 사용되기 위해서는 공급업체가 여전히 생체적합성 증거와 적절한 규제 관련 문서를 제시해야 합니다. 일회용 EEG 전극 시장에서는 폴리머 기술이 차별화된 용도로 확대되는 한편, Ag/AgCl이 임상 분야의 기반으로 유지될 가능성이 있습니다.
2025년, 컵형 전극은 전 세계 일회용 EEG 전극 매출의 33.4%를 차지했습니다. 이 전극의 사용은 표준 임상 기록 몽타주에서 사용되는 국제적인 10-20법 EEG 배치 시스템과 밀접한 관련이 있습니다. 이러한 관계로 인해 신경과 부문에서의 수요는 계속해서 예상됩니다. 이는 대체 형태의 전극이 확립된 워크플로우에서 임상적 동등성을 입증해야 하기 때문입니다. 바늘 전극은 일반적인 두피 배치에 적합하지 않은 수술 중 환경에 대응합니다. 패치 전극과 디스크 전극은 신생아, 외래 환자 및 집중 모니터링 용도를 위해 다양한 부착 방법을 제공합니다. 이러한 형태의 다양성은 전극 설계를 환자의 상태, 기록 기간 및 치료 환경에 맞춰야 할 필요성을 반영합니다. 또한, 이로 인해 특정 하나의 설계가 다른 모든 범주를 대체할 가능성도 낮아집니다.
전극 어레이 시장은 2031년까지 연평균 성장률(CAGR) 5.1%로 확대될 것으로 예측됩니다. 신경 중환자 치료, 수술 중 모니터링, 재활, 그리고 뇌-컴퓨터 인터페이스(BCI) 응용 분야에서 고밀도 기록에 대한 수요가 이러한 성장을 뒷받침하고 있습니다. Ceribell사는 중환자 치료 환경에서 신속한 착용을 목적으로 설계된 10전극 헤드밴드 어레이를 채택하고 있습니다. 이 어레이를 사용하면 여러 부위에서의 기록 기능을 유지하면서 개별 전극을 부착하는 데 필요한 시간을 단축할 수 있습니다. 헤드밴드, 캡, 네트는 자가 착용이 중요한 연구 개발 용도나 일반 소비자를 대상으로 한 뇌-컴퓨터 인터페이스(BCI) 애플리케이션에도 적합합니다. 2025년 REVE 기본 모델은 92개의 데이터셋과 2만 5,000명의 피험자로부터 얻은 60,000시간의 EEG 데이터를 사용하여 학습되었으며, 모델 개발 과정에서 다양한 전극 배치를 지원할 수 있음이 입증되었습니다. 이러한 접근 방식은 유연한 배치를 가능하게 하지만, 임상 사용자에게는 여전히 검증된 치료 프로토콜에 부합하는 형식이 필요합니다.
지역별 분석
2025년, 북미는 전 세계 일회용 뇌파(EEG) 전극 매출의 42.7%를 차지했습니다. 이 지역은 병원 내 확고한 사용 실적, FDA 승인 활동, 그리고 일회용 소모품을 지원하는 공동 구매 계약의 혜택을 받고 있습니다. 미국은 간질 모니터링 기기의 집중과 보다 광범위한 급성기 의료 인프라를 배경으로 이 지역의 수요를 주도하고 있습니다. Natus사는 2025년 12월, BrainWatch의 ‘간질 중첩 상태’ 적응증에 대해 FDA 510(k) 승인을 획득하여 급성기 의료 현장에서의 현장 진단용 EEG 활용을 촉진했습니다. 또한 이 회사는 해당 솔루션이 메디케어의 ‘신기술 추가 지급(New Technology Add-on Payment)’ 대상이 되어, 대상 환자 1인당 최대 913.9달러의 추가 지급을 받을 수 있다고 보고했습니다. 캐나다와 멕시코는 규모는 작지만 수요가 확대되고 있는 시장입니다. 코버넌트 헬스(Covenant Health)는 일회용 의료기기 기준을 규정한 2025년 정책을 발표했으며, 이는 캐나다 의료 현장에서 감염 예방에 중점을 두고 있음을 보여줍니다.
유럽은 일회용 뇌파 전극 시장에서 2위를 차지하는 지역 시장입니다. 독일, 프랑스, 영국, 이탈리아, 스페인이 주요 수요 거점입니다. 독일은 고령화가 진행되고 있으며, 뇌졸중, 치매, 파킨슨병의 발병률이 연령이 증가함에 따라 높아지기 때문에 신경학적 모니터링에 대한 수요가 증가하고 있습니다. EU 의료기기 규정의 요건은 지역 전체에서 일회용 의료기기의 취급에 관한 견고한 규정 준수 체계를 확립하고 있습니다. 이 체계에 따라 재사용 가능한 전극이 사용되는 상황에서 검증된 취급 및 재처리 운영의 중요성이 커지고 있습니다. 프랑스에서는 신경 질환에 대한 인식 제고와 의료 투자 증가에 따라 성장에 유리한 여건이 조성되어 있습니다. 지역 공급업체는 규정 준수 관련 문서, 환자별 포장, MRI 호환 제품 요건을 충족함으로써 타사와의 차별화를 꾀할 수 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 5.8%로 성장할 것으로 예측되며, 이는 일회용 EEG 전극 시장에서 가장 높은 지역 성장률입니다. 중국은 국내 의료 시설 및 수출 시장을 위한 국내 생산을 통해 지역 판매량 증가를 뒷받침하고 있습니다. 일본에서는 AI를 통합한 진단 시스템에 대한 집중 투자가 고령화 사회에서 신속한 신경학적 평가에 대한 수요를 뒷받침하고 있습니다. 인도와 한국은 각각 진단 인프라에 대한 투자와 첨단 병원 기술 도입을 통해 성장 잠재력을 지니고 있습니다. 소규모 병원 및 일부 동남아시아 시장에서는 일회용 제품이 저가의 재사용 가능한 대체품과 경쟁하고 있어, 가격 민감도가 여전히 제약요인으로 작용하고 있습니다. 중동 및 아프리카 및 남미의 시장 점유율은 비교적 작으며, GCC 국가, 남아프리카공화국, 브라질, 아르헨티나가 주요 수요 거점입니다. 브라질과 아르헨티나의 민간 병원 네트워크는 고급 일회용 전극 형태의 주요 도입처로 자리 잡고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
- 조사 가정과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 공급망 분석
- 규제 상황
- 기술 전망
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 제품 유형별 세분화
- 소재별 세분화
- 폼팩터별 세분화
- 채널 구성별 세분화
- 용도별 세분화
- 최종사용자별 세분화
- 유통 채널별 세분화
- 지역별
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 스페인
- 기타 유럽 국가
- 아시아태평양
- 중국
- 일본
- 인도
- 한국
- 호주
- 기타 아시아태평양 국가
- 중동 및 아프리카
- GCC
- 남아프리카공화국
- 기타 중동 및 아프리카 국가
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 북미
제6장 경쟁 구도
- 시장 집중도
- 시장 점유율 분석
- 기업 개요
- Natus Medical Incorporated
- Ambu A/S
- NIHON KOHDEN CORPORATION
- Medtronic plc
- Rhythmlink International, LLC
- Cadwell Industries, Inc.
- Koninklijke Philips N.V.
- CONMED Corporation
- Compumedics Limited
- Brain Products GmbH
- BIOPAC Systems, Inc.
- Ceribell, Inc.
- Brain Scientific Inc.
- NeuroWave Systems Inc.
- Micromed S.p.A.
- Neurosoft
- Bittium Biosignals Ltd
- Dymedix Diagnostics
- SPES MEDICA S.r.l.
- B. Braun Melsungen AG
제7장 시장 기회와 향후 전망
KSM 26.10.30According to Mordor Intelligence, the disposable EEG electrode market size was valued at USD 616 million in 2025 and is estimated to grow from USD 636.37 million in 2026 to reach USD 786.30 million by 2031, at a CAGR of 4.32% during the forecast period (2026-2031).
Global Disposable EEG Electrode Market Trends and Insights
Infection-Control Adoption of Single-Use Electrodes
Hospital infection-control policies are establishing a durable basis for demand in the Disposable EEG Electrode Market. The European Union Medical Devices Regulation restricts the reprocessing of single-use devices under Article 17, and national rules continue to guide implementation across member states. These requirements move purchasing decisions beyond clinician preference and place more weight on documented hygiene processes. The Australasian College for Infection Prevention and Control issued a 2025 position statement that addresses the use of single-use devices in infection-prevention practice. This environment supports patient-specific electrode kits in acute and semi-critical care workflows. The Disposable EEG Electrode Market also requires standardized pouching, traceability, and disposal instructions from suppliers.
Rising Neurological and Sleep-Disorder Monitoring Demand
Neurological care needs are expanding the potential monitoring pool for the Disposable EEG Electrode Market. The World Health Organization reported in 2025 that neurological conditions affect more than 3 billion people and account for more than 11 million deaths each year. The organization also reported that only 32% of member states had a national neurological policy, and only 25% included neurological services in universal health coverage benefit packages. These gaps limit access today, but they also create a need for wider diagnostic capacity as countries work toward the Intersectoral Global Action Plan on Epilepsy and Other Neurological Disorders 2022-2031. The World Health Organization states that around 50 million people live with epilepsy, with nearly 80% living in low- and middle-income countries. The Disposable EEG Electrode Market can support sleep studies, seizure monitoring, and outpatient neurological assessment with dependable consumables.
Higher Per-Procedure Cost Versus Reusable Electrodes
A visible per-procedure purchase cost remains a barrier for the Disposable EEG Electrode Market in price-sensitive settings. Hospitals and diagnostic centers that perform large volumes of neurological monitoring can see this cost accumulate across daily procedures. The issue is most acute in emerging markets, where reusable systems may have lower upfront supply costs and local alternatives can be less expensive. This creates different adoption conditions between facilities that prioritize infection control and labor efficiency and those focused mainly on procurement price. Bundled EEG kits and subscription-based supply programs can reduce ordering complexity, but their availability remains more established in North America and Western Europe. The Disposable EEG Electrode Market requires a clear workflow benefit and predictable supply terms in high-volume facilities with constrained budgets.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Point-of-Care and Ambulatory EEG
- Disposable Electrode Integration With AI-Enabled EEG Workflows
- Regulatory and Clinical Validation Complexity
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Wet EEG electrodes accounted for 57.8% of the Disposable EEG Electrode Market share in 2025. Their position reflects established use in hospital laboratories and inpatient monitoring units, where trained technicians can apply conductive gel. Wet electrodes continue to set the signal-quality benchmark in controlled clinical workflows. Pre-gelled products improve the setup process while preserving the operating principles familiar to EEG staff. Needle electrodes serve intraoperative applications where scalp access is restricted. Patch and adhesive electrodes are useful for neonatal and pediatric monitoring where conventional cup placement may be impractical. Disposable caps, headbands, and accessories serve narrower requirements across research, acute care, and specialized monitoring.
Dry EEG electrodes are projected to record a 5.3% CAGR through 2031, making them the fastest-growing product category. Their growth reflects compatibility with home monitoring, ambulatory epilepsy assessment, and brain-computer interface use cases that require self-application. A 2025 study reported that a PEDOT:PSS/PVA-coated fabric dry electrode achieved contact impedance and EEG signal quality comparable to Ag/AgCl wet electrodes after 10 washing cycles . This evidence supports the technical direction of dry wearable formats, but clinical adoption still depends on validation and regulatory clearance. Home use is likely to develop before widespread replacement of wet systems in complex diagnostic laboratories. The Disposable EEG Electrode Market can benefit from products that improve adhesion, instructions, and comfort for patients without a technician.
Silver/silver chloride electrodes held 68.3% of market share in 2025. Their long clinical history, biocompatibility profile, and available manufacturing scale support continued use across established EEG procedures. Gel-assisted Ag/AgCl systems remain familiar to clinicians and are used as a reference point for signal performance. Gold electrodes serve select research and premium applications where material characteristics and longer-term use matter. Stainless steel electrodes address specialized settings, including some intraoperative procedures. Carbon-based materials are being examined for wearable electrodes because they can combine electrical performance with mechanical flexibility. These material choices give suppliers a way to tailor products to clinical, research, and portable monitoring requirements.
Conductive polymer materials are forecast to grow at a 5.2% CAGR through 2031. PEDOT:PSS-based designs can support stretchability, gel-free operation, and integration with textiles. These features enable electrode formats that are harder to create with conventional metal-foil designs. A 2025 study of MXene/PEDOT:PSS epidermal dry electrodes reported high conductivity and strain-insensitive performance for physiological signal monitoring. The development path for polymer materials is therefore tied to wearable monitoring and extended-use comfort. Suppliers still need biocompatibility evidence and suitable regulatory documentation before these materials can enter broad clinical use. The Disposable EEG Electrode Market can retain Ag/AgCl as its clinical base while polymer technologies expand into differentiated applications.
Cup electrodes held 33.4% of global disposable EEG electrode sales in 2025. Their use is closely linked to the international 10-20 EEG placement system used in standard clinical recording montages. This relationship supports continued demand in neurology departments because alternative forms must demonstrate clinical equivalence in established workflows. Needle electrodes address intraoperative settings where ordinary scalp placement is not suitable. Patch and disk electrodes offer different attachment methods for neonatal, ambulatory, and focused monitoring applications. The diversity of form factors reflects the need to match electrode design to patient condition, recording duration, and care setting. It also reduces the likelihood that one design will displace every other category.
Electrode arrays are forecast to expand at a 5.1% CAGR through 2031. High-density recording needs in neurocritical care, intraoperative monitoring, rehabilitation, and brain-computer interface applications support this growth. Ceribell uses a 10-electrode headband array designed for rapid placement in critical care settings. Arrays reduce the time needed to place individual electrodes while preserving multi-site recording capability. Headbands, caps, and nets also fit research and consumer-facing brain-computer interface applications where self-application is important. The 2025 REVE foundation model was trained on 60,000 hours of EEG data from 92 datasets and 25,000 subjects, showing support for varied electrode layouts in model development. This work supports flexible layouts, although clinical users still need formats that fit validated care protocols.
Complete Report Scope:
- Segmentation by Product Type
- Wet EEG Electrodes
- Dry EEG Electrodes
- Needle EEG Electrodes
- Patch and Adhesive EEG Electrodes
- Disposable EEG Caps and Headbands
- Electrode Accessories
- Segmentation by Material Type
- Silver/Silver Chloride
- Gold
- Stainless Steel
- Conductive Polymer
- Carbon-Based and Other Materials
- Segmentation by Form Factor
- Cup Electrodes
- Needle Electrodes
- Patch Electrodes
- Disk Electrodes
- Headbands, Caps and Nets
- Electrode Arrays
- Segmentation by Channel Configuration
- Single-Channel Electrodes
- Multi-Channel Electrode Arrays
- Segmentation by Application
- Clinical Diagnostics
- Sleep Studies
- Neurocritical Care
- Intraoperative Monitoring
- Brain-Computer Interface Applications
- Others
- Segmentation by End User
- Hospitals and Neurology Clinics
- Diagnostic and Sleep Centers
- Ambulatory Surgical and Outpatient Centers
- Academic and Research Institutes
- Pharmaceutical and Contract Research Organizations
- Home Healthcare and Remote Monitoring Providers
- Segmentation by Distribution Channel
- Direct Sales
- Medical Device Distributors
- Hospital Group Purchasing Organizations
- Online and Manufacturer Stores
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 42.7% of global disposable EEG electrode sales in 2025. The region benefits from established hospital utilization, FDA clearance activity, and group purchasing arrangements that support disposable consumables. The United States is the primary source of regional demand because of its concentration of epilepsy monitoring units and broader acute-care infrastructure. Natus received FDA 510(k) clearance in December 2025 for a BrainWatch electrographic status epilepticus indication, supporting point-of-care EEG use in acute-care settings. The company also reported Medicare New Technology Add-on Payment eligibility with a maximum incremental payment of USD 913.9 per eligible patient for the solution. Canada and Mexico represent smaller but developing demand centers. Covenant Health published a 2025 policy covering standards for single-use medical devices, illustrating the infection-prevention focus in Canadian health care.
Europe is the second-largest regional market for the Disposable EEG Electrode Market. Germany, France, the United Kingdom, Italy, and Spain are the principal demand centers. Germany's aging population supports neurological monitoring needs because the frequency of stroke, dementia, and Parkinson's disease rises with age. EU Medical Devices Regulation requirements establish a strong compliance framework for single-use device practices across the region. This framework increases the operational importance of validated handling and reprocessing where reusable electrodes are used. France has favorable conditions for growth as awareness of neurological disorders and health care investment increase. Regional suppliers can differentiate by addressing compliance documentation, patient-specific packaging, and MRI-conditional product requirements.
Asia-Pacific is forecast to grow at a 5.8% CAGR through 2031, the fastest regional rate in the Disposable EEG Electrode Market. China supports regional volume growth through domestic production for local health care facilities and export markets. Japan's focus on AI-integrated diagnostic systems supports demand for rapid neurological assessment in an aging population. India and South Korea offer growth potential through diagnostic infrastructure investment and advanced hospital technology adoption, respectively. Price sensitivity in lower-tier hospitals and some Southeast Asian markets remains a constraint because disposable products compete with lower-cost reusable alternatives. The Middle East and Africa and South America contribute smaller shares, with GCC countries, South Africa, Brazil, and Argentina providing key demand centers. Private hospital networks in Brazil and Argentina are important adopters of premium single-use electrode formats.
- Natus Medical
- Ambu
- Nihon Kohden
- Medtronic
- Rhythmlink International, LLC
- Cadwell
- Koninklijke Philips
- Conmed
- Compumedics
- Brain Products GmbH
- BIOPAC Systems, Inc.
- Ceribell, Inc.
- Brain Scientific Inc.
- NeuroWave Systems
- Micromed S.p.A.
- Neurosoft
- Bittium Biosignals Ltd
- Dymedix Diagnostics
- SPES MEDICA S.r.l.
- B. Braun
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Infection-Control Adoption of Single-Use Electrodes
- 4.2.2 Rising Neurological and Sleep-Disorder Monitoring Demand
- 4.2.3 Expansion of Point-of-Care and Ambulatory EEG
- 4.2.4 Faster Setup Through Pre-Gelled and Integrated Electrode Systems
- 4.2.5 Disposable Electrode Integration With AI-Enabled EEG Workflows
- 4.2.6 Contract-Based Procurement of Patient-Specific EEG Kits
- 4.3 Market Restraints
- 4.3.1 Higher Per-Procedure Cost Versus Reusable Electrodes
- 4.3.2 Regulatory and Clinical Validation Complexity
- 4.3.3 Electrode-Skin Impedance and Motion-Artifact Variability
- 4.3.4 Medical Waste and Silver-Containing Material Disposal Burden
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porters Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 Segmentation by Product Type
- 5.1.1 Wet EEG Electrodes
- 5.1.2 Dry EEG Electrodes
- 5.1.3 Needle EEG Electrodes
- 5.1.4 Patch and Adhesive EEG Electrodes
- 5.1.5 Disposable EEG Caps and Headbands
- 5.1.6 Electrode Accessories
- 5.2 Segmentation by Material Type
- 5.2.1 Silver/Silver Chloride
- 5.2.2 Gold
- 5.2.3 Stainless Steel
- 5.2.4 Conductive Polymer
- 5.2.5 Carbon-Based and Other Materials
- 5.3 Segmentation by Form Factor
- 5.3.1 Cup Electrodes
- 5.3.2 Needle Electrodes
- 5.3.3 Patch Electrodes
- 5.3.4 Disk Electrodes
- 5.3.5 Headbands, Caps and Nets
- 5.3.6 Electrode Arrays
- 5.4 Segmentation by Channel Configuration
- 5.4.1 Single-Channel Electrodes
- 5.4.2 Multi-Channel Electrode Arrays
- 5.5 Segmentation by Application
- 5.5.1 Clinical Diagnostics
- 5.5.2 Sleep Studies
- 5.5.3 Neurocritical Care
- 5.5.4 Intraoperative Monitoring
- 5.5.5 Brain-Computer Interface Applications
- 5.5.6 Others
- 5.6 Segmentation by End User
- 5.6.1 Hospitals and Neurology Clinics
- 5.6.2 Diagnostic and Sleep Centers
- 5.6.3 Ambulatory Surgical and Outpatient Centers
- 5.6.4 Academic and Research Institutes
- 5.6.5 Pharmaceutical and Contract Research Organizations
- 5.6.6 Home Healthcare and Remote Monitoring Providers
- 5.7 Segmentation by Distribution Channel
- 5.7.1 Direct Sales
- 5.7.2 Medical Device Distributors
- 5.7.3 Hospital Group Purchasing Organizations
- 5.7.4 Online and Manufacturer Stores
- 5.8 By Geography
- 5.8.1 North America
- 5.8.1.1 United States
- 5.8.1.2 Canada
- 5.8.1.3 Mexico
- 5.8.2 Europe
- 5.8.2.1 Germany
- 5.8.2.2 United Kingdom
- 5.8.2.3 France
- 5.8.2.4 Italy
- 5.8.2.5 Spain
- 5.8.2.6 Rest of Europe
- 5.8.3 Asia-Pacific
- 5.8.3.1 China
- 5.8.3.2 Japan
- 5.8.3.3 India
- 5.8.3.4 South Korea
- 5.8.3.5 Australia
- 5.8.3.6 Rest of Asia-Pacific
- 5.8.4 Middle East and africa
- 5.8.4.1 GCC
- 5.8.4.2 South Africa
- 5.8.4.3 Rest of Middle East and Africa
- 5.8.5 South America
- 5.8.5.1 Brazil
- 5.8.5.2 Argentina
- 5.8.5.3 Rest of South America
- 5.8.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 Natus Medical Incorporated
- 6.3.2 Ambu A/S
- 6.3.3 NIHON KOHDEN CORPORATION
- 6.3.4 Medtronic plc
- 6.3.5 Rhythmlink International, LLC
- 6.3.6 Cadwell Industries, Inc.
- 6.3.7 Koninklijke Philips N.V.
- 6.3.8 CONMED Corporation
- 6.3.9 Compumedics Limited
- 6.3.10 Brain Products GmbH
- 6.3.11 BIOPAC Systems, Inc.
- 6.3.12 Ceribell, Inc.
- 6.3.13 Brain Scientific Inc.
- 6.3.14 NeuroWave Systems Inc.
- 6.3.15 Micromed S.p.A.
- 6.3.16 Neurosoft
- 6.3.17 Bittium Biosignals Ltd
- 6.3.18 Dymedix Diagnostics
- 6.3.19 SPES MEDICA S.r.l.
- 6.3.20 B. Braun Melsungen AG
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


