

|
시장보고서
상품코드
2156901
시추액 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Drilling Fluid - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
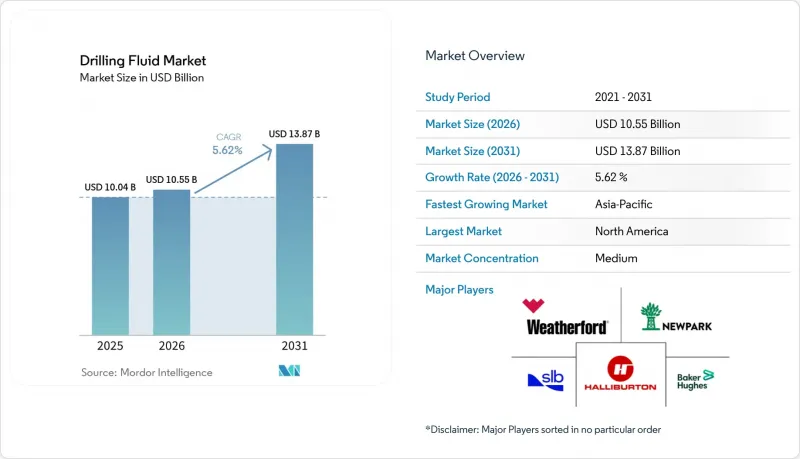
에 따르면 시추액 시장 규모는 2025년에 100억 4,000만 달러, 2026년에 105억 5,000만 달러에 달하며, 2031년까지 138억 7,000만 달러에 달할 것으로 예측되고 있으며, 2026-2031년까지 CAGR은 5.62%에 달할 전망입니다.
전 세계 시추액 시장의 동향 및 인사이트
심해 및 초심해 시추 프로젝트
심해 및 초심해 유정에서는 고성능 합성계 및 고밀도 수성 시추액가 필요하며, 이로 인해 시추액 시장에서 유정당 가장 높은 유체 비용이 발생하고 있습니다. 브라질, 가이아나, 서아프리카는 해양 공급량 증가에 기여하고 있으며, 고품질 시추 서비스에 대한 수요를 지원하고 있습니다. SLB사는 2024년 12월, 캄포스, 산토스, 에스피리투 산토 각 분지에서 페트로브라스의 심해 유정 100개 이상 건설을 지원하는 계약을 수주했습니다. 이 계약에서는 최대 9기의 초심해 시추 리그에서 시추액 및 시멘트 주입 기술이 활용됩니다. 또한 베이커 휴즈(Baker Hughes)사도 2026년, 브라질 산토스 분지에서의 통합 유정 건설 업무를 확대하여 유체, 시멘트 주입, 와이어라인, 지구과학 서비스 등을 포괄하고 있습니다. 브라질의 프레솔트층 유정은 깊이 2,000미터에 달하는 염층을 관통하는 경우가 있으며, 10,000psi를 초과하는 압력에 노출됩니다. 이러한 조건으로 인해 시추액의 밀도 및 유정 안정성에 관한 운영 범위가 좁아집니다. 또한 셰일층이나 해양 분지에서의 장거리 시추 및 복잡한 장측방 시추에도 대응하고 있습니다. 이러한 요건으로 인해 시추 1피트당 수익이 증가하며, 길고 복잡한 유정 구간에서도 시추액의 성능을 유지할 수 있는 서비스 제공업체가 유리해집니다. 시추액 시장은 사용 후 진흙물의 재이용 및 지역별 혼합 능력에 의해서도 지원되고 있으며, 이를 통해 폐기물 처리 부담을 줄이고 해양 프로젝트 인근에서의 공급 리드타임을 단축할 수 있습니다.
비전통적 셰일 및 타이트 저류층 개발
셰일층 및 타이트 저류층에서의 수평 시추는 기존의 수직 시추에 비해 유정당 시추액 사용량이 많아, 시추액 시장의 수요를 지속적으로 지원하고 있습니다. 퍼미안 분지는 여전히 이러한 수요의 중심지이지만, 원유 가격 하락과 자본 규율 강화로 인해 미국의 생산 성장세는 둔화되고 있으며, 일부 분지에서는 활동이 감소하고 있습니다. 10,000피트를 넘는 긴 수평 터널과 여러 착지 목표 지점으로 인해 퍼미안 분지의 많은 유정에서는 여전히 높은 시추액 수요가 유지되고 있습니다. 아르헨티나의 바카 무에르타(Vaca Muerta) 유전에서도 반응성이 높은 쥬라기 셰일층에 대응하기 위해 억제 작용이 있는 수성 시추액가 필요한 수평 시추 프로그램이 확대되고 있습니다. 중국 쓰촨성 및 탈림 분지의 프로젝트에서는 복잡한 다지(多枝) 유정 설계로 전환되고 있으며, 심부 및 과압 상태의 지층을 관리하기 위해 첨단 고분자계 수성 시추액가 사용되고 있습니다. 이러한 프로젝트에서는 현지 배합 능력, 기술 지원, 그리고 특수 자재에 대한 안정적인 공급 체계를 갖춘 서비스 기업이 우위를 점하고 있습니다.
원유 가격에 좌우되는 시추 예산의 변동
원유 가격의 침체는 시추액 시장에 있으며, 가장 시급한 수요 리스크로 대두되고 있습니다. 이는 예상 수익이 감소하면 운영사가 시추 장비 가동을 축소하고 시추 계획을 연기하기 때문입니다. 댈러스 연방준비은행의 2025년 3월 조사에 따르면 일부 운영사는 WTI 가격이 배럴당 50달러 아래로 떨어질 가능성에 대비해 시추를 일시 중단하고 있으며, 응답자들 중에는 가동중인 유정 수가 10개에서 5개 이하로 감소했다는 의견이 있었습니다. 베이커 휴즈(Baker Hughes)는 2026년 7월, 라틴아메리카 및 아프리카 연안에서의 성장이 유럽과 중동의 부진을 상쇄할 것으로 예상됨에 따라 2026년 전 세계 탐사·생산(E&P) 지출은 소폭 감소할 것으로 전망했습니다. 호르무즈 해협의 혼란은 지역 시설에 물류 및 인플레이션 측면에서 압박을 가했습니다. 또한 특수 폴리머와 중정석은 투입 비용을 상승시키고 조달 리스크를 초래할 가능성이 있으며, 원자재 확보 가능성도 계속해서 우려 사항으로 남아 있습니다. 압력 제어 시추는 압력을 보다 정밀하게 제어함으로써 일부 유정에서 유체 사용량을 더욱 줄일 수 있을 가능성이 있지만, 반면 신속한 대응이 가능한 유체 시스템과 모니터링의 필요성도 높아집니다.
부문별 분석
2025년에는 수성 시추액가 매출 점유율의 57.1%를 차지하며 시장을 주도했습니다. 이는 규제 당국으로부터 폭넓게 인정받고 있으며, 대규모 육상 시추에 적합하기 때문입니다. 이 범주에는 표준 벤토나이트계 시스템 외에도 고부가가치 폴리머 강화형 및 나노 첨가제가 배합된 제품이 포함됩니다. 수평 시추공 및 장거리 시추공 운영자들은 기본적인 배합으로는 제공할 수 없는 더욱 강력한 유변학 제어 및 셰일 억제를 점점 더 요구하고 있습니다. 합성계 시추액는 가장 빠르게 성장하는 유형이며, 이 부문의 시추액 시장 규모는 2031년까지 연평균 성장률(CAGR) 5.9%로 확대될 것으로 예측됩니다. 그 열 안정성, 밀도 제어, 윤활성 및 배출 성능은 고압·고온의 해양 유정에서의 사용을 지원하고 있습니다. 유성 시추액는 중동 및 중앙아시아의 성숙한 육상 유전에서 여전히 수요가 있습니다. 이러한 지역에서는 유정 안정성 및 윤활성 요구 사항이 추가적인 규제 요건보다 우선시되는 경우가 있습니다.
‘기타’ 범주에는 기존 시추 진흙 기둥이 지층을 손상시킬 우려가 있는 고갈된 저류층이나 지열 우물에서 사용되는 공기압식, 발포식 및 통기식 시스템이 포함됩니다. 쉐브론 필립스 케미컬(Chevron Phillips Chemical)과 드릴링 스페셜티즈(Drilling Specialties)는 2025년 11월, 그래핀과 Synfluid PAO 윤활유를 배합한 ‘NanoSlide’를 출시했습니다. 이 제품은 마찰계 시험에서 0.05 미만의 마찰 계수를 기록했습니다. 이 제품은 장거리 시추 및 고압·고온의 시추 조건을 위해 설계되었습니다. 발표된 연구에 따르면 생분해성 나노복합재 덕분에 필터 케이크의 두께가 2.5 mm에서 1.5 mm로 감소했을 뿐만 아니라, 고압 여과 손실도 줄어든 것으로 밝혀졌습니다. 이러한 개발을 통해 수성 시스템과 합성 시스템 간의 기술적 격차가 부분적으로 해소되고 있습니다. 그 결과, 시추액 선정은 시추공 총비용, 시추 시간, 폐기물 처리 요건 및 운영 위험과 더욱 밀접하게 연관되어 가고 있습니다.
지역별 분석
2025년, 북미는 퍼미안, 이글포드, 바켄의 셰일 개발, 멕시코만 프로젝트 및 캐나다 서부 운영에 힘입어 시추액 시장 점유율의 37.7%를 차지했습니다. 이 지역은 수평 시추 효율성 면에서 여전히 세계적 중심지입니다. 원유 가격 하락과 시추 장비 수 감소로 인해 미국의 단기 시추 활동은 둔화되고 있지만, 퍼미안 분지의 지속적인 성장이 기존 및 해양 분야의 감소를 부분적으로 상쇄하고 있습니다. 멕시코만의 심해 개발은 합성계 및 첨단 수계 시스템에 더 지속적인 수요 기반을 제공하고 있습니다. 캐나다의 몬토니 및 듀버네이 플레이에서 패드 시추 방식이 채택됨에 따라 몬모릴로나이트가 풍부하게 함유된 지층을 위해 설계된 수계 시추액에 대한 수요가 지원되고 있습니다.
유럽은 시추액 시장에 대한 기여도는 작지만, 가장 엄격한 요건이 요구되는 해양용 유체의 용도가 몇 가지 포함되어 있습니다. 노르웨이 대륙붕에서 에퀴노르(Equinor)사의 2026년 계약 옵션은 시추 및 완공용 유체가 여전히 장기 주기의 유정 서비스 프로그램에 포함되어 있음을 보여줍니다. 북해의 운영사들은 OSPAR의 배출 요건을 충족해야 하며, 이는 고압 성능과 생분해성이라는 두 가지 요구 사항을 모두 충족할 수 있는 고사양 합성계 시스템에 대한 수요를 지원하고 있습니다. 폴란드, 러시아, 영국은 기존의 육상 작업, 성숙한 북해 프로젝트, 그리고 워크오버 활동을 통해 지역적 수요를 끌어올리고 있습니다. 러시아 프로젝트는 수량 측면에서 수요를 창출하고 있지만, 지정학적 제약으로 인해 일부 첨단 기술에 대한 접근이 제한되고 있습니다.
아시아태평양은 가장 빠른 성장세를 기록할 것으로 예상되며, 시추액 시장 규모는 2031년까지 연평균 성장률(CAGR) 6.3%로 확대될 전망입니다. 중국의 남중국해 활동, 인도의 심해 광구, 그리고 인도네시아, 베트남, 브루나이, 호주에서의 라이선싱 프로그램이 이러한 성장을 지원하고 있습니다. 이 지역의 시추액 소비량의 43%를 중국이 차지하고 있으며, 수성 시스템이 지역 수요의 67%를 차지하고 있습니다. 또한 동남아시아의 심해 개발 활동 증가에 따라 2024년에는 합성 배합 제품에 대한 수요가 18% 증가했습니다. 남미에서는 브라질의 프레솔트층 개발과 아르헨티나의 바카 무에르타 개발이 주도적인 역할을 하고 있으며, 이들은 환경 부하가 낮은 해양용 혼합제 및 긴 셰일층에 대응하는 억제성 유체를 필요로 합니다. 중동에서는 사우디아라비아, 아랍에미리트, 이라크에서 대량의 기존형 시추 슬러리가 사용되는 반면, 서아프리카 연안에서는 나이지리아, 알제리, 이집트에서 더 높은 사양의 시스템에 대한 수요가 증가하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 공급망 분석
- Porter's Five Forces 분석
- 기술 동향
- 규제 상황
- 투자 분석
제5장 시장 규모와 성장 예측
- 유형별
- 용도별
- 지역별
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 프랑스
- 이탈리아
- 영국
- 폴란드
- 러시아
- 기타 유럽 국가
- 아시아태평양
- 중국
- 인도
- 호주
- 인도네시아
- 베트남
- 브루나이
- 태국
- 기타 아시아태평양 국가
- 남미
- 브라질
- 아르헨티나
- 칠레
- 기타 남미 국가
- 중동 및 아프리카
- 사우디아라비아
- 아랍에미리트
- 이집트
- 나이지리아
- 알제리
- 기타 중동 및 아프리카 국가
- 북미
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- AES Drilling Fluids LLC
- Anchor Drilling Fluids USA Inc.
- Baker Hughes Company
- CES Energy Solutions Corp.
- Chevron Phillips Chemical Company LLC
- Flotek Industries Inc.
- Global Drilling Fluids and Chemical Limited
- Gumpro Drilling Fluids Pvt Ltd
- Halliburton Company
- IMDEX Limited
- National Oilwell Varco Inc.
- Newpark Resources Inc.
- Oilfield Chemical Co. Baker Petrolite
- Petrochem Performance Chemicals Ltd
- Q'Max Solutions Inc.
- Schlumberger Limited
- Scomi Energy Services Bhd
- TETRA Technologies Inc.
- Valence Drilling Fluids LLC
- Weatherford International plc
제7장 시장 기회와 향후 전망
KSA 26.10.29According to Mordor Intelligence, the drilling fluid market size is projected to be USD 10.04 billion in 2025, USD 10.55 billion in 2026, and reach USD 13.87 billion by 2031, at a CAGR of 5.62% from 2026 to 2031.
Global Drilling Fluid Market Trends and Insights
Deepwater and Ultra-Deepwater Campaigns
Deepwater and ultra-deepwater wells require high-performance synthetic and dense water-based systems, which creates the highest fluid spending per well in the drilling fluids market. Brazil, Guyana, and West Africa are contributing to offshore supply additions and are supporting demand for premium drilling services. SLB received a contract in December 2024 to support construction of more than 100 Petrobras deepwater wells in the Campos, Santos, and Espirito Santo basins, using drilling-fluid and cementing technologies on up to 9 ultra-deepwater rigs. Baker Hughes also extended integrated well construction work in Brazil's Santos Basin during 2026, covering fluids, cementing, wireline, and geosciences services. Brazil's pre-salt wells can pass through salt layers reaching 2,000 meters and face pressures above 10,000 psi, conditions that tighten the operating window for fluid density and wellbore stability. It also accommodates extended-reach drilling and complex long-lateral work in shale and offshore basins. These requirements raise revenue per drilled foot and favor providers that can maintain fluid performance during long, complex well sections. The drilling fluids market is also supported by spent-mud recycling and regional blending capacity, which can reduce waste obligations and shorten supply lead times near offshore projects.
Unconventional Shale and Tight-Reservoir Development
Horizontal drilling in shale and tight reservoirs uses more fluid per well than conventional vertical drilling and continues to support volume demand in the drilling fluids market. The Permian Basin remains central to this demand, although lower oil prices and capital discipline have slowed U.S. production growth and reduced activity across some basins. Long laterals above 10,000 feet and multiple landing targets keep fluid requirements high for many Permian wells. Argentina's Vaca Muerta play is also expanding horizontal programs that need inhibitive water-based fluids for reactive Jurassic shales. China's Sichuan and Tarim programs are moving toward complex multilateral well designs, where advanced polymer water-based fluids are used to manage deep and overpressured formations. These programs favor service companies with localized blending capacity, technical support, and reliable access to specialty materials.
Crude-Price-Driven Drilling-Budget Volatility
Oil-price weakness is the most immediate demand risk for the drilling fluids market because operators reduce rig activity and defer well programs when expected returns decline. The Dallas Federal Reserve's March 2025 survey reported that some operators were suspending drilling in response to potential WTI prices below USD 50 per barrel, with respondents citing reductions from 10 active wells to 5 or fewer. Baker Hughes stated in July 2026 that global E&P spending is expected to decline modestly in 2026, as growth in Latin America and offshore Africa offsets weakness in Europe and the Middle East. Strait of Hormuz disruptions added logistical and inflationary pressure at regional facilities. Raw-material availability also remains a concern because specialty polymers and barite can increase input costs and create procurement risk. Managed-pressure drilling may further reduce fluid intensity in some wells by controlling pressure more precisely, although it also increases the need for responsive fluid systems and monitoring.
Other drivers and restraints analyzed in the detailed report include:
- Low-Toxicity and Environmentally Compliant Fluid Adoption
- Real-Time Rheology Control and Digital Fluid Management
- Oil-Based-Cuttings Discharge and Disposal Restrictions
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Water-based drilling fluids led with 57.1% revenue share in 2025 as they are widely accepted by regulators and are suitable for high-volume onshore drilling. Their position includes standard bentonite systems as well as higher-value polymer-enhanced and nano-additive formulations. Operators in horizontal and extended-reach wells increasingly require stronger rheology control and shale inhibition than basic formulations can provide. Synthetic-based fluids are the fastest-growing type, with the drilling fluids market size for this segment forecast to increase at a 5.9% CAGR through 2031. Their thermal stability, density control, lubricity, and discharge credentials support use in high-pressure, high-temperature offshore wells. Oil-based fluids retain demand in mature Middle Eastern and Central Asian onshore plays, where wellbore-stability and lubricity needs can outweigh added compliance requirements.
The others category includes pneumatic, foam, and aerated systems used in depleted reservoirs and geothermal wells where conventional mud columns could damage the formation. Chevron Phillips Chemical and Drilling Specialties launched NanoSlide in November 2025, a graphene and Synfluid PAO lubricant that recorded a coefficient of friction below 0.05 in tribometer testing. The product was designed for extended-reach and high-pressure, high-temperature drilling conditions. Published research also found that biodegradable nanocomposites reduced filter-cake thickness from 2.5 mm to 1.5 mm while lowering high-pressure filtration loss. These developments narrow some technical gaps between water-based and synthetic systems. Fluid selection is therefore becoming more closely linked to total well cost, drilling time, waste requirements, and operating risk.
Complete Report Scope:
- By Type
- Water-Based
- Oil-Based
- Synthetic-Based
- Others
- By Application
- Onshore
- Offshore
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- Italy
- United Kingdom
- Poland
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Australia
- Indonesia
- Vietnam
- Brunei
- Thailand
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Egypt
- Nigeria
- Algeria
- Rest of Middle East and Africa
- North America
Geography Analysis
North America held 37.7% of drilling fluids market share in 2025, supported by Permian, Eagle Ford, and Bakken shale activity, Gulf of Mexico projects, and Western Canadian operations. The region remains a global center for horizontal drilling efficiency. Lower crude prices and reduced rig counts are slowing near-term U.S. activity, although continued Permian growth partly offsets declines in conventional and offshore areas. Gulf of Mexico deepwater developments provide a more durable demand base for synthetic and advanced water-based systems. Canada's use of pad drilling in the Montney and Duvernay plays supports demand for water-based fluids designed for montmorillonite-rich formations.
Europe is a smaller contributor to the drilling fluids market, but it includes some of the most demanding offshore fluid applications. Equinor's 2026 contract options on the Norwegian Continental Shelf show that drilling and completion fluids remain embedded in long-cycle well-service programs. North Sea operators must meet OSPAR discharge requirements, which supports high-specification synthetic systems that can meet both high-pressure performance and biodegradability needs. Poland, Russia, and the United Kingdom add regional demand through conventional onshore work, mature North Sea projects, and workover activity. Russian projects provide volume demand, while geopolitical constraints limit access to some advanced technologies.
Asia-Pacific is forecast to record the fastest growth, with the drilling fluids market size expected to advance at a 6.3% CAGR through 2031. China's South China Sea activity, India's deepwater blocks, and licensing programs in Indonesia, Vietnam, Brunei, and Australia support this expansion. China represents 43% of regional fluid consumption, while water-based systems account for 67% of regional demand and synthetic formulations grew 18% in 2024 as Southeast Asian deepwater activity increased. South America is led by Brazil's pre-salt work and Argentina's Vaca Muerta development, which require lower-impact offshore formulations and inhibitive fluids for long shale sections. The Middle East supports high volumes of conventional mud in Saudi Arabia, the United Arab Emirates, and Iraq, while offshore West Africa is building demand for higher-specification systems in Nigeria, Algeria, and Egypt.
- AES Drilling Fluids LLC
- Anchor Drilling Fluids USA Inc.
- Baker Hughes Company
- CES Energy Solutions Corp.
- Chevron Phillips Chemical Company LLC
- Flotek Industries Inc.
- Global Drilling Fluids and Chemical Limited
- Gumpro Drilling Fluids Pvt Ltd
- Halliburton Company
- IMDEX Limited
- National Oilwell Varco Inc.
- Newpark Resources Inc.
- Oilfield Chemical Co. Baker Petrolite
- Petrochem Performance Chemicals Ltd
- Q'Max Solutions Inc.
- Schlumberger Limited
- Scomi Energy Services Bhd
- TETRA Technologies Inc.
- Valence Drilling Fluids LLC
- Weatherford International plc
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Deepwater and Ultra-Deepwater Campaigns
- 4.2.2 Unconventional Shale and Tight-Reservoir Development
- 4.2.3 Low-Toxicity and Environmentally Compliant Fluid Adoption
- 4.2.4 Real-Time Rheology Control and Digital Fluid Management
- 4.2.5 Spent-Mud Recycling and Reconditioning
- 4.2.6 National Oil Company Localization and Regional Blending
- 4.3 Market Restraints
- 4.3.1 Crude-Price-Driven Drilling-Budget Volatility
- 4.3.2 Oil-Based-Cuttings Discharge and Disposal Restrictions
- 4.3.3 Specialty Polymer and Barite Supply Tightness
- 4.3.4 Managed-Pressure Drilling Reducing Fluid Intensity
- 4.4 Supply-Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Type
- 5.1.1 Water-Based
- 5.1.2 Oil-Based
- 5.1.3 Synthetic-Based
- 5.1.4 Others
- 5.2 By Application
- 5.2.1 Onshore
- 5.2.2 Offshore
- 5.3 By Geography
- 5.3.1 North America
- 5.3.1.1 United States
- 5.3.1.2 Canada
- 5.3.1.3 Mexico
- 5.3.2 Europe
- 5.3.2.1 Germany
- 5.3.2.2 France
- 5.3.2.3 Italy
- 5.3.2.4 United Kingdom
- 5.3.2.5 Poland
- 5.3.2.6 Russia
- 5.3.2.7 Rest of Europe
- 5.3.3 Asia-Pacific
- 5.3.3.1 China
- 5.3.3.2 India
- 5.3.3.3 Australia
- 5.3.3.4 Indonesia
- 5.3.3.5 Vietnam
- 5.3.3.6 Brunei
- 5.3.3.7 Thailand
- 5.3.3.8 Rest of Asia-Pacific
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Chile
- 5.3.4.4 Rest of South America
- 5.3.5 Middle East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 United Arab Emirates
- 5.3.5.3 Egypt
- 5.3.5.4 Nigeria
- 5.3.5.5 Algeria
- 5.3.5.6 Rest of Middle East and Africa
- 5.3.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 AES Drilling Fluids LLC
- 6.4.2 Anchor Drilling Fluids USA Inc.
- 6.4.3 Baker Hughes Company
- 6.4.4 CES Energy Solutions Corp.
- 6.4.5 Chevron Phillips Chemical Company LLC
- 6.4.6 Flotek Industries Inc.
- 6.4.7 Global Drilling Fluids and Chemical Limited
- 6.4.8 Gumpro Drilling Fluids Pvt Ltd
- 6.4.9 Halliburton Company
- 6.4.10 IMDEX Limited
- 6.4.11 National Oilwell Varco Inc.
- 6.4.12 Newpark Resources Inc.
- 6.4.13 Oilfield Chemical Co. Baker Petrolite
- 6.4.14 Petrochem Performance Chemicals Ltd
- 6.4.15 Q'Max Solutions Inc.
- 6.4.16 Schlumberger Limited
- 6.4.17 Scomi Energy Services Bhd
- 6.4.18 TETRA Technologies Inc.
- 6.4.19 Valence Drilling Fluids LLC
- 6.4.20 Weatherford International plc
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


