

|
시장보고서
상품코드
2157058
플라스틱 압력관 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Plastic Pressure Pipes - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
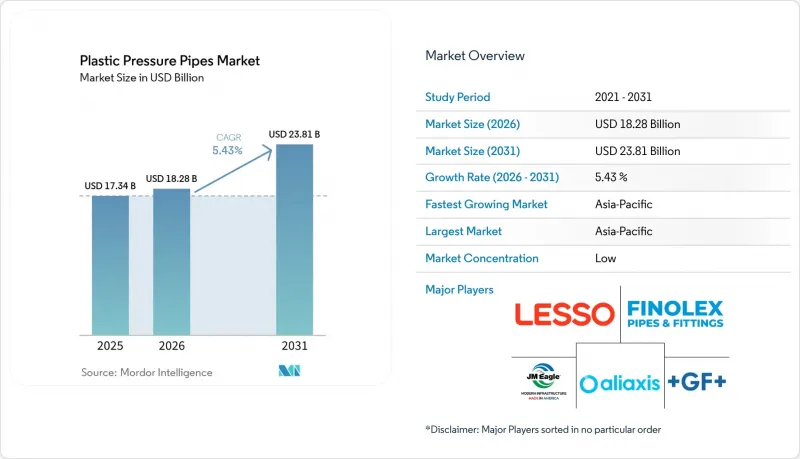
에 따르면 플라스틱 압력관 시장 규모는 2025년에 173억 4,000만 달러로 평가되며, 2026년 182억 8,000만 달러에서 2031년까지 238억 1,000만 달러에 달할 것으로 추정되고 있으며, 예측 기간(2026-2031년)에 CAGR은 5.43%에 달할 전망입니다.
글로벌 플라스틱 가압관 시장의 동향 및 인사이트
노후화된 상하수도 네트워크로 인한 압력관 교체 수요
상하수도 사업자가 노후화된 상하수도 인프라를 교체할 때, 플라스틱 가압관 시장은 그 혜택을 누리게 됩니다. 미국 환경보호청(EPA)은 2024년 10월, 음용수 시스템에 대해 납제 급수관을 특정하고 10년 이내에 교체하도록 의무화하는 요건을 최종 확정했습니다. ‘초당적 인프라 법안’에 따라 납제 급수관의 교체를 지원하기 위해 150억 달러의 연방 자금이 배정되었습니다. 이로 인해 미뤄졌던 유지 관리의 일부가 고밀도 폴리에틸렌(HDPE) 및 PVC-O 파이프 제조업체들에게 규제 준수를 주축으로 한 조달 주기로 전환될 것입니다. 또한 개보수 사양에서도 PE100-RC 등 비개착 공법에 대응하는 등급이 점점 더 중요시되고 있으며, 이를 통해 설치 1미터당 수익을 높일 수 있습니다. 미국 상수도 협회(AWWA) 및 ISO 규격, 2024년 미국 EPA의 ‘납·구리 규정’ 개정, 그리고 EU의 도시 하수 처리 지침이 공공 프로젝트의 사양 및 자재 선정에 영향을 미치고 있습니다.
효율적인 관개 및 절수 인프라의 확대
효율적인 관개로 인해 물 부족 지역의 플라스틱 가압관 시장에 대한 잠재적 수요 기반이 확대되고 있습니다. 중국은 폴리에틸렌 가압관용 농업 관개 새들에 관한 국가 표준(GB/T) 19796.1-2025를 공표했으며, 이는 2026년 5월부터 시행될 예정입니다. 인도의 ‘PM Krishi Sinchayee Yojana’는 ‘Jal Jeevan Mission 2.0’과 병행하여 시행되고 있으며, 농지 급수를 위한 인증된 uPVC 파이프 조달을 지원하고 있습니다. 비닐 협회(Vinyl Institute)의 보고서에 따르면 PVC의 송수 효율은 89%-99%인 반면, 흙으로 만든 용수로는 60%-65%에 그치고 있으며, 이는 관개 프로젝트에서 가압 시스템의 도입을 지원하는 근거가 됩니다. Molecor사의 TR6는 UNE-EN 17176 및 ISO 16422 인증을 획득한 PN6 사양의 PVC 관개용 파이프로, 기존의 PVC-U PN6에 비해 강성이 15% 더 높습니다. 이러한 요건은 농경지에 대한 배수 수요를 충족시키면서 동시에 자재 사용량을 줄인 제품을 장려하는 것입니다.
폴리머 및 첨가제의 가격 변동
수지가 주요 투입 비용이기 때문에 폴리머 및 첨가제의 가격 변동은 플라스틱 가압관 시장을 억제하는 요인이 되고 있습니다. 2026년 7월 기준, 플라스틱 관 및 관 이음쇠 제조와 관련된 미국의 생산자 물가 지수는 418.1이었습니다. 이 지수는 에틸렌 및 PVC 단량체의 비용 주기에 미치는 지속적인 영향을 반영합니다. 가격 변동은 제조업체, 계약업체 및 공공 사업 예산에 동시에 영향을 미칩니다. 수지 가격이 안정적이라면 생산자는 생산 능력 계획을 수립하거나 장기적인 인프라 사업 입찰에 더 확실한 전망을 가지고 임할 수 있습니다. 인도는 2026년 7월 PVC 수지에 대해 최저 수입 가격을 부과했는데, 이는 수지 가격의 불안정성이 정책 조치를 초래할 수도 있음을 보여줍니다.
부문 분석
2025년, PVC는 플라스틱 압력관 시장의 48.67%를 차지했습니다. 이러한 위상은 낮은 수지 비용, 확립된 시공업체의 기술 기반, 그리고 배수 및 농업 시스템에서 사용되는 기존 이음쇠와의 호환성을 반영합니다. PVC-O는 기존 PVC의 4,000psi에 비해 정수압 설계 기준이 7,100psi이므로, 대구경 도시 상수도 본관에서 사용이 증가하고 있습니다. 이러한 높은 정격 덕분에 동등한 압력 수준에서도 벽 두께를 얇게 할 수 있으며, 자재 사용량과 설치시 중량을 줄일 수 있습니다. 폴리프로필렌(PP) 및 기타 소재는 PVC로는 운용상 제한이 있는 고온의 특수 산업용 및 화학 용도에 사용되고 있습니다.
PE 시장은 2031년까지 연평균 성장률(CAGR) 6.24%로 확대될 것으로 예측됩니다. PE는 무굴착 개량 공사, 대구경 융착 용접식 송수관 및 농업용 점적 관개 시스템에 적용됩니다. CHINA LESSO사는 2026년 상반기에 아프리카 및 동남아시아로 농업용 특수 배관 사업을 확대할 것이라고 보고했습니다. 또한 이 회사는 같은 기간 중 고성능 복합 배관에 대한 조사를 수행하고 관련 특허 여러 건을 취득했다고 보고했습니다. 따라서 재료 선정은 요구되는 내압 성능, 설치 방법, 온도 환경 및 예상되는 사용 조건을 반영하게 됩니다.
지역별 분석
아시아태평양은 2025년 플라스틱 가압관 시장의 45.06%를 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 6.39%로 확대될 것으로 예측됩니다. 중국과 인도에서는 도시 상수도, 농촌 급수 및 농업 관개 프로그램이 시장을 주도하고 있습니다. JJM 2.0에 따라 인도에서는 2028년 12월까지 장기적인 농촌 용수 조달 프로그램이 시행될 예정입니다. 중국의 GB/T 19796.1-2025 규격은 2026년 5월부터 PE 재질 농업용 관개 새들에 적용되고 있습니다. 일본과 한국에서는 성숙한 배관망과 높은 품질 기준을 배경으로 노후 배관 교체 수요가 발생하고 있습니다. 동남아시아 및 남아시아에서는 도시 확장과 상수도망 확충으로 인해 수요가 증가하고 있습니다.
북미 및 유럽에서는 수요가 개보수 공사에 중점을 두고 있으며, 지자체 및 산업의 사양을 충족하는 PE100-RC 및 PVC-O 등급이 포함됩니다. 미국의 납 급수관 규제에 따라 10년에 걸친 명확한 교체 의무가 정해져 있습니다. ISO 11300-1:2026은 지하 상수도망의 무굴착 교체에 있으며, PE 사용에 관한 기술적 근거를 제공합니다. 유럽의 규제 요건은 도시 재생 프로젝트에서 EN 12201을 준수하는 PE 및 PVC-O의 선정에 영향을 미치고 있습니다. 또한 영국에서는 지속적인 상수도 인프라 투자 프로그램이 시행되고 있으며, 이는 가압관 제조업체의 국내 수요를 지원하고 있습니다.
남미, 중동 및 아프리카는 플라스틱 압력관 시장에서 신흥 성장 지역으로 부상하고 있습니다. GF Industry and Infrastructure Flow Solutions는 2026년 4월, 상파울루주의 375개 지자체에서 급수 네트워크 현대화를 위해 SABESP와 1억 스위스 프랑(약 1억 2,650만 달러) 규모의 계약을 체결했습니다. 사우디아라비아의 물 전략은 2030년까지 1만 km가 넘는 새로운 송수 인프라 구축을 목표로 하고 있으며, 300억 달러의 투자가 포함되어 있습니다. CHINA LESSO는 2025년 5월 에티오피아에 생산 거점을 개설한 한편, Polyfab Plastic 중동 FZC는 수출 네트워크를 통해 아프리카의 여러 시장에 제품을 공급하고 있습니다. 이 지역들은 물 부족, 인프라 수요, 그리고 수출 지향적인 공급업체들의 활동이 맞물려 있으며, 시장으로서의 잠재력이 기대됩니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 밸류체인 분석
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 소재별
- 최종사용자 산업별
- 지역별
- 아시아태평양
- 중국
- 인도
- 일본
- 한국
- 기타 아시아태평양 국가
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 기타 유럽 국가
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 중동 및 아프리카
- 사우디아라비아
- 남아프리카공화국
- 기타 중동 및 아프리카 국가
- 아시아태평양
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율·순위 분석
- 기업 개요
- Aliaxis Holdings SA
- APL Apollo
- ASTRAL PIPES
- CHINA LESSO
- Finolex Industries Limited
- GF Industry and Infrastructure Flow Solutions
- JM EAGLE, INC.
- KPT Piping System
- LUNA PLAST a.s. na EDB
- Martoni Group
- Molecor
- P&F Global
- Polyfab Plastic Middle East FZC
- Supreme
- TRUFLO
제7장 시장 기회와 향후 전망
KSA 26.10.30According to Mordor Intelligence, the plastic pressure pipes market size was valued at USD 17.34 billion in 2025 and is estimated to grow from USD 18.28 billion in 2026 to reach USD 23.81 billion by 2031, at a CAGR of 5.43% during the forecast period (2026-2031).
Global Plastic Pressure Pipes Market Trends and Insights
Aging Water and Wastewater Networks Requiring Pressure-Pipe Replacement
The plastic pressure pipes market benefits when utilities replace aging water and wastewater infrastructure. The U.S. Environmental Protection Agency finalized requirements in October 2024 for drinking water systems to identify and replace lead service lines within 10 years. Federal funding of USD 15 billion supports the lead service line transition under the Bipartisan Infrastructure Law. This turns a portion of deferred maintenance into a compliance-led procurement cycle for High-Density Polyethylene (HDPE) and PVC-O pipe producers. Rehabilitation specifications also increasingly favor trenchless-compatible grades such as PE100-RC, which can increase revenue per installed meter. American Water Works Association (AWWA) and ISO standards, the 2024 U.S. EPA Lead and Copper Rule revision, and the EU Urban Wastewater Treatment Directive influence public-project specifications and material selection.
Expansion of Efficient Irrigation and Water-Conservation Infrastructure
Efficient irrigation is widening the addressable demand base for the plastic pressure pipes market in water-scarce regions. China issued Guobiao (GB/T) 19796.1-2025 for polyethylene pressure-pipe agricultural irrigation saddles, with implementation effective in May 2026. India's PM Krishi Sinchayee Yojana operates alongside Jal Jeevan Mission 2.0 and supports certified uPVC pipe procurement for farm distribution. The Vinyl Institute reported PVC delivery efficiency of 89%-99%, compared with 60%-65% for earthen canals, which supports the use of pressurized systems in irrigation projects. Molecor's TR6 is a PN6-oriented PVC irrigation pipe certified under UNE-EN 17176 and ISO 16422, with 15% higher stiffness than conventional PVC-U PN6. These requirements support products that use less material while meeting farm-water distribution needs.
Polymer and Additive Price Volatility
Polymer and additive price changes restrain the plastic pressure pipes market because resin is a major input cost. The U.S. Producer Price Index for plastics pipe and pipe fitting manufacturing stood at 418.1 in July 2026. The index reflects continued exposure to ethylene and PVC monomer cost cycles. Price movements affect manufacturers, contractors, and public-project budgets at the same time. A stable resin environment allows producers to plan capacity and bid on longer infrastructure programs with greater certainty. India imposed a minimum import price on PVC resin in July 2026, showing that resin price instability can also prompt policy action.
Other drivers and restraints analyzed in the detailed report include:
- Corrosion Resistance and Lower Installed Cost Versus Metallic Alternatives
- Trenchless Rehabilitation Enabled by Flexible PE and Fusion-Jointed Systems
- Fragmented Certification and Pressure-Rating Requirements Across Countries
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
PVC held 48.67% of the plastic pressure pipes market in 2025. Its position reflects lower resin cost, an established contractor skill base, and compatibility with existing fittings used in water distribution and agricultural systems. PVC-O is gaining use in large-diameter municipal mains because its hydrostatic design basis is 7,100 psi, compared with 4,000 psi for conventional PVC. The higher rating permits thinner walls at comparable pressure levels and can reduce material use and installation weight. Polypropylene (PP) and other materials serve specialized higher-temperature industrial and chemical applications where PVC has operating limitations.
PE is projected to advance at a 6.24% CAGR through 2031. It supports trenchless rehabilitation, large-diameter fusion-welded water transmission, and agricultural drip systems. CHINA LESSO reported expanded specialized agricultural piping into Africa and Southeast Asia in the first half of 2026. The company also reported high-performance composite piping research and several associated patents during that period. Material selection, therefore, reflects the required pressure performance, installation method, temperature exposure, and expected service conditions.
Complete Report Scope:
- By Material
- Polyvinyl Chloride (PVC)
- Polyethylene (PE)
- Polypropylene (PP)
- Other Materials
- By End-User Industry
- Water and Wastewater Treatment
- Building and Construction
- Agriculture
- Oil and Gas
- Mining
- Industrial
- Other End-User Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 45.06% of the plastic pressure pipes market in 2025 and is projected to advance at a 6.39% CAGR through 2031. China and India are supported by municipal water, rural distribution, and agricultural-irrigation programs. JJM 2.0 gives India a long-term rural water procurement program through December 2028. China's GB/T 19796.1-2025 standard has applied to PE agricultural irrigation saddles since May 2026. Japan and South Korea provide replacement demand shaped by mature networks and high-quality requirements. Southeast Asia and South Asia add demand through urban expansion and water-network development.
In North America and Europe, demand is weighted toward rehabilitation, including PE100-RC and PVC-O grades that meet municipal and industrial specifications. The U.S. lead service line rule creates a defined replacement obligation over 10 years. ISO 11300-1:2026 provides a technical basis for PE use in trenchless renewal of underground water networks. European regulatory requirements influence the selection of EN 12201 PE and PVC-O in urban renewal projects. The United Kingdom also has a sustained water infrastructure investment program, which supports domestic demand for pressure pipe producers.
South America and the Middle East and Africa are emerging growth areas in the plastic pressure pipes market. GF Industry and Infrastructure Flow Solutions signed a CHF 100 million (approximately USD 126.5 million) contract with SABESP in April 2026 to modernize water distribution networks in 375 municipalities in Sao Paulo state. Saudi Arabia's water strategy targets more than 10,000 km of new water transmission infrastructure by 2030 and includes USD 30 billion of investment. CHINA LESSO inaugurated an Ethiopian production base in May 2025, while Polyfab Plastic Middle East FZC supplies several African markets through its export network. These regions combine water scarcity, infrastructure needs, and export-oriented supplier activity.
- Aliaxis Holdings SA
- APL Apollo
- ASTRAL PIPES
- CHINA LESSO
- Finolex Industries Limited
- GF Industry and Infrastructure Flow Solutions
- JM EAGLE, INC.
- KPT Piping System
- LUNA PLAST a.s. na EDB
- Martoni Group
- Molecor
- P&F Global
- Polyfab Plastic Middle East FZC
- Supreme
- TRUFLO
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Aging Water and Wastewater Networks Requiring Pressure-Pipe Replacement
- 4.2.2 Expansion of Efficient Irrigation and Water-Conservation Infrastructure
- 4.2.3 Corrosion Resistance and Lower Installed Cost Versus Metallic Alternatives
- 4.2.4 Trenchless Rehabilitation Enabled by Flexible PE and Fusion-Jointed Systems
- 4.2.5 Digital Leak Detection and Asset-Monitoring Compatibility of New Pipe Networks
- 4.3 Market Restraints
- 4.3.1 Polymer and Additive Price Volatility
- 4.3.2 Fragmented Certification and Pressure-Rating Requirements Across Countries
- 4.3.3 Limited Availability of Verified Recycled Resin for Pressure Applications
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Material
- 5.1.1 Polyvinyl Chloride (PVC)
- 5.1.2 Polyethylene (PE)
- 5.1.3 Polypropylene (PP)
- 5.1.4 Other Materials
- 5.2 By End-User Industry
- 5.2.1 Water and Wastewater Treatment
- 5.2.2 Building and Construction
- 5.2.3 Agriculture
- 5.2.4 Oil and Gas
- 5.2.5 Mining
- 5.2.6 Industrial
- 5.2.7 Other End-User Industries
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Aliaxis Holdings SA
- 6.4.2 APL Apollo
- 6.4.3 ASTRAL PIPES
- 6.4.4 CHINA LESSO
- 6.4.5 Finolex Industries Limited
- 6.4.6 GF Industry and Infrastructure Flow Solutions
- 6.4.7 JM EAGLE, INC.
- 6.4.8 KPT Piping System
- 6.4.9 LUNA PLAST a.s. na EDB
- 6.4.10 Martoni Group
- 6.4.11 Molecor
- 6.4.12 P&F Global
- 6.4.13 Polyfab Plastic Middle East FZC
- 6.4.14 Supreme
- 6.4.15 TRUFLO
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


