
|
시장보고서
상품코드
2131870
자동차용 접착제 시장 예측(-2031년) : 수지 유형별, 차종별, 용도별, 지역별Automotive Adhesives Market by Resin Type, Vehicle Type, Application, and Region - Global Forecast to 2031 |
||||||

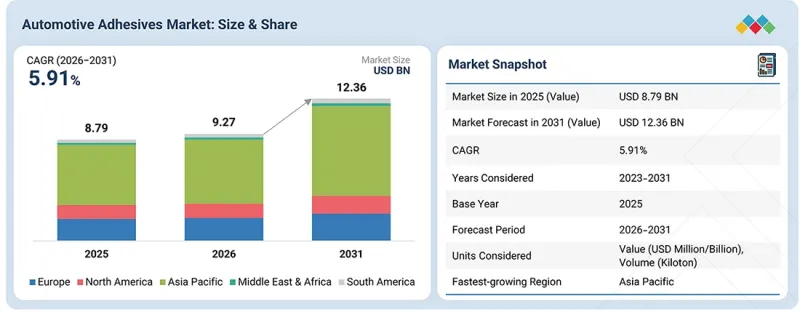
자동차용 접착제 시장 규모는 2026년 92억 7,000만 달러에서 2031년까지 123억 6,000만 달러로, CAGR 5.91%로 확대할 것으로 추정되고 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2023-2031년 |
| 기준연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 산정개 | 금액(100만/10억 달러) 및 킬로톤 |
| 부문 | 수지 유형별, 차종별, 용도별, 지역별 |
| 대상 지역 | 아시아태평양, 유럽, 북미, 중동 및 아프리카, 남미 |
접착제 제조업체들의 지속적인 기술 혁신으로 인해 자동차 분야의 적용 범위가 확대되고 시장 기회가 강화되고 있습니다. 각 공급업체들은 경화 시간 단축, 내열성 향상, 접착이 어려운 기판에 대한 접착력 향상, 그리고 자동 가공을 위한 유연성 향상을 실현하는 배합 개발을 추진하고 있습니다. 또한 배터리 조립, 이종 재료 구조, 구조용 접착 및 차량 내장재와 관련된 특정 요구 사항을 충족하기 위한 신기술도 설계되고 있습니다. 1액형 시스템, 광경화, 습기 경화 및 기타 도포 방법의 개선을 통해 제조사는 생산 요구 사항에 따라 접착제 기술을 보다 쉽게 선택할 수 있게 되었습니다. 아울러 제품 개발에서는 보관 안정성 및 공정 관리 개선에도 중점을 두고 있으며, 이를 통해 자동차 공장내 취급이 간소화됩니다. 이러한 지속적인 혁신을 통해 시장 성장이 단순히 자동차 생산 대수의 증가에만 의존하는 것이 아니라, 자동차용 접착제의 기술적 역량이 확대되고 있습니다. 접착 기술의 진화가 계속됨에 따라 제조업체는 더욱 폭넓은 차량 설계 및 조립 조건에 적합한 접착 솔루션을 활용할 수 있게 될 것입니다.
"2025년, 애프터마켓 부문은 자동차용 접착제 시장에서 3위의 점유율을 차지했습니다."
2025년, 애프터마켓 부문은 자동차용 접착제 시장에서 금액 기준 3위의 점유율을 차지했습니다. 이는 차량 수리 및 유지보수 서비스에 대한 수요 증가에 힘입은 결과입니다. 차량의 사용 기간이 길어짐에 따라 교체 및 수리 작업으로 인해 접착 제품에 대한 지속적인 수요가 발생하고 있습니다. 자동차용 접착제는 트림 장착, 앞유리 장착, 내장 수리, 차체 패널 작업 및 특정 부품 교체에 사용됩니다. 자동차 부품 판매점, 정비소, 전문 서비스 센터를 통해 구할 수 있으므로 다양한 차종에서 편리하게 사용할 수 있습니다. 또한 접착제는 정확한 장착과 적절한 표면 접촉이 요구되는 부품에 대해 수리 전문가에게 실용적인 접합 수단을 제공합니다. 따라서 운행 중인 차량 대수의 증가는 애프터마켓에서 꾸준한 소비 흐름을 창출하고 있습니다. 이러한 수요는 북미 및 유럽 전역에서 이루어지는 정기 정비, 충돌 수리, 외관 복원, 그리고 노후된 내외장 부품의 교체를 통해 지원되고 있습니다.
"2025년, SMP 부문은 자동차용 접착제 시장에서 세 번째로 큰 점유율을 차지했습니다."
2025년, 자동차용 접착제 시장에서 SMP 부문은 금액 기준으로 세 번째로 큰 점유율을 차지했습니다. 이는 제조사들이 저배출형 접착제 기술에 대한 관심을 높였기 때문입니다. SMP 배합은 용제를 사용하지 않고 개발할 수 있으며, 차량 생산 현장이나 수리 시설에서 더 깨끗한 시공 환경을 실현합니다. 또한 그 습기 경화 공정은 상온 경화를 가능하게 하여, 적절한 시공을 위해 고온 설비에 대한 의존도를 낮춥니다. 이러한 특성은 작업 환경 개선 및 공정내 에너지 소비 절감에 중점을 둔 제조 프로그램과 부합합니다. SMP 기술은 트림, 패널, 내장 부품 및 유연한 접착이 요구되는 기타 부품의 접착 분야에서 주목을 받고 있습니다. 접착제 공급업체들은 자동차 생산의 요구를 충족하기 위해 경화 속도, 접착력 및 보관 안정성 향상에 주력하고 있습니다. 보다 깨끗한 배합 선택에 대한 관심이 높아짐에 따라 자동차 제조 및 애프터마켓 용도 전반에 걸쳐 SMP 접착제에 대한 명확한 수요 기반이 형성되고 있습니다.
"2025년, 자동차용 접착제 시장에서 조립 부문은 세 번째로 큰 점유율을 차지했습니다."
2025년, 자동차용 접착제 시장에서 조립 용도는 금액 기준으로 3위의 점유율을 차지했습니다. 이는 자동차 생산 주기의 단축에 대한 관심이 높아지고 있는 것이 배경입니다. 자동차용 접착제를 통해 제조사는 조립 공정에서 기계적 체결 방법에만 의존하지 않고 부품을 접합할 수 있습니다. 자동 도포, 정밀한 도포 및 제어된 경화 기능을 지원하므로 생산 라인은 안정적인 가동 속도를 유지할 수 있습니다. 또한 접착 시스템은 특정 부품에 대한 개별 접합 공정의 횟수를 줄일 수 있으며, 차체, 내장, 트림의 각 조립 공정에 걸친 워크플로우를 원활하게 하는 데 기여합니다. 이는 기존 생산 능력에서 더 높은 생산량을 추구하는 자동차 공장에 유익합니다. 따라서 안정적인 도포 특성, 예측 가능한 경화 시간, 그리고 자동화 설비와의 호환성을 갖춘 접착제에 대한 수요가 증가하고 있습니다. 이러한 특성들 덕분에 북미 및 전 세계 자동차 생산 시설에서 접착제는 중요한 조립 재료로서의 역할을 강화하고 있습니다.
"2025년, 북미는 금액 기준으로 전 세계 자동차용 접착제 시장에서 3위의 점유율을 차지했습니다."
2025년, 북미는 금액 기준으로 세계 3위의 자동차용 접착제 시장이 되었으며, 각 제조사는 에너지 효율이 높은 차량 생산을 더욱 중시하게 되었습니다. 자동차용 접착제 공급업체들은 더 낮은 온도에서 경화되어 처리 시간을 단축하거나, 더 신속한 조립 조건에 대응할 수 있는 배합을 개발하고 있습니다. 이러한 기술을 통해 특히 가열, 건조 또는 열경화를 수반하는 공정에서 자동차 제조 공장의 에너지 수요를 줄일 수 있습니다. 저에너지 경화는 접착 성능을 저하시키지 않으면서 자원 효율 향상을 목표로 하는 생산 시설에도 유익합니다. 수성 및 반응형 접착제 기술은 그 배합 특성이 특정 자동차 용도에 적합할 경우 주목을 받고 있습니다. 이러한 제품의 지속가능성 측면에서의 가치는 단순히 접착제의 원자재를 변경하는 것뿐만 아니라, 공장의 에너지 사용 효율을 개선하는 데 있으며, 이는 북미 제조 산업 전반에서 자동차용 접착제의 새로운 성장 동력이 되고 있습니다.
이 보고서에서 다루고 있는 주요 기업 개요에는 헨켈 AG & Co. KGaA(독일), 3M(미국), Sika AG(스위스), Arkema S.A.(프랑스), H.B. Fuller Company(미국), DuPont de Nemours, Inc.(미국),PPG Industries, Inc.(미국), Huntsman International LLC(미국), Parker-Hannifin Corporation(미국) 및 Illinois Tool Works Inc.(미국)가 포함됩니다.
조사 범위
이 보고서에서는 자동차용 접착제 시장을 차종, 수지 유형, 용도, 지역별로 세분화하여 각 지역의 시장 규모·추정치(개 - 100만 달러) 및 수량(개 - 킬로톤)을 제공합니다. 또한 주요 업계 플레이어에 대한 상세한 분석을 통해 자동차용 접착제 시장과 관련된 각 기업의 사업 개요, 서비스 및 주요 전략에 대한 인사이트를 제공합니다.
이 보고서를 구매해야 하는 이유
본 조사 보고서는 업계 분석(업계 동향), 주요 기업의 시장 점유율 분석, 기업 개요 등 다양한 수준의 분석에 초점을 맞추고 있습니다. 이를 종합함으로써 자동차용 접착제 시장의 경쟁 구도, 신흥 및 고성장 부문, 고성장 지역, 그리고 시장 촉진요인, 억제요인, 성장 기회에 대한 전체적인 그림을 파악할 수 있습니다.
이 보고서는 다음 사항에 대한 인사이트를 제공합니다. :
- 시장 침투도: 세계 시장의 주요 기업이 제공하는 자동차용 접착제에 대한 포괄적인 정보
- 주요 촉진요인 분석:(전 세계 전기자동차 보급 가속화 및 배터리 팩 조립 수요 증가 시장 성장을 촉진하는 경량 차체 구조의 채택 확대, 신흥 경제국에서의 자동차 생산 확대), 제약 요인(석유화학 원자재 비용 상승, 다중 소재 기판 접착시 기술적 복잡성),기회(자동차 배터리 열 관리 분야에서 접착제 용도의 확대, 자동차 조립용 속경화형 접착제 개발) 및 과제(가혹한 차량 조건 하에서의 장기 내구성 요건 대응) 등, 자동차용 접착제 시장의 성장에 영향을 미치는 요인
- 제품 개발/혁신: 자동차용 접착제 시장의 향후 기술, 연구개발 활동 및 신제품·서비스 출시에 관한 상세 인사이트
- 시장 개발: 수익성이 높은 신흥 시장에 대한 포괄적인 정보--이 보고서에서는 지역별 자동차용 접착제 시장을 분석하고 있습니다.
- 시장 다각화: 전 세계 자동차용 접착제 시장의 신제품, 미개발 지역 및 최근 동향에 대한 포괄적인 정보
- 경쟁 분석: 자동차용 접착제 시장 주요 기업의 시장 점유율, 전략, 제품 및 생산 능력에 대한 상세한 평가
목차
제1장 서론
제2장 개요
제3장 주요 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 기술 진보, AI에 의한 영향, 특허, 혁신, 향후 응용
제7장 고객 상황과 구매 행동
제8장 지속가능성과 규제 상황
제9장 자동차용 접착제 시장(수지 유형별)
제10장 자동차용 접착제 시장(차종별)
제11장 자동차용 접착제 시장(용도별)
제12장 자동차용 접착제 시장(지역별)
제13장 경쟁 구도
제14장 기업 개요
제15장 조사 방법
제16장 부록
KSAThe automotive adhesives market is estimated to grow from USD 9.27 billion in 2026 to USD 12.36 billion by 2031, at a CAGR of 5.91%.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2023-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million/Billion) and Volume (Kiloton) |
| Segments | Vehicle Type, Resin Type, Application, and Region |
| Regions covered | Asia Pacific, Europe, North America, Middle East & Africa, and South America |
Continuous innovation by adhesive manufacturers is expanding the range of automotive applications and strengthening market opportunities. Suppliers are developing formulations with faster curing, improved temperature resistance, better adhesion to difficult substrates, and greater flexibility for automated processing. New technologies are also being designed to meet specific requirements associated with battery assemblies, mixed-material structures, structural bonding, and vehicle interiors. Improvements in one-component systems, light-assisted curing, moisture curing, and other application methods are helping manufacturers select adhesive technologies according to production requirements. Product development is also focused on improving storage stability and process control, which can simplify handling within automotive plants. This ongoing innovation is expanding the technical capabilities of automotive adhesives rather than relying only on higher vehicle production volumes for market growth. As adhesive technology continues to evolve, manufacturers gain access to bonding solutions suited to a broader range of vehicle designs and assembly conditions.
"The aftermarket segment accounted for the third-largest share in the automotive adhesives market in 2025."
The aftermarket segment accounted for the third-largest share of the automotive adhesives market, in terms of value, in 2025, supported by rising demand for vehicle repair and maintenance services. As vehicles remain in use for longer periods, replacement and repair activities create recurring requirements for bonding products. Automotive adhesives are used for trim attachment, windshield installation, interior repairs, body panel work, and selected component replacement. Their availability through automotive distributors, repair shops, and specialized service centers supports convenient application across different vehicle models. Adhesives also provide repair professionals with practical joining options for parts that require clean installation and suitable surface contact. Growth in the installed vehicle base therefore creates a steady aftermarket consumption stream. This demand is supported by routine maintenance, collision repair, cosmetic restoration, and replacement of aging interior and exterior components across North America and Europe.
"The SMP segment accounted for the third-largest share in the automotive adhesives market in 2025."
The SMP segment held the third-largest share of the automotive adhesives market, in terms of value, in 2025, as manufacturers increased attention to low-emission adhesive technologies. SMP formulations can be developed without solvents, supporting cleaner application conditions in vehicle production and repair facilities. Their moisture-curing process also supports ambient curing, reducing reliance on high-temperature equipment for suitable applications. These characteristics align with manufacturing programs focused on improving workplace conditions and lowering process energy use. SMP technology is gaining interest for bonding trim, panels, interior parts, and other components where flexible adhesion is required. Adhesive suppliers are improving curing speed, adhesion, and shelf stability to support automotive production needs. Greater focus on cleaner formulation choices is creating a distinct demand base for SMP adhesives across vehicle manufacturing and aftermarket applications.
"The assembly segment held the third-largest share in the automotive adhesives market in 2025."
The assembly application accounted for the third-largest share of the automotive adhesives market, in terms of value, in 2025, supported by the growing focus on faster vehicle production cycles. Automotive adhesives allow manufacturers to join components during assembly without relying only on mechanical fastening methods. Their ability to support automated dispensing, precise application, and controlled curing helps production lines maintain steady operating speeds. Adhesive systems can also reduce the number of separate joining steps for selected components, supporting smoother workflow across body, interior, and trim assembly. This is valuable for vehicle plants seeking higher production output from existing manufacturing capacity. Demand is therefore increasing for adhesives with consistent dispensing behavior, predictable setting time, and compatibility with automated equipment. These characteristics strengthen the role of adhesives as an important assembly material across North American and global automotive production facilities.
"North America accounted for the third-largest share of the global automotive adhesives market, in terms of value, in 2025."
North America was the third-largest automotive adhesives market, in terms of value, in 2025, with manufacturers placing greater emphasis on energy-efficient vehicle production. Automotive adhesive suppliers are developing formulations that cure at lower temperatures, require shorter processing times, or support faster assembly conditions. These technologies can reduce energy demand within vehicle manufacturing plants, particularly in processes involving heating, drying, or thermal curing. Low-energy curing also supports production facilities seeking to improve resource efficiency without reducing bonding performance. Water-based and reactive adhesive technologies are gaining attention where their formulation characteristics fit specific automotive applications. The sustainability value of these products comes from improving factory energy use rather than only changing the adhesive raw materials, creating a separate growth driver for automotive adhesives across North American manufacturing operations.
- By Company Type: Tier 1 - 55%, Tier 2 - 25%, and Tier 3 - 20%
- By Designation: Directors - 50%, Managers - 30%, and Others - 20%
- By Region: North America - 40%, Europe - 35%, Asia Pacific - 20%, RoW - 5%
The key players profiled in the report include Henkel AG & Co. KGaA (Germany), 3M Company (US), Sika AG (Switzerland), Arkema S.A. (France), H.B. Fuller Company (US), DuPont de Nemours, Inc. (US), PPG Industries, Inc. (US), Huntsman International LLC (US), Parker-Hannifin Corporation (US), and Illinois Tool Works Inc. (US).
Study Coverage
This report segments the market for automotive adhesives based on vehicle type, resin type, application, and region, and provides estimations of value (in USD Million) and volume (in Kiloton) for the overall market size across various regions. A detailed analysis of key industry players has been conducted to provide insights into their business overviews, services, and key strategies associated with the automotive adhesives market.
Reasons to Buy this Report
This research report is focused on various levels of analysis-industry analysis (industry trends), market share analysis of top players, and company profiles, which together provide an overall view of the competitive landscape, emerging and high-growth segments of the automotive adhesives market, high-growth regions, and market drivers, restraints, and opportunities.
The report provides insights into the following points:
- Market Penetration: Comprehensive information on automotive adhesives offered by top players in the global market
- Analysis of key drivers: (Accelerating global electric vehicle adoption and battery pack assembly demand, Rising adoption of lightweight vehicle structures to drive market growth, Growing automotive production in emerging economies), restraints (Increasing costs of petrochemical-based raw materials, Technical complexity of multi-material substrate bonding), opportunities (Expansion of adhesive applications in automotive battery thermal management, Development of faster-curing adhesives for automated vehicle assembly) and challenges (Meeting long-term durability requirements under demanding vehicle conditions) influencing the growth of automotive adhesives market
- Product Development/Innovation: Detailed insights on upcoming technologies, research & development activities, and new product & service launches in the automotive adhesives market
- Market Development: Comprehensive information about lucrative emerging markets-the report analyzes the market for automotive adhesives across regions.
- Market Diversification: Exhaustive information about new products, untapped regions, and recent developments in the global automotive adhesives market
- Competitive Assessment: In-depth assessment of market shares, strategies, products, and manufacturing capabilities of leading players in the automotive adhesives market
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKETS COVERED AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS OF STUDY
- 1.3.3 MARKET DEFINITION AND INCLUSIONS, BY VEHICLE TYPE
- 1.3.4 MARKET DEFINITION AND INCLUSIONS, BY RESIN TYPE
- 1.3.5 MARKET DEFINITION AND INCLUSIONS, BY APPLICATION
- 1.3.6 YEARS CONSIDERED
- 1.3.7 CURRENCY CONSIDERED
- 1.3.8 UNIT CONSIDERED
- 1.4 STAKEHOLDERS
- 1.5 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN AUTOMOTIVE ADHESIVES MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN AUTOMOTIVE ADHESIVES MARKET
- 3.2 AUTOMOTIVE ADHESIVES MARKET, BY VEHICLE TYPE AND REGION
- 3.3 AUTOMOTIVE ADHESIVES MARKET, BY APPLICATION
- 3.4 AUTOMOTIVE ADHESIVES MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Accelerating global electric vehicle adoption and battery pack assembly demand
- 4.2.1.2 Rising adoption of lightweight vehicle structures
- 4.2.1.3 Growing automotive production in emerging economies
- 4.2.2 RESTRAINTS
- 4.2.2.1 Increasing costs of petrochemical-based raw materials
- 4.2.2.2 Technical complexity of multi-material substrate bonding
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Expansion of adhesive applications in automotive battery thermal management
- 4.2.3.2 Development of faster-curing adhesives for automated vehicle assembly
- 4.2.4 CHALLENGES
- 4.2.4.1 Meeting long-term durability requirements under demanding vehicle conditions
- 4.2.1 DRIVERS
- 4.3 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.3.1 INTERCONNECTED MARKETS
- 4.3.2 CROSS-SECTOR OPPORTUNITIES
- 4.4 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
- 4.4.1 KEY MOVES AND STRATEGIC FOCUS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 THREAT OF SUBSTITUTES
- 5.1.3 BARGAINING POWER OF SUPPLIERS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC OUTLOOK
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECAST FOR MAJOR ECONOMIES
- 5.2.3 TRENDS IN GLOBAL AUTOMOTIVE INDUSTRY
- 5.3 SUPPLY CHAIN ANALYSIS
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 PRICING ANALYSIS
- 5.5.1 AVERAGE SELLING PRICE OF AUTOMOTIVE ADHESIVES OFFERED BY KEY PLAYERS, BY APPLICATION, 2025
- 5.5.2 AVERAGE SELLING PRICE TREND OF AUTOMOTIVE ADHESIVES, BY REGION, 2023-2031
- 5.6 TRADE ANALYSIS
- 5.6.1 IMPORT SCENARIO (HS CODE 3506)
- 5.6.2 EXPORT SCENARIO (HS CODE 3506)
- 5.7 KEY CONFERENCES & EVENTS IN 2025-2026
- 5.8 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.9 INVESTMENT AND FUNDING SCENARIO
- 5.10 CASE STUDY ANALYSIS
- 5.10.1 STRUCTURAL ADHESIVE BONDING FOR LIGHTWEIGHT AUTOMOTIVE CHASSIS
- 5.10.2 ADVANCED ADHESIVE SEALING FOR ELECTROHYDRAULIC AUTOMOTIVE SUSPENSION SYSTEMS
- 5.11 IMPACT OF 2025 US TARIFF - AUTOMOTIVE ADHESIVES MARKET
- 5.11.1 INTRODUCTION
- 5.11.2 KEY TARIFF RATES
- 5.11.3 PRICE IMPACT ANALYSIS
- 5.11.4 IMPACT ON COUNTRY/REGION
- 5.11.4.1 US
- 5.11.4.2 Europe
- 5.11.4.3 Asia Pacific
- 5.11.5 IMPACT ON APPLICATIONS
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.1.1 NANOCOMPOSITE-ENHANCED ADHESIVE TECHNOLOGY
- 6.1.2 STIMULI-RESPONSIVE (SMART) ADHESIVE TECHNOLOGY
- 6.1.3 THERMALLY CONDUCTIVE STRUCTURAL ADHESIVE TECHNOLOGY FOR EV BATTERY SYSTEMS
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 DIGITAL TWIN AND AI-DRIVEN ADHESIVE FORMULATION TECHNOLOGY
- 6.2.2 AUTOMATED ROBOTIC ADHESIVE DISPENSING SYSTEMS
- 6.2.3 BIO-BASED ADHESIVE FEEDSTOCK TECHNOLOGY
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 SOLID-STATE BATTERY (SSB) TECHNOLOGY
- 6.4 TECHNOLOGY/PRODUCT ROADMAP
- 6.4.1 SHORT-TERM (2025-2027) | FORMULATION OPTIMIZATION & REGULATORY COMPLIANCE
- 6.4.2 MID-TERM (2027-2030) | PERFORMANCE ENHANCEMENT & MULTI-FUNCTIONALITY
- 6.4.3 LONG-TERM (2030-2035+) | SUSTAINABILITY, SMART ADHESIVES & DIGITAL INTEGRATION
- 6.5 PATENT ANALYSIS
- 6.5.1 APPROACH
- 6.5.2 DOCUMENT TYPES
- 6.5.3 TOP APPLICANTS
- 6.5.4 JURISDICTION ANALYSIS
- 6.6 IMPACT OF AI/GEN AI ON AUTOMOTIVE ADHESIVES MARKET
- 6.6.1 TOP USE CASES AND MARKET POTENTIAL
- 6.6.2 BEST PRACTICES IN AUTOMOTIVE ADHESIVES PROCESSING
- 6.6.3 CASE STUDIES OF AI IMPLEMENTATION IN AUTOMOTIVE ADHESIVES MARKET
- 6.6.4 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.6.5 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN AUTOMOTIVE ADHESIVES MARKET
7 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 7.1 DECISION-MAKING PROCESS
- 7.2 KEY STAKEHOLDERS AND BUYING CRITERIA
- 7.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 7.2.2 BUYING CRITERIA
- 7.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 7.4 UNMET NEEDS IN VARIOUS APPLICATIONS
8 SUSTAINABILITY AND REGULATORY LANDSCAPE
- 8.1 REGIONAL REGULATIONS AND COMPLIANCE
- 8.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 8.1.2 INDUSTRY STANDARDS
- 8.2 SUSTAINABILITY IMPACT AND REGULATORY POLICY INITIATIVES
- 8.2.1 SAFETY PROTOCOLS
- 8.2.2 SUSTAINABLE DEVELOPMENT
- 8.2.3 STANDARDIZATION
- 8.3 CERTIFICATIONS, LABELING, AND ECO-STANDARDS
9 AUTOMOTIVE ADHESIVES MARKET, BY RESIN TYPE
- 9.1 INTRODUCTION
- 9.2 POLYURETHANE
- 9.2.1 RISING DEMAND FOR FLEXIBLE AND DURABLE BONDING
- 9.3 EPOXY
- 9.3.1 INCREASING REQUIREMENTS FOR HIGH-STRENGTH STRUCTURAL BONDING
- 9.4 ACRYLICS
- 9.4.1 GROWING NEED FOR RAPID BOND FORMATION
- 9.5 SILICONE
- 9.5.1 INCREASING THERMAL AND ENVIRONMENTAL PERFORMANCE REQUIREMENTS
- 9.6 SMP
- 9.6.1 RISING DEMAND FOR FLEXIBLE ADHESIVES WITH LOWER EMISSIONS
- 9.7 MMA
- 9.7.1 GROWING ADOPTION OF COMPOSITE COMPONENTS
- 9.8 OTHER RESIN TYPES
10 AUTOMOTIVE ADHESIVES MARKET, BY VEHICLE TYPE
- 10.1 INTRODUCTION
- 10.2 PASSENGER CAR
- 10.2.1 GROWING DEMAND FOR ADVANCED VEHICLE FEATURES
- 10.3 LCVS
- 10.3.1 EXPANSION OF LAST-MILE DELIVERY FLEETS
- 10.4 TRUCKS
- 10.4.1 INCREASING FLEET MODERNIZATION AND HEAVY-DUTY VEHICLE RELIABILITY
- 10.5 BUSES
- 10.5.1 FLEET ELECTRIFICATION AND LIGHTWEIGHT BUS CONSTRUCTION
- 10.6 AFTERMARKET
- 10.6.1 AGING VEHICLE PARC AND LONGER OWNERSHIP PERIODS
11 AUTOMOTIVE ADHESIVES MARKET, BY APPLICATION
- 11.1 INTRODUCTION
- 11.2 BODY-IN-WHITE (BIW)
- 11.2.1 GROWING ADOPTION OF LIGHTWEIGHT BODY CONSTRUCTION
- 11.3 PAINTSHOP
- 11.3.1 INCREASING USE OF SEAM SEALING AND HEM BONDING
- 11.4 ASSEMBLY
- 11.4.1 RISING ADOPTION OF DIRECT COMPONENT BONDING
- 11.5 POWERTRAIN
- 11.5.1 EXPANSION OF BATTERY BONDING AND THERMAL MANAGEMENT APPLICATIONS
12 AUTOMOTIVE ADHESIVES MARKET, BY REGION
- 12.1 INTRODUCTION
- 12.2 ASIA PACIFIC
- 12.2.1 CHINA
- 12.2.1.1 Growing industrial activities to drive market
- 12.2.2 INDIA
- 12.2.2.1 Rapid industrialization to drive demand
- 12.2.3 JAPAN
- 12.2.3.1 Continued advancement of hybrid vehicle platforms to drive market
- 12.2.4 SOUTH KOREA
- 12.2.4.1 Growth of electric vehicle production to fuel demand
- 12.2.5 THAILAND
- 12.2.5.1 Increasing production of commercial vehicles to fuel market
- 12.2.6 INDONESIA
- 12.2.6.1 Greater emphasis on vehicle durability to fuel demand
- 12.2.7 MALAYSIA
- 12.2.7.1 Growth in premium vehicle assembly to drive demand
- 12.2.1 CHINA
- 12.3 NORTH AMERICA
- 12.3.1 US
- 12.3.1.1 Strong industrial infrastructure to fuel growth
- 12.3.2 CANADA
- 12.3.2.1 Focus on advanced research & development to drive demand
- 12.3.3 MEXICO
- 12.3.3.1 Expansion of vehicle export manufacturing to drive demand
- 12.3.1 US
- 12.4 EUROPE
- 12.4.1 GERMANY
- 12.4.1.1 Strong automotive sector to propel market
- 12.4.2 FRANCE
- 12.4.2.1 Increasing emphasis on vehicle interior design to propel growth
- 12.4.3 UK
- 12.4.3.1 Expansion of premium and luxury vehicle manufacturing to drive demand
- 12.4.4 SPAIN
- 12.4.4.1 Development of advanced vehicle component production to drive market
- 12.4.5 RUSSIA
- 12.4.5.1 Modernization of automotive production capabilities to fuel demand
- 12.4.6 TURKEY
- 12.4.6.1 Strengthening regional automotive supply chains to drive market
- 12.4.1 GERMANY
- 12.5 MIDDLE EAST & AFRICA
- 12.5.1 SOUTH AFRICA
- 12.5.1.1 Increasing adoption of advanced powertrain assembly methods to fuel growth
- 12.5.2 IRAN
- 12.5.2.1 Rising replacement of conventional joining methods to fuel market
- 12.5.1 SOUTH AFRICA
- 12.6 SOUTH AMERICA
- 12.6.1 BRAZIL
- 12.6.1.1 Economic momentum drives adoption across sectors
- 12.6.2 ARGENTINA
- 12.6.2.1 Increasing adoption of lightweight vehicle components to drive market
- 12.6.1 BRAZIL
13 COMPETITIVE LANDSCAPE
- 13.1 INTRODUCTION
- 13.2 KEY PLAYER STRATEGIES/RIGHT TO WIN, JANUARY 2021-JULY 2026
- 13.2.1 STRATEGIES ADOPTED BY KEY AUTOMOTIVE ADHESIVE MANUFACTURERS, JANUARY 2021-JULY 2026
- 13.3 MARKET SHARE ANALYSIS, 2025
- 13.4 REVENUE ANALYSIS, 2023-2025
- 13.5 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 13.5.1 STARS
- 13.5.2 EMERGING LEADERS
- 13.5.3 PERVASIVE PLAYERS
- 13.5.4 PARTICIPANTS
- 13.5.5 OMPANY FOOTPRINT: KEY PLAYERS, 2025
- 13.5.5.1 Company footprint
- 13.5.5.2 Region footprint
- 13.5.5.3 Vehicle type footprint
- 13.5.5.4 Resin type footprint
- 13.5.5.5 Application footprint
- 13.6 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 13.6.1 PROGRESSIVE COMPANIES
- 13.6.2 RESPONSIVE COMPANIES
- 13.6.3 DYNAMIC COMPANIES
- 13.6.4 STARTING BLOCKS
- 13.6.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES
- 13.6.5.1 Detailed list of key startups/SMES
- 13.6.5.2 Competitive benchmarking of key startups/SMEs
- 13.7 BRAND/PRODUCT COMPARISON ANALYSIS
- 13.8 COMPANY VALUATION AND FINANCIAL METRICS
- 13.9 COMPETITIVE SCENARIO
- 13.9.1 PRODUCT LAUNCHES
- 13.9.2 DEALS
- 13.9.3 EXPANSIONS
- 13.9.4 OTHER DEVELOPMENTS
14 COMPANY PROFILES
- 14.1 KEY PLAYERS
- 14.1.1 HENKEL AG & CO. KGAA
- 14.1.1.1 Business overview
- 14.1.1.2 Products/Solutions/Services offered
- 14.1.1.3 Recent developments
- 14.1.1.3.1 Product Launches
- 14.1.1.3.2 Expansions
- 14.1.1.3.3 Other Developments
- 14.1.1.4 MnM view
- 14.1.1.4.1 Key strengths
- 14.1.1.4.2 Strategic choices
- 14.1.1.4.3 Weaknesses and competitive threats
- 14.1.2 SIKA AG
- 14.1.2.1 Business overview
- 14.1.2.2 Products/Solutions/Services offered
- 14.1.2.3 Recent developments
- 14.1.2.3.1 Product Launches
- 14.1.2.3.2 Deals
- 14.1.2.4 MnM view
- 14.1.2.4.1 Key Strengths
- 14.1.2.4.2 Strategic choices
- 14.1.2.4.3 Weaknesses and competitive threats
- 14.1.3 3M COMPANY
- 14.1.3.1 Business overview
- 14.1.3.2 Products/Solutions/Services offered
- 14.1.3.3 MnM view
- 14.1.3.3.1 Key strengths
- 14.1.3.3.2 Strategic choices
- 14.1.3.3.3 Weaknesses and competitive threats
- 14.1.4 ARKEMA S.A.
- 14.1.4.1 Business overview
- 14.1.4.2 Products/Solutions/Services offered
- 14.1.4.3 Recent developments
- 14.1.4.3.1 Product Launches
- 14.1.4.3.2 Deals
- 14.1.4.4 MnM view
- 14.1.4.4.1 Key strengths
- 14.1.4.4.2 Strategic choices
- 14.1.4.4.3 Weaknesses and competitive threats
- 14.1.5 H.B. FULLER COMPANY
- 14.1.5.1 Business overview
- 14.1.5.2 Products/Solutions/Services offered
- 14.1.5.3 MnM view
- 14.1.5.3.1 Key strengths
- 14.1.5.3.2 Strategic choices
- 14.1.5.3.3 Weaknesses and competitive threats
- 14.1.6 DUPONT DE NEMOURS, INC.
- 14.1.6.1 Business overview
- 14.1.6.2 Products/Solutions/Services offered
- 14.1.6.3 Recent developments
- 14.1.6.3.1 Expansions
- 14.1.6.3.2 Other developments
- 14.1.7 PPG INDUSTRIES, INC.
- 14.1.7.1 Business overview
- 14.1.7.2 Products/Solutions/Services offered
- 14.1.8 HUNTSMAN INTERNATIONAL LLC
- 14.1.8.1 Business overview
- 14.1.8.2 Products/Solutions/Services offered
- 14.1.8.3 Recent developments
- 14.1.8.3.1 Product Launches
- 14.1.8.3.2 Other developments
- 14.1.9 PARKER-HANNIFIN CORPORATION
- 14.1.9.1 Business overview
- 14.1.9.2 Products/Solutions/Services offered
- 14.1.10 ILLINOIS TOOL WORKS INC.
- 14.1.10.1 Business overview
- 14.1.10.2 Products/Solutions/Services offered
- 14.1.10.3 Recent developments
- 14.1.10.3.1 Product Launches
- 14.1.1 HENKEL AG & CO. KGAA
- 14.2 STARTUP/SMES
- 14.2.1 UNISEAL, INC.
- 14.2.2 CATTIE ADHESIVES
- 14.2.3 SUNSTAR ENGINEERING
- 14.2.4 DELO INDUSTRIAL ADHESIVES
- 14.2.5 MASTER BOND INC.
- 14.2.6 PERMABOND
- 14.2.7 DYMAX CORPORATION
- 14.2.8 THREEBOND INTERNATIONAL
- 14.2.9 METLOK PRIVATE LIMITED
- 14.2.10 WEICON GMBH & CO. KG
- 14.2.11 EMS-CHEMIE HOLDING AG
- 14.2.12 JOWAT SE
- 14.2.13 KLEIBERIT SE & CO. KG
- 14.2.14 HERNON MANUFACTURING
- 14.2.15 GUANGDONG SINO-ADHESIVE NEW MATERIAL TECHNOLOGY CO., LTD.
15 RESEARCH METHODOLOGY
- 15.1 RESEARCH DATA
- 15.1.1 SECONDARY DATA
- 15.1.1.1 Key data from secondary sources
- 15.1.2 PRIMARY DATA
- 15.1.2.1 Key data from primary sources
- 15.1.2.2 Primary interview - demand side and supply side
- 15.1.2.3 Breakdown of primary interviews
- 15.1.2.4 Key industry insights
- 15.1.1 SECONDARY DATA
- 15.2 MARKET SIZE ESTIMATION
- 15.2.1 BOTTOM-UP APPROACH
- 15.2.2 TOP-DOWN APPROACH
- 15.3 GROWTH FORECAST
- 15.3.1 SUPPLY SIDE
- 15.3.2 DEMAND SIDE
- 15.4 DATA TRIANGULATION
- 15.5 FACTOR ANALYSIS
- 15.6 RESEARCH ASSUMPTIONS
- 15.7 RESEARCH LIMITATIONS
- 15.8 RISK ASSESSMENT
16 APPENDIX
- 16.1 DISCUSSION GUIDE
- 16.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 16.3 CUSTOMIZATION OPTIONS
- 16.4 RELATED REPORTS
- 16.5 AUTHOR DETAILS


