

|
시장보고서
상품코드
2158072
위치 센서 시장 규모, 점유율 및 동향 : 유형, 신호, 기술별 - 세계 예측(-2032년)Position Sensor Market Size, Share and Trends by Type (Linear, Rotary, Proximity, Photoelectric, 3D Sensor), Signal ( Digital, Analog), Technology (Capacitive, Inductive, Optical, Magnetic, Ultrasonic) - Global Forecast to 2032 |
||||||

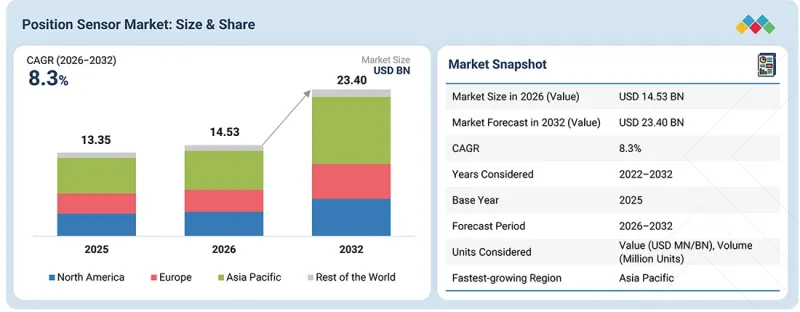
MarketsandMarkets에 따르면 위치 센서 시장은 2026년 145억 3,000만 달러에서 2032년까지 234억 달러로 연평균 성장률(CAGR) 8.3%를 기록하며 확대될 것으로 전망됩니다.
이 시장은 자동차, 제조, 항공우주·방위, 의료, 포장, 전자 등 각 분야에서 산업 자동화, 전기자동차, 로봇 공학 및 첨단 모션 제어 시스템의 도입이 확대되는 것을 배경으로, 예측 기간 중 강력한 성장을 보일 것으로 전망됩니다. 위치 센서는 직선, 회전, 각도 및 물체의 위치에 대한 정확한 피드백을 제공하기 위해 점점 더 많이 활용되고 있으며, 기계, 액추에이터, 모터, 차량 시스템 및 자동화 설비의 정밀한 제어를 가능하게 하고 있습니다. 인더스트리 4.0, 스마트 제조, 예측 유지보수 및 커넥티드 기기에 대한 관심이 높아짐에 따라 신뢰성이 높고 정밀한 위치 감지에 대한 수요는 더욱 증가하고 있습니다. 각 제조사들은 정밀도, 응답 시간, 내구성, 소형화 및 내환경성을 향상시킨 자기식, 유도식, 광학식, 홀 효과식, 근접식 및 3D 위치 센서의 개발을 점점 더 추진하고 있습니다. 위치 센서와 디지털 인터페이스, PLC, IoT 플랫폼 및 지능형 제어 시스템과의 통합을 통해 그 기능성이 확대되어 실시간 위치 모니터링 및 모션 제어가 가능해졌습니다. TDK-Micronas사의 3D 홀 효과 센서 등 최근 동향은 자동차 및 산업용 애플리케이션을 위한 유연하고 고정밀하며 견고한 센싱 기술에 대한 업계의 집중을 보여주고 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2021-2032년 |
| 기준 연도 | 2025 |
| 예측 기간 | 2026-2032년 |
| 산정 단위 | 금액(10억 달러) |
| 부문 | 유형, 신호, 기술, 지역별 |
| 대상 지역 | 북미, 유럽, 아시아태평양(APAC), 기타 지역(RoW) |
또한 전동 모빌리티, 로봇 공학, 자동화 생산, 스마트 팩토리 및 첨단 산업용 장비에 대한 투자 증가가 시장 확산을 가속화하고 있습니다. 정밀도 향상, 가동 신뢰성 향상, 기계적 마모 감소, 안전성 향상 및 정밀한 모션 제어와 같은 장기적인 이점으로 인해 위치 센서는 현대의 자동차 및 산업용 분야에서 점점 더 중요해질 것으로 예상됩니다.
"2032년까지 근접 센서 부문이 가장 큰 시장 점유율을 차지할 전망"
유형별로는 산업용 및 자동차용 애플리케이션에서 비접촉 감지 및 위치 모니터링을 위한 근접 센서의 광범위한 활용에 힘입어, 2032년까지 근접 센서 부문이 가장 큰 시장 점유율을 차지할 것으로 예상됩니다. 근접 센서는 물리적 접촉 없이 물체의 유무나 움직임을 감지하므로 공작 기계, 자재 취급, 조립 라인, 로봇 공학, 자동차 시스템, 포장 장비, 공정 자동화 등의 용도에 적합합니다. 근접 센서는 높은 신뢰성의 감지, 긴 수명, 빠른 응답 속도, 그리고 가혹한 작동 조건에 대한 내성이 중요한 분야에서 점점 더 많이 채택되고 있습니다. 유도식, 정전용량식, 자기식 및 기타 근접 감지 기술을 통해 다양한 작동 환경에서 금속 및 비금속 물체를 감지할 수 있습니다. 기계적 접촉 없이 작동하는 특성 덕분에 마모와 유지보수 부담을 줄이면서 신뢰성 높은 연속 운전을 실현합니다. 또한 스마트 센서, IO-Link 연결, 콤팩트한 설계 및 내환경성 향상과 같은 기술 발전으로 인해 근접 센서와 자동 제어·감시 시스템 간의 통합이 진행되고 있습니다. 산업 자동화, 로봇 공학, 스마트 제조, 자동차 생산 및 커넥티드 기기에 대한 투자 확대에 힘입어 근접 센서의 도입이 더욱 가속화되고, 시장내 우위성이 유지될 것으로 예상됩니다.
"2026-2032년에 비접촉형 부문이 가장 높은 연평균 성장률(CAGR)을 보일 것으로 예측됩니다."
접촉 방식별로 보면 자동차, 산업 자동화, 로봇 공학 및 기타 용도 분야에서 내구성, 정밀도 및 유지보수 효율이 뛰어난 위치 감지에 대한 수요가 증가함에 따라 비접촉형 부문이 예측 기간 중 가장 높은 성장률을 보일 것으로 전망됩니다. 비접촉형 자기식, 유도식, 광학식 및 홀 효과식 위치 센서의 채택 확대는 물리적 접촉 없이 직선 운동, 각도 운동 및 회전 운동을 측정할 수 있는 능력 덕분에 해당 부문의 성장을 가속화하고 있습니다. 또한 고정밀 감지, 3D 자기 감지, 미아 자기장에 대한 내성, 디지털 인터페이스 및 기능 안전 기능의 발전으로 인해 전기자동차(EV), 스티어링 시스템, 액추에이터, 공작 기계, 로봇 시스템, 자동 생산 설비에서 비접촉식 위치 센서의 활용이 확대되고 있습니다.
"예측 기간 중 아시아태평양이 최대 지역 시장이 될 전망"
지역별로 보면 아시아태평양은 중국, 일본, 한국, 인도 등 국가들의 급속한 산업 자동화 발전, 자동차 및 전기자동차(EV) 생산 확대, 로봇 공학 도입, 스마트 제조에 대한 투자 증가에 힘입어 예측 기간 중 위치 센서 시장에서 최대 점유율을 유지할 것으로 예상됩니다. 이 지역의 강력한 제조 및 전자 생태계와 정밀 센싱에 대한 수요 증가가 맞물려, 자동차, 산업 자동화, 로봇 공학, 전자, 공작 기계 등 각 분야에서 위치 센서의 도입을 촉진하고 있습니다. EV의 파워트레인, 스티어링 시스템, 액추에이터, 자동 생산 설비, 로봇 시스템에서 위치 센서의 채택 확대가 이 지역의 수요를 더욱 부추기고 있습니다. 또한 공장 자동화, 커넥티드 제조, 첨단 로봇 공학 및 지능형 제어 시스템에 대한 투자가 자기식, 유도식, 광학식, 근접식 및 기타 첨단 위치 감지 기술에 새로운 기회를 창출하고 있습니다. 제조 활동의 확대, 자동차의 전동화, 스마트 팩토리 추진, 그리고 센싱 및 자동화 분야의 기술 발전으로 인해 위치 센서의 채택이 더욱 가속화되어 아시아태평양의 시장 성장이 지속적으로 지원될 것으로 예상됩니다.
1차 조사 내역
위치 센서 시장에서 사업을 운영하는 주요 조직의 CEO, 마케팅 이사, 혁신·기술 이사 등 다양한 직책의 임원들을 대상으로 상세한 인터뷰를 시행했습니다.
- 기업 규모별: Tier 1-38%, Tier 2-28%, Tier 3-34%
- 직책별: C레벨 임원-40%, 이사-30%, 기타-30%
- 지역별: 북미-35%, 유럽-35%, 아시아태평양-20%, 기타 지역-10%
참고: 2025년 기준 총매출을 바탕으로 기업을 3개의 티어로 분류했습니다. Tier 3: 매출 1억 달러 미만, Tier 2: 매출 1억 달러 이상 10억 달러 미만, Tier 1: 매출 10억 달러 이상. 기타 직책에는 제품, 영업, 마케팅 매니저 등이 포함됩니다. ‘기타 지역(RoW)’에는 중동 및 아프리카, 남미가 포함됩니다.
이 기업은 다양한 용도에서 위치 센서의 정확도, 응답 시간, 신뢰성, 내구성, 소형화 및 통합 능력을 지속적으로 향상시킴으로써 경쟁하고 있습니다. 전략적 중점은 첨단 자기식, 유도식, 광학식, 정전용량식, 홀 효과식, 근접식 및 3D 위치 감지 기술의 개발에 맞춰져 있습니다. 시장 참여 기업은 자동차, 산업용 자동화, 로봇공학, 항공우주·방위, 헬스케어, 전자, 제조 등 다양한 산업 분야를 대상으로 맞춤형 고성능 솔루션을 우선시하고 있습니다. 또한 제어 시스템 및 연결 기기와의 원활한 통합은 물론, 고정밀 동작 감지, 실시간 위치 피드백, 비접촉 동작, 내환경성, 기능 안전성 향상에도 중점을 두고 있습니다. 첨단 센싱 기술, 디지털 인터페이스, 스마트 센서, IoT 연결, 자동화, 차세대 모션 제어 솔루션에 대한 지속적인 투자와 더불어 OEM, 시스템 통합사업자, 산업용 장비 제조업체와의 협력을 통해 경쟁이 심화되고, 전 세계 위치 센서의 보급이 가속화될 것으로 예상됩니다.
본 조사에서는 시장의 주요 기업에 대해 상세한 경쟁 분석을 수행하고, 각 기업의 프로필, 최근 동향, 제품 포트폴리오, 기술력 및 주요 시장 전략을 소개하고 있습니다.
조사 범위
본 위치 센서 시장 관련 보고서에서는 유형, 접촉 방식, 신호 출력, 기술, 연결 방식, 최종사용자 산업 및 지역을 기반으로 한 상세한 분석을 제시하고 있습니다. 유형별로는 시장이 선형 센서, 로터리 센서, 근접 센서, 광전 센서 및 3D 센서로 분류됩니다. 접촉 방식별로는 시장이 비접촉형 센서와 접촉형 센서로 구성됩니다. 신호 출력별로는 시장이 디지털 출력형과 아날로그 출력형으로 분류됩니다. 기술별로는 정전용량식, 유도식, 광학식, 자기식, 초음파식, 압전식 기술이 포함됩니다. 연결 방식별로는 유선식과 무선식으로 분류됩니다. 용도별로는 공작기계, 로봇 공학, 모션 시스템, 자재 취급, 시험 장비 및 기타 용도로 분류됩니다. 최종사용자 산업별로는 제조, 자동차, 항공우주·방위, 포장, 헬스케어, 소비자 가전 및 기타 최종사용자 산업으로 분류됩니다. 지역별 분석에는 북미, 유럽, 아시아태평양 및 기타 지역(RoW)이 포함되어 있으며, 주요 시장의 수요 패턴, 기술 도입 현황, 성장 요인 및 업계 동향을 평가할 수 있습니다.
이 보고서를 구매해야 하는 이유
이 보고서는 시장 전체 매출 및 각 하위 부문의 매출에 대해 가장 정확한 추정치를 제공함으로써, 이 시장의 선도 기업과 신규 진입 기업을 지원합니다. 또한 이해관계자가 경쟁 구도를 이해하고, 더 심층 인사이트를 얻어 자사의 비즈니스를 더 나은 위치로 이끌며, 적절한 시장 진입 전략을 수립하는 데 도움이 됩니다. 더불어 이 보고서는 위치 센서 시장의 동향을 파악하는 데 도움이 되며, 주요 시장 촉진요인, 제약, 과제 및 기회에 대한 정보를 제공합니다.
이 보고서를 구매할 때의 주요 이점
- 위치 센서 시장의 성장에 영향을 미치는 주요 촉진요인(인더스트리 4.0 기술 채택 확대, 자동차 산업에서의 위치 센서 채택 증가), 제약 요인(높은 소유 비용), 기회(IoT 기기에 대한 위치 센서 통합, 로봇 공학 및 자동화 기술의 발전), 그리고 과제(위치 센서의 측정 범위, 성능, 정확도 측면에서의 운영상 제한)에 대한 분석
- 제품 개발 및 혁신: 시장의 향후 기술, 연구개발 활동, 신제품 출시에 대한 상세 인사이트
- 시장 개발: 다양한 지역에 걸친 시장 분석을 통해 수익성 높은 시장에 대한 포괄적인 정보를 제공합니다
- 시장 다각화: 시장의 신제품 및 서비스, 미개발 지역, 최근 동향 및 투자에 대한 포괄적인 정보
- 경쟁 분석: 주요 기업의 시장 점유율, 성장 전략, 서비스 제공에 대한 상세한 평가
자주 묻는 질문
목차
제1장 서론
제2장 요약
제3장 주요 인사이트
- 위치 센서 시장에서 사업자에게 매력적인 기회
- 위치 센서 시장: 유형별
- 위치 센서 시장: 접점 유형별
- 위치 센서 시장: 신호 출력별
- 위치 센서 시장: 연결 방식별
- 위치 센서 시장: 기술별
- 위치 센서 시장: 용도별
- 위치 센서 시장: 최종 용도 산업별
- 북미 위치 센서 시장: 최종 용도 산업 및 국가별
- 위치 센서 시장: 국가별
제4장 시장 개요
- 시장 역학
- 촉진요인
- 억제요인
- 기회
- 과제
- 미충족 수요와 미개발 분야
- 상호 연관된 시장 및 부문 간 기회
- Tier 1/2/3 주요 기업의 전략적 움직임
제5장 업계 동향
- Porter's Five Forces 분석
- 경쟁 기업 간의 적대적 관계
- 공급업체의 협상력
- 구매자의 협상력
- 대체품의 위협
- 신규 진입자의 위협
- 거시경제 전망
- GDP 동향 및 전망
- 세계 제조업 동향
- 세계 자동차 및 전기자동차 산업의 동향
- 공급망 분석
- 생태계 분석
- 가격 분석
- 위치 센서의 평균 판매 가격 동향(유형별, 2022-2025년)
- 지역별 위치 센서 평균 판매 가격 동향(2022-2025년)
- 무역 분석
- 수입 시나리오(HS 코드 9031)
- 수출 시나리오(HS 코드 9031)
- 주요 회의 및 행사(2026-2027년)
- 고객의 사업에 영향을 미치는 동향/파괴적 변화
- 투자 및 자금 조달 시나리오
- 사례 연구 분석
- 미국 관세의 영향 - 위치 센서 시장
- 주요 관세율
- 가격에 미치는 영향 분석
- 국가 및 지역에 미치는 영향
- 최종 용도 산업에 미치는 영향
제6장 기술 발전, AI의 영향, 특허, 혁신 및 향후 응용
- 주요 기술
- 유도형 센싱
- 홀 효과
- 보완 기술
- 관련 기술
- 특허 분석
- 특허 분석
- AI가 위치 센서 시장에 미치는 영향
- AI의 주요 활용 사례와 시장 잠재력
- 위치 센서 OEM 업체들이 실천하고 있는 베스트 프랙티스
- 위치 센서 시장에서의 AI 도입에 관한 사례 연구
- 상호 연관된/인접한 생태계 및 시장 참여자에 미치는 영향
- AI 통합형 위치 센서 도입에 대한 고객의 준비 현황
제7장 규제 현황
- 규제기관, 정부 기관 및 기타 조직
- 업계 표준
- IEC 61326-1
- ANSI/ISA-75.25.01
- IEC 60947-5-2
- EN 61496-1
- NEMA ICS 5
- IEC 60947-5-6
제8장 고객 현황 및 구매 행동
- 의사결정 과정
- 주요 이해관계자와 구매 기준
- 구매 과정의 주요 이해관계자
- 구매 기준
- 도입 장벽 및 사내 과제
- 다양한 최종사용자의 충족되지 않은 요구
제9장 위치 센서 시장: 유형별
- 선형 센서
- 로터리 센서
- 근접 센서
- 광전 센서
- 3D 센서
제10장 위치 센서 시장: 접촉 유형별
- 비접촉식
- 접촉식
제11장 위치 센서 시장: 신호 출력별
- 디지털
- 아날로그
제12장 위치 센서 시장: 기술별
- 정전용량식
- 유도식
- 광학식
- 자기식
- 초음파식
- 압전식
제13장 위치 센서 시장: 연결 방식별
- 유선
- 무선
제14장 위치 센서 시장: 용도별
- 공작기계
- 로봇 공학
- 모션 시스템
- 자재 취급 장비
- 시험 장비
- 기타 용도
제15장 위치 센서 시장: 최종 용도 산업별
- 제조
- 자동차
- 항공우주·방위
- 포장
- 헬스케어
- 소비자용 전자기기
- 기타 최종 용도 산업
제16장 위치 센서 시장: 지역별
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 영국
- 독일
- 프랑스
- 이탈리아
- 기타 유럽
- 아시아태평양
- 중국
- 일본
- 한국
- 인도
- 기타 아시아태평양
- 기타 지역
- 중동
- 남미
- 아프리카
제17장 경쟁 현황
- 개요
- 주요 진입 기업의 전략/강점, 2023-2026년
- 수익 분석, 2021-2025년
- 시장 점유율 분석, 2025년
- 기업 평가 및 재무 지표
- 브랜드 비교
- 기업 평가 매트릭스: 주요 기업, 2025년
- 스타 기업
- 신흥 리더
- 광범위한 영향력을 가진 기업
- 진출 기업
- 기업의 사업 전개: 주요 기업, 2025년
- 기업 평가 매트릭스: 스타트업/중소기업, 2025년
- 선도적인 기업
- 대응력이 뛰어난 기업
- 역동적인 기업
- 출발점
- 경쟁사 벤치마킹: 스타트업/중소기업, 2025년
- 경쟁 시나리오
- 신제품 출시
제18장 기업 개요
- 주요 기업
- HONEYWELL INTERNATIONAL INC.
- TDK CORPORATION
- STMICROELECTRONICS
- AMPHENOL CORPORATION
- SICK AG
- TE CONNECTIVITY
- TEXAS INSTRUMENTS INCORPORATED
- AMS-OSRAM AG
- ANALOG DEVICES, INC.
- CTS CORPORATION
- INFINEON TECHNOLOGIES AG
- MICROCHIP TECHNOLOGY INC.
- VISHAY INTERTECHNOLOGY, INC.
- NOVOTECHNIK U.S. INC.
- 기타 주요 기업
- BAUMER
- NXP SEMICONDUCTORS
- RENISHAW PLC
- ALLEGRO MICROSYSTEMS, INC.
- PHOENIX SENSORS
- BALLUFF AUTOMATION
- PEPPERL+FUCHS SE
- SENSOR SOLUTIONS CORP.
- ANGST+PFISTER SENSORS AND POWER AG
- ACTIVE SENSORS
- ROCKWELL AUTOMATION
제19장 조사 방법론
제20장 부록
KSA 26.11.03According to MarketsandMarkets, the position sensor market is anticipated to grow from USD 14.53 billion in 2026 to USD 23.40 billion by 2032, at a CAGR of 8.3%. The market is expected to witness strong growth during the forecast period, driven by the increasing adoption of industrial automation, electric vehicles, robotics, and advanced motion-control systems across automotive, manufacturing, aerospace & defense, healthcare, packaging, and electronics applications. Position sensors are increasingly used to provide accurate feedback on linear, rotary, angular, and object positions, enabling precise control of machines, actuators, motors, vehicle systems, and automated equipment. The growing emphasis on Industry 4.0, smart manufacturing, predictive maintenance, and connected equipment is further increasing demand for reliable and high-accuracy position sensing. Manufacturers are increasingly developing magnetic, inductive, optical, Hall-effect, proximity, and 3D position sensors with improved accuracy, response time, durability, miniaturization, and environmental resistance. The integration of position sensors with digital interfaces, PLCs, IoT platforms, and intelligent control systems is expanding their functionality and enabling real-time position monitoring and motion control. Recent developments such as TDK-Micronas' 3D Hall-effect sensors demonstrate the industry's focus on flexible, high-precision, and robust sensing for automotive and industrial applications.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2021-2032 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Units Considered | Value (USD Billion) |
| Segments | By Type, Signal, Technology and Region |
| Regions covered | North America, Europe, APAC, RoW |
Additionally, increasing investments in electric mobility, robotics, automated production, smart factories, and advanced industrial equipment are accelerating market adoption. The long-term benefits of improved accuracy, operational reliability, reduced mechanical wear, enhanced safety, and precise motion control are expected to make position sensors increasingly important across modern automotive and industrial applications.
"Proximity sensors segment to capture largest market share by 2032"
By type, the proximity sensors segment is expected to account for the largest market share by 2032, supported by the widespread use of proximity sensors for non-contact detection and position monitoring across industrial and automotive applications. Proximity sensors detect the presence, absence, or movement of objects without physical contact, making them suitable for applications such as machine tools, material handling, assembly lines, robotics, automotive systems, packaging equipment, and process automation. Proximity sensors are increasingly adopted in applications where reliable detection, long service life, fast response, and resistance to harsh operating conditions are important. Inductive, capacitive, magnetic, and other proximity-sensing technologies enable detection of metallic and non-metallic objects across diverse operating environments. Their ability to operate without mechanical contact reduces wear and maintenance requirements while supporting reliable and continuous operation. Furthermore, advancements in smart sensors, IO-Link connectivity, compact designs, and enhanced environmental resistance are improving the integration of proximity sensors with automated control and monitoring systems. Growing investments in industrial automation, robotics, smart manufacturing, automotive production, and connected equipment are expected to further accelerate the adoption of proximity sensors and support their continued market dominance.
"Non-contact segment to exhibit highest CAGR between 2026 and 2032"
By contact type, the non-contact type segment is projected to grow at the highest rate during the forecast period, driven by increasing demand for durable, accurate, and maintenance-efficient position sensing across automotive, industrial automation, robotics, and other applications. Rising adoption of non-contact magnetic, inductive, optical, and Hall-effect position sensors is accelerating segmental growth due to their ability to measure linear, angular, and rotary movement without physical contact. Additionally, advancements in high-accuracy sensing, 3D magnetic sensing, stray-field robustness, digital interfaces, and functional-safety capabilities are expanding the use of non-contact position sensors in EVs, steering systems, actuators, machine tools, robotic systems, and automated production equipment.
"Asia Pacific to be largest regional market during forecast period"
By region, Asia Pacific is expected to maintain the largest share of the position sensor market during the forecast period, supported by rapid industrial automation, expanding automotive and electric vehicle production, robotics adoption, and increasing investments in smart manufacturing across countries such as China, Japan, South Korea, and India. The region's strong manufacturing and electronics ecosystem, coupled with growing demand for precision sensing, is supporting the deployment of position sensors across automotive, industrial automation, robotics, electronics, and machine tools. Rising adoption of position sensors in EV powertrains, steering systems, actuators, automated production equipment, and robotic systems is further strengthening regional demand. Additionally, investments in factory automation, connected manufacturing, advanced robotics, and intelligent control systems are creating opportunities for magnetic, inductive, optical, proximity, and other advanced position-sensing technologies. Growing manufacturing activities, vehicle electrification, smart-factory initiatives, and technological advancements in sensing and automation are expected to further accelerate the adoption of position sensors and support Asia Pacific's continued market growth.
Breakdown of Primaries
A variety of executives from key organizations operating in the position sensor market were interviewed in-depth, including CEOs, marketing directors, and innovation and technology directors.
- By Company Type: Tier 1 - 38%, Tier 2 - 28%, and Tier 3 - 34%
- By Designation: C-level Executives - 40%, Directors - 30%, and Others - 30%
- By Region: North America - 35%, Europe - 35, Asia Pacific - 20%, and RoW - 10%
Note: Three tiers of companies have been defined based on their total revenues as of 2025: Tier 3: revenue less than USD 100 million; Tier 2: revenue between USD 100 million and USD 1 billion; and Tier 1: revenue more than USD 1 billion. Other designations include product, sales, and marketing managers. Rest of the World (RoW) includes the Middle East, Africa, and South America.
Major players profiled in this report include Honeywell International (US), TDK Corporation (Japan), STMicroelectronics (Switzerland), Amphenol Corp. (US), SICK AG (Germany), TE Connectivity (Ireland), Texas Instruments Inc. (US), Analog Devices Inc. (US), CTS Corporation (US), and Infineon Technologies AG (Germany), among others.
These companies compete by continuously enhancing position sensor accuracy, response time, reliability, durability, miniaturization, and integration capabilities across diverse applications. Strategic emphasis is placed on developing advanced magnetic, inductive, optical, capacitive, Hall-effect, proximity, and 3D position-sensing technologies. Market participants prioritize high-performance solutions tailored for industries such as automotive, industrial automation, robotics, aerospace & defense, healthcare, electronics, and manufacturing. Strong focus is also placed on improving precise motion detection, real-time position feedback, non-contact operation, environmental resistance, and functional safety, along with seamless integration with control systems and connected equipment. Continued investments in advanced sensing technologies, digital interfaces, smart sensors, IoT connectivity, automation, and next-generation motion-control solutions, along with collaborations with OEMs, system integrators, and industrial equipment manufacturers, are expected to strengthen competition and accelerate the adoption of position sensors globally.
The study provides a detailed competitive analysis of these key players in the market, presenting their company profiles, recent developments, product portfolios, technological capabilities, and key market strategies.
Research Coverage
This report on the position sensor market presents a detailed analysis based on type, contact type, signal output, technology, connectivity, technology, end-user industry, and region. By type, the market is segmented into linear, rotary, proximity, photoelectric, and 3D sensors. By contact type, the market includes non-contact and contact sensors. By signal output, the market is segmented into digital and analog. By technology, the market includes capacitive, inductive, optical, magnetic, ultrasonic, and piezoelectric technologies. By connectivity, the market is segmented into wired and wireless. By application, the market is segmented into machine tools, robotics, motion systems, material handling, test equipment, and other applications. By end-user industry, the market is segmented into manufacturing, automotive, aerospace & defense, packaging, healthcare, consumer electronics, and other end-user industries. The regional analysis includes North America, Europe, Asia Pacific, and the Rest of the World (RoW), enabling evaluation of demand patterns, technology adoption, growth drivers, and industry trends across key markets.
Reasons to Buy the Report
The report will help leaders/new entrants in this market with information on the closest approximations of the revenue numbers for the overall market and the subsegments. This report will help stakeholders understand the competitive landscape and gain more insights to position their businesses better and plan suitable go-to-market strategies. The report also helps stakeholders understand the position sensor market's pulse and provides information on key market drivers, restraints, challenges, and opportunities.
Key Benefits of Buying the Report
- Analysis of key drivers (Increase in adoption of Industry 4.0 technologies, Rise in adoption of position sensors in automotive industry), restraints (High cost of ownership), opportunities (Integration of position sensors into IoT devices, Growth in advancements in robotics and automation), and challenges (Operational limitations in range, performance, and precision of position sensors) influencing the growth of the position sensor market
- Product Development/Innovation: Detailed insights on upcoming technologies, research & development activities, and product launches in the market
- Market Development: Comprehensive information about lucrative markets by analyzing the market across varied regions
- Market Diversification: Exhaustive information about new products/services, untapped geographies, recent developments, and investments in the market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and service offerings of leading players such as Honeywell International (US), TDK Corporation (Japan), STMicroelectronics (Switzerland), Amphenol Corp. (US), SICK AG (Germany), TE Connectivity (Ireland), Texas Instruments Inc. (US), Analog Devices Inc. (US), CTS Corporation (US), and Infineon Technologies AG (Germany), among others
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 MARKET SCOPE
- 1.3.1 MARKET SEGMENTATION AND REGIONAL SCOPE
- 1.3.2 YEARS CONSIDERED
- 1.3.3 INCLUSIONS AND EXCLUSIONS
- 1.4 CURRENCY CONSIDERED
- 1.5 UNITS CONSIDERED
- 1.6 STAKEHOLDERS
- 1.7 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN POSITION SENSOR MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN POSITION SENSOR MARKET
- 3.2 POSITION SENSOR MARKET, BY TYPE
- 3.3 POSITION SENSOR MARKET, BY CONTACT TYPE
- 3.4 POSITION SENSOR MARKET, BY SIGNAL OUTPUT
- 3.5 POSITION SENSOR MARKET, BY CONNECTIVITY
- 3.6 POSITION SENSOR MARKET, BY TECHNOLOGY
- 3.7 POSITION SENSOR MARKET, BY APPLICATION
- 3.8 POSITION SENSOR MARKET, BY END-USE INDUSTRY
- 3.9 POSITION SENSOR MARKET IN NORTH AMERICA, BY END-USE INDUSTRY AND COUNTRY
- 3.10 POSITION SENSOR MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Increasing adoption of Industry 4.0 technologies
- 4.2.1.2 Rising demand for position sensors from automotive industry
- 4.2.1.3 Growing deployment of position sensors in aerospace & defense applications
- 4.2.2 RESTRAINTS
- 4.2.2.1 High cost of ownership
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Integration of position sensor into IoT devices
- 4.2.3.2 Rapid advancements in robotics and automation technologies
- 4.2.4 CHALLENGES
- 4.2.4.1 Operational limitations in range, performance, and precision of position sensor
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER 1/2/3 PLAYERS
5 INDUSTRY TRENDS
- 5.1 INTRODUCTION
- 5.2 PORTER'S FIVE FORCES ANALYSIS
- 5.2.1 INTENSITY OF COMPETITIVE RIVALRY
- 5.2.2 BARGAINING POWER OF SUPPLIERS
- 5.2.3 BARGAINING POWER OF BUYERS
- 5.2.4 THREAT OF SUBSTITUTES
- 5.2.5 THREAT OF NEW ENTRANTS
- 5.3 MACROECONOMIC OUTLOOK
- 5.3.1 INTRODUCTION
- 5.3.2 GDP TRENDS AND FORECAST
- 5.3.3 TRENDS IN GLOBAL MANUFACTURING INDUSTRY
- 5.3.4 TRENDS IN GLOBAL AUTOMOTIVE AND ELECTRIC VEHICLE INDUSTRY
- 5.4 SUPPLY CHAIN ANALYSIS
- 5.5 ECOSYSTEM ANALYSIS
- 5.6 PRICING ANALYSIS
- 5.6.1 AVERAGE SELLING PRICE TREND OF POSITION SENSOR, BY TYPE, 2022-2025
- 5.6.2 AVERAGE SELLING PRICE TREND OF POSITION SENSOR, BY REGION, 2022-2025
- 5.7 TRADE ANALYSIS
- 5.7.1 IMPORT SCENARIO (HS CODE 9031)
- 5.7.2 EXPORT SCENARIO (HS CODE 9031)
- 5.8 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.9 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.10 INVESTMENT AND FUNDING SCENARIO
- 5.11 CASE STUDY ANALYSIS
- 5.12 IMPACT OF US TARIFFS - POSITION SENSOR MARKET
- 5.12.1 INTRODUCTION
- 5.12.2 KEY TARIFF RATES
- 5.12.3 PRICE IMPACT ANALYSIS
- 5.12.4 IMPACT ON COUNTRIES/REGIONS
- 5.12.4.1 US
- 5.12.4.2 Europe
- 5.12.4.3 Asia Pacific
- 5.12.5 IMPACT ON END-USE INDUSTRIES
6 TECHNOLOGICAL ADVANCEMENT, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY TECHNOLOGIES
- 6.1.1 INDUCTIVE SENSING
- 6.1.2 HALL-EFFECT
- 6.1.3 COMPLEMENTARY TECHNOLOGIES
- 6.1.3.1 IoT connectivity
- 6.1.3.2 Edge computing
- 6.1.4 ADJACENT TECHNOLOGIES
- 6.1.4.1 LiDAR
- 6.2 PATENT ANALYSIS
- 6.2.1 PATENT ANALYSIS
- 6.3 IMPACT OF AI ON POSITION SENSOR MARKET
- 6.3.1 TOP AI USE CASES AND MARKET POTENTIAL
- 6.3.2 BEST PRACTICES FOLLOWED BY POSITION SENSOR OEMS
- 6.3.3 CASE STUDIES RELATED TO AI IMPLEMENTATION IN POSITION SENSOR MARKET
- 6.3.4 INTERCONNECTED/ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.3.5 CLIENTS' READINESS TO ADOPT AI-INTEGRATED POSITION SENSOR
7 REGULATORY LANDSCAPE
- 7.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.2 INDUSTRY STANDARDS
- 7.2.1 IEC 61326-1
- 7.2.2 ANSI/ISA-75.25.01
- 7.2.3 IEC 60947-5-2
- 7.2.4 EN 61496-1
- 7.2.5 NEMA ICS 5
- 7.2.6 IEC 60947-5-6
8 CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS AND BUYING CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS AND INTERNAL CHALLENGES
- 8.4 UNMET NEEDS OF VARIOUS END USERS
9 POSITION SENSOR MARKET, BY TYPE
- 9.1 INTRODUCTION
- 9.2 LINEAR SENSORS
- 9.2.1 INCREASING DEMAND FOR PRECISION POSITION FEEDBACK IN INDUSTRIAL AUTOMATION TO BOOST ADOPTION
- 9.2.2 LINEAR ENCODERS
- 9.2.2.1 Optical linear encoders
- 9.2.2.2 Magnetic linear encoders
- 9.2.2.3 Inductive linear encoders
- 9.2.2.4 Capacitive linear encoders
- 9.2.3 LINEAR VARIABLE DIFFERENTIAL TRANSFORMERS (LVDTS)
- 9.2.4 MAGNETOSTRICTIVE SENSORS
- 9.2.5 LINEAR POTENTIOMETERS
- 9.2.6 LASER POSITION SENSORS
- 9.3 ROTARY SENSORS
- 9.3.1 GROWING DEMAND FOR PRECISE ROTATIONAL MEASUREMENT ACROSS INDUSTRIES TO FUEL SEGMENTAL GROWTH
- 9.3.2 ROTARY ENCODERS
- 9.3.2.1 Optical rotary encoders
- 9.3.2.2 Magnetic rotary encoders
- 9.3.2.3 Mechanical rotary encoders
- 9.3.2.4 Capacitive rotary encoders
- 9.3.3 ROTARY POTENTIOMETERS
- 9.3.4 ROTARY VARIABLE DIFFERENTIAL TRANSFORMERS
- 9.3.5 RESOLVERS
- 9.4 PROXIMITY SENSORS
- 9.4.1 RISING USE IN AUTOMOTIVE AND INDUSTRIAL APPLICATIONS TO FOSTER SEGMENTAL GROWTH
- 9.5 PHOTOELECTRIC SENSORS
- 9.5.1 RISING NEED FOR AUTOMATED OBJECT DETECTION IN AUTOMOTIVE AND FOOD PROCESSING INDUSTRIES TO PROPEL MARKET
- 9.5.2 REFLECTIVE SENSORS
- 9.5.3 THROUGH-BEAM SENSORS
- 9.5.4 DIFFUSE SENSORS
- 9.6 3D SENSORS
- 9.6.1 EXPANDING ADOPTION OF 3D SENSORS FOR SPATIAL PERCEPTION AND OBJECT DETECTION TO FACILITATE SEGMENTAL GROWTH
- 9.6.2 TOF SENSORS
- 9.6.3 STEREO VISION SENSORS
- 9.6.4 STRUCTURED LIGHT SENSORS
10 POSITION SENSOR MARKET, BY CONTACT TYPE
- 10.1 INTRODUCTION
- 10.2 NON-CONTACT TYPE
- 10.2.1 GROWING PREFERENCE FOR DURABLE AND LOW-MAINTENANCE POSITION SENSING IN HARSH ENVIRONMENTS TO DRIVE MARKET
- 10.3 CONTACT TYPE
- 10.3.1 CONTINUED USE OF COST-EFFECTIVE CONTACT SENSORS IN PRECISION POSITION MEASUREMENT TO SUPPORT MARKET GROWTH
11 POSITION SENSOR MARKET, BY SIGNAL OUTPUT
- 11.1 INTRODUCTION
- 11.2 DIGITAL
- 11.2.1 INDUSTRY 4.0 ADOPTION TO ACCELERATE DEMAND FOR DIGITAL OUTPUT-BASED POSITION SENSORS
- 11.3 ANALOG
- 11.3.1 NEED FOR CONTINUOUS POSITION FEEDBACK TO SPIKE DEMAND FOR ANALOG POSITION SENSOR
12 POSITION SENSOR MARKET, BY TECHNOLOGY
- 12.1 INTRODUCTION
- 12.2 CAPACITIVE
- 12.2.1 RISING DEMAND FOR HIGH-PRECISION MEASUREMENTS AND TOUCH-BASED DEVICES TO CONTRIBUTE TO MARKET GROWTH
- 12.3 INDUCTIVE
- 12.3.1 HIGH DEMAND FOR ROBUST POSITION SENSING IN AUTOMOTIVE AND INDUSTRIAL AUTOMATION TO SUPPORT MARKET GROWTH
- 12.4 OPTICAL
- 12.4.1 INCREASING ADOPTION IN ROBOTICS, 3D SCANNING, AND PRECISION APPLICATIONS TO AUGMENT MARKET GROWTH
- 12.5 MAGNETIC
- 12.5.1 ESCALATING USE IN AUTOMOTIVE SYSTEMS FOR THROTTLE CONTROL TO FOSTER SEGMENTAL GROWTH
- 12.6 ULTRASONIC
- 12.6.1 RISING IMPLEMENTATION IN AUTOMOTIVE, INDUSTRIAL, AND PACKAGING APPLICATIONS TO SUPPORT SEGMENTAL GROWTH
- 12.7 PIEZOELECTRIC
- 12.7.1 HIGH SENSITIVITY AND FAST RESPONSE TO INCREASE DEMAND FROM AEROSPACE AND HEALTHCARE INDUSTRIES
13 POSITION SENSOR MARKET, BY CONNECTIVITY
- 13.1 INTRODUCTION
- 13.2 WIRED
- 13.2.1 ABILITY TO SUPPORT POSITION SENSING IN MISSION-CRITICAL AND INDUSTRIAL APPLICATIONS TO ACCELERATE DEPLOYMENT
- 13.3 WIRELESS
- 13.3.1 INCLINATION TOWARD IIOT AND SMART FACTORIES TO BOOST DEMAND
14 POSITION SENSOR MARKET, BY APPLICATION
- 14.1 INTRODUCTION
- 14.2 MACHINE TOOLS
- 14.2.1 INCREASING AUTOMATION AND PRECISION REQUIREMENTS IN MANUFACTURING SECTOR TO FUEL MARKET GROWTH
- 14.3 ROBOTICS
- 14.3.1 INCREASING DEPLOYMENT OF INDUSTRIAL AND COLLABORATIVE ROBOTS TO STRENGTHEN DEMAND
- 14.4 MOTION SYSTEMS
- 14.4.1 INCREASED DEMAND FOR HIGH ACCURACY IN MOTION CONTROL IN AUTOMATED MANUFACTURING LINES TO PROPEL MARKET
- 14.5 MATERIAL HANDLING EQUIPMENT
- 14.5.1 THRIVING E-COMMERCE AND LOGISTICS SECTORS TO ACCELERATE DEMAND
- 14.6 TEST EQUIPMENT
- 14.6.1 REQUIREMENT FOR TESTING EQUIPMENT WITH GREATER ACCURACY AND REAL-TIME MEASUREMENTS TO STIMULATE DEMAND
- 14.7 OTHER APPLICATIONS
15 POSITION SENSOR MARKET, BY END-USE INDUSTRY
- 15.1 INTRODUCTION
- 15.2 MANUFACTURING
- 15.2.1 ADVANCEMENTS IN INDUSTRIAL AUTOMATION AND ROBOTICS TO SPIKE DEMAND FOR POSITION SENSORS
- 15.2.2 ROBOTICS
- 15.2.3 ASSEMBLY LINE AUTOMATION
- 15.2.4 QUALITY CONTROL & INSPECTION
- 15.3 AUTOMOTIVE
- 15.3.1 GROWING DEMAND FOR SELF-DRIVING CARS TO CREATE GROWTH OPPORTUNITIES
- 15.3.2 ENGINE MANAGEMENT SYSTEMS
- 15.3.3 TRANSMISSION SYSTEMS
- 15.3.4 SAFETY & SECURITY SYSTEMS
- 15.3.5 INFOTAINMENT SYSTEMS
- 15.3.6 ADVANCED DRIVER-ASSISTANCE SYSTEMS
- 15.4 AEROSPACE & DEFENSE
- 15.4.1 GROWING NEED FOR HIGH-PRECISION POSITION SENSING IN AEROSPACE APPLICATIONS TO FACILITATE MARKET GROWTH
- 15.4.2 FLIGHT CONTROL SYSTEMS
- 15.4.3 NAVIGATION SYSTEMS
- 15.4.4 WEAPON SYSTEMS
- 15.4.5 UNMANNED AERIAL VEHICLES
- 15.4.6 SPACECRAFT SYSTEMS
- 15.5 PACKAGING
- 15.5.1 SURGING NEED FOR ADVANCED PACKAGING MACHINERY TO DRIVE MARKET
- 15.5.2 AUTOMATED PACKAGING LINES
- 15.5.3 LABELING SYSTEMS
- 15.5.4 SORTING SYSTEMS
- 15.6 HEALTHCARE
- 15.6.1 INCREASING ADOPTION OF MINIMALLY INVASIVE AND ROBOTIC-ASSISTED PROCEDURES TO ACCELERATE MARKET GROWTH
- 15.6.2 MEDICAL IMAGING EQUIPMENT
- 15.6.3 PATIENT MONITORING SYSTEMS
- 15.6.4 SURGICAL INSTRUMENTS
- 15.6.5 DIAGNOSTIC DEVICES
- 15.7 CONSUMER ELECTRONICS
- 15.7.1 ELEVATING DEMAND FOR SMART WEARABLES TO SUPPORT MARKET GROWTH
- 15.7.2 SMARTPHONES & TABLETS
- 15.7.3 GAMING CONSOLES
- 15.7.4 WEARABLE DEVICES
- 15.7.5 VR DEVICES
- 15.7.6 HOME AUTOMATION SYSTEMS
- 15.8 OTHER END-USE INDUSTRIES
- 15.8.1 AGRICULTURE
- 15.8.2 ENERGY & POWER
- 15.8.3 TELECOMMUNICATIONS
16 POSITION SENSOR MARKET, BY REGION
- 16.1 INTRODUCTION
- 16.2 NORTH AMERICA
- 16.2.1 US
- 16.2.1.1 RISING DEMAND POSITION SENSORS FROM AUTOMOTIVE AND AEROSPACE VERTICALS TO ACCELERATE MARKET GROWTH
- 16.2.2 CANADA
- 16.2.2.1 Growing adoption of ADAS and automated manufacturing technologies by automobile companies to drive market
- 16.2.3 MEXICO
- 16.2.3.1 Booming electronics and industrial verticals to contribute to market growth
- 16.2.1 US
- 16.3 EUROPE
- 16.3.1 UK
- 16.3.1.1 Developments in medical and automotive sector and potential in industrial automation to create growth opportunities
- 16.3.2 GERMANY
- 16.3.2.1 Heavy investments in R&D on automotive electronics to fuel demand
- 16.3.3 FRANCE
- 16.3.3.1 Expansion of electric mobility and continued investment in aerospace manufacturing to reinforce market growth
- 16.3.4 ITALY
- 16.3.4.1 Presence of prominent automotive companies to contribute to market growth
- 16.3.5 REST OF EUROPE
- 16.3.1 UK
- 16.4 ASIA PACIFIC
- 16.4.1 CHINA
- 16.4.1.1 Inclination toward domestic and smart manufacturing to boost demand
- 16.4.2 JAPAN
- 16.4.2.1 Rapid industrialization and well-developed robotics and automation technologies to foster market growth
- 16.4.3 SOUTH KOREA
- 16.4.3.1 Booming electronics & semiconductors industry to expedite market growth
- 16.4.4 INDIA
- 16.4.4.1 Growing customer base for electronics and consumer goods to strengthen market growth
- 16.4.5 REST OF ASIA PACIFIC
- 16.4.1 CHINA
- 16.5 ROW
- 16.5.1 MIDDLE EAST
- 16.5.1.1 Smart city and infrastructure development projects to create growth opportunities
- 16.5.1.2 GCC countries
- 16.5.1.3 Rest of the Middle East
- 16.5.2 SOUTH AMERICA
- 16.5.2.1 Increasing investments in renewable energy projects to drive market
- 16.5.3 AFRICA
- 16.5.3.1 Rising demand for advanced mining equipment to foster market growth
- 16.5.1 MIDDLE EAST
17 COMPETITIVE LANDSCAPE
- 17.1 OVERVIEW
- 17.2 KEY PLAYER COMPETITIVE STRATEGIES/RIGHT TO WIN, 2023-2026
- 17.3 REVENUE ANALYSIS, 2021-2025
- 17.4 MARKET SHARE ANALYSIS, 2O25
- 17.5 COMPANY VALUATION AND FINANCIAL METRICS
- 17.6 BRAND COMPARISON
- 17.7 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 17.7.1 STARS
- 17.7.2 EMERGING LEADERS
- 17.7.3 PERVASIVE PLAYERS
- 17.7.4 PARTICIPANTS
- 17.7.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 17.7.5.1 Company footprint
- 17.7.5.2 Region footprint
- 17.7.5.3 Type footprint
- 17.7.5.4 Contact type footprint
- 17.7.5.5 End-use industry footprint
- 17.8 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 17.8.1 PROGRESSIVE COMPANIES
- 17.8.2 RESPONSIVE COMPANIES
- 17.8.3 DYNAMIC COMPANIES
- 17.8.4 STARTING BLOCKS
- 17.8.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 17.8.5.1 Detailed list of startups/SMEs
- 17.8.5.2 Competitive benchmarking of key startups/SMEs
- 17.9 COMPETITIVE SCENARIO
- 17.9.1 PRODUCT LAUNCHES
- 17.9.1.1 Deals
- 17.9.1 PRODUCT LAUNCHES
18 COMPANY PROFILES
- 18.1 KEY PLAYERS
- 18.1.1 HONEYWELL INTERNATIONAL INC.
- 18.1.1.1 Business overview
- 18.1.1.2 Products/Solutions/Services offered
- 18.1.1.3 Recent developments
- 18.1.1.3.1 Product launches
- 18.1.1.3.2 Deals
- 18.1.1.4 MnM view
- 18.1.1.4.1 Key strengths/Right to win
- 18.1.1.4.2 Strategic choices
- 18.1.1.4.3 Weaknesses and competitive threats
- 18.1.2 TDK CORPORATION
- 18.1.2.1 Business overview
- 18.1.2.2 Products/Solutions/Services offered
- 18.1.2.3 Recent developments
- 18.1.2.3.1 Product launches
- 18.1.2.3.2 Expansions
- 18.1.2.3.3 Deals
- 18.1.2.4 MnM views
- 18.1.2.4.1 Key strengths/Right to win
- 18.1.2.4.2 Strategic choices
- 18.1.2.4.3 Weaknesses and competitive threats
- 18.1.3 STMICROELECTRONICS
- 18.1.3.1 Business overview
- 18.1.3.2 Products/Solutions/Services offered
- 18.1.3.3 Recent developments
- 18.1.3.3.1 Product launches
- 18.1.3.3.2 Expansions
- 18.1.3.4 MnM view
- 18.1.3.4.1 Key strengths/Right to win
- 18.1.3.4.2 Strategic choices
- 18.1.3.4.3 Weaknesses and competitive threats
- 18.1.4 AMPHENOL CORPORATION
- 18.1.4.1 Business overview
- 18.1.4.2 Products/Solutions/Services offered
- 18.1.4.3 Recent developments
- 18.1.4.3.1 Product launches
- 18.1.4.3.2 Deals
- 18.1.4.4 MnM view
- 18.1.4.4.1 Key strengths/Right to win
- 18.1.4.4.2 Strategic choices
- 18.1.4.4.3 Weaknesses and competitive threats
- 18.1.5 SICK AG
- 18.1.5.1 Business overview
- 18.1.5.2 Products/Solutions/Services offered
- 18.1.5.3 Recent developments
- 18.1.5.3.1 Product launches
- 18.1.5.3.2 Expansions
- 18.1.5.3.3 Deals
- 18.1.5.4 MnM view
- 18.1.5.4.1 Key strengths/Right to win
- 18.1.5.4.2 Strategic choices
- 18.1.5.4.3 Weaknesses and competitive threats
- 18.1.6 TE CONNECTIVITY
- 18.1.6.1 Business overview
- 18.1.6.2 Products/Solutions/Services offered
- 18.1.6.3 Recent developments
- 18.1.6.3.1 Deals
- 18.1.6.3.2 Expansions
- 18.1.7 TEXAS INSTRUMENTS INCORPORATED
- 18.1.7.1 Business overview
- 18.1.7.2 Products/Solutions/Services offered
- 18.1.8 AMS-OSRAM AG
- 18.1.8.1 Business overview
- 18.1.8.2 Products/Solutions/Services offered
- 18.1.8.3 Recent developments
- 18.1.8.3.1 Product launches
- 18.1.8.3.2 Expansions
- 18.1.9 ANALOG DEVICES, INC.
- 18.1.9.1 Business overview
- 18.1.9.2 Products/Solutions/Services offered
- 18.1.9.3 Recent developments
- 18.1.9.3.1 Product launches
- 18.1.10 CTS CORPORATION
- 18.1.10.1 Business overview
- 18.1.10.2 Products/Solutions/Services offered
- 18.1.10.3 Recent developments
- 18.1.10.3.1 Product launches
- 18.1.10.3.2 Deals
- 18.1.11 INFINEON TECHNOLOGIES AG
- 18.1.11.1 Business overview
- 18.1.11.2 Products/Solutions/Services offered
- 18.1.11.3 Recent developments
- 18.1.11.3.1 Product launches
- 18.1.12 MICROCHIP TECHNOLOGY INC.
- 18.1.12.1 Business overview
- 18.1.12.2 Products/Solutions/Services offered
- 18.1.12.3 Recent developments
- 18.1.12.3.1 Product launches
- 18.1.13 VISHAY INTERTECHNOLOGY, INC.
- 18.1.13.1 Business overview
- 18.1.13.2 Products/Solutions/Services offered
- 18.1.13.3 Recent developments
- 18.1.13.3.1 Product launches
- 18.1.14 NOVOTECHNIK U.S. INC.
- 18.1.14.1 Business overview
- 18.1.14.2 Products/Solutions/Services offered
- 18.1.1 HONEYWELL INTERNATIONAL INC.
- 18.2 OTHER PLAYERS
- 18.2.1 BAUMER
- 18.2.2 NXP SEMICONDUCTORS
- 18.2.3 RENISHAW PLC
- 18.2.4 ALLEGRO MICROSYSTEMS, INC.
- 18.2.5 PHOENIX SENSORS
- 18.2.6 BALLUFF AUTOMATION
- 18.2.7 PEPPERL+FUCHS SE
- 18.2.8 SENSOR SOLUTIONS CORP.
- 18.2.9 ANGST+PFISTER SENSORS AND POWER AG
- 18.2.10 ACTIVE SENSORS
- 18.2.11 ROCKWELL AUTOMATION
19 RESEARCH METHODOLOGY
- 19.1 RESEARCH DATA
- 19.1.1 SECONDARY DATA
- 19.1.1.1 List of key secondary sources
- 19.1.1.2 Key data from secondary sources
- 19.1.2 PRIMARY DATA
- 19.1.2.1 List of primary interview participants
- 19.1.2.2 Breakdown of primary interviews
- 19.1.2.3 Key data from primary sources
- 19.1.2.4 Key Industry Insights
- 19.1.3 SECONDARY AND PRIMARY RESEARCH
- 19.1.1 SECONDARY DATA
- 19.2 MARKET SIZE ESTIMATION
- 19.2.1 BOTTOM-UP APPROACH
- 19.2.1.1 Approach to arrive at market size using bottom-up analysis (demand side)
- 19.2.2 TOP-DOWN APPROACH
- 19.2.2.1 Approach to arrive at market size using top-down analysis (supply side)
- 19.2.1 BOTTOM-UP APPROACH
- 19.3 FACTOR ANALYSIS
- 19.3.1 DEMAND-SIDE ANALYSIS
- 19.3.2 SUPPLY-SIDE ANALYSIS
- 19.4 DATA TRIANGULATION
- 19.5 RESEARCH ASSUMPTIONS
- 19.6 RESEARCH LIMITATIONS
- 19.7 RISK ASSESSMENT
20 APPENDIX
- 20.1 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 20.2 CUSTOMIZATION OPTIONS
- 20.3 RELATED REPORTS
- 20.4 AUTHOR DETAILS


