

|
시장보고서
상품코드
2118094
사건 관리 소프트웨어 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Matter Management Software - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
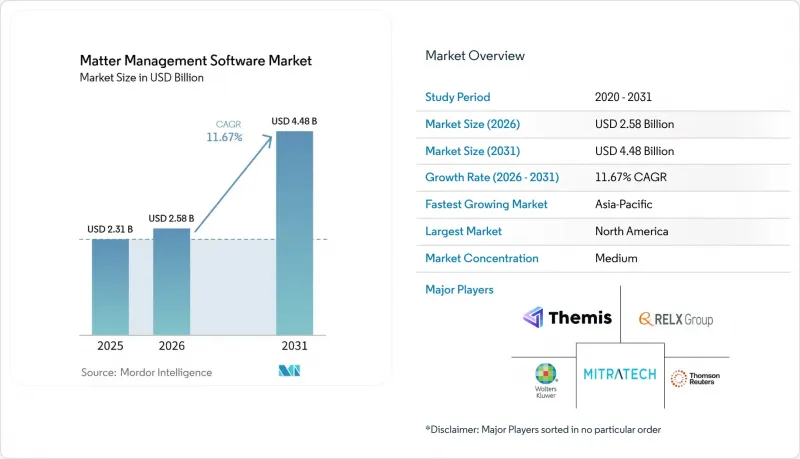
에 의하면, 사건 관리 소프트웨어 시장 규모는 2025년 23억 1,000만 달러로 평가되었고, 2026년 25억 8,000만 달러에서 2031년까지 44억 8,000만 달러로 확대될 것으로 예측되며, 2026-2031년 연평균 복합 성장률(CAGR)은 11.67%를 나타낼 전망입니다.
본 보고서는 배포 방식별(클라우드 기반, 온프레미스, 하이브리드), 조직 규모별(대기업, 중소기업), 사건 유형별(소송·분쟁, 상사·기업 법무 사건, 컴플라이언스·규제 관련 사건, 기타), 최종 사용자 산업별(기업 법무 부서, 기타), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 사건 관리 소프트웨어 시장 동향 및 인사이트
법무 업무에서의 클라우드 전환 가속화
2025년에는 클라우드 기반 도입이 사건 관리 소프트웨어 시장의 76.23%를 차지했으며, 2026년에도 조직들은 온프레미스형 시스템에서 클라우드로의 전환을 계속했습니다. Wolters Kluwer의 2025년 벤치마크 조사에 따르면, 유럽과 미국의 조사 대상 법무 전문가들 사이에서 법무 업무에 사용되는 일반적인 파일 공유 도구의 이용률은 1년 동안 46%에서 33%로 감소했습니다. 이러한 변화는 법적 기록과 접근 권한을 보다 일관된 방식으로 정리하는 플랫폼으로의 전환을 나타냅니다. 또한 클라우드 저장소는 벤더에게 생성된 요약, 비용 분석, 기한 추출 기능을 제공하는 실용적인 수단이 됩니다. 파일이 흩어져 있거나 온프레미스 데이터가 고립되어 있는 조직은 이러한 기능의 도입이 지연될 가능성이 있습니다. 그 결과, 클라우드 전환을 단순한 기술 교체로만 볼 것이 아니라 법무 업무 현대화의 일환으로 인식해야 한다는 압력이 커지고 있습니다.
법무 업무 현대화를 위한 전제조건으로서의 AI 대응 사건 데이터
많은 법무 부서는 법무 업무를 위한 일관된 데이터 구조를 확립하기 전에 인공지능(AI) 도구를 도입했습니다. 2025년 미국 기업법무협회(ACC)의 벤치마크 조사에 따르면, 법무 부서의 52%가 AI 도구를 이용하고 있으며, 32%는 사건 관리 소프트웨어를, 26%는 워크플로우 도구를 이용하고 있는 것으로 나타났습니다. 이러한 격차로 인해 많은 팀이 불완전한 데이터, 라벨링이 일관되지 않은 데이터, 혹은 시스템 간에 분산된 데이터를 사용하여 업무를 수행할 수밖에 없는 상황에 처해 있습니다. 구조화된 사건 기록은 신뢰할 수 있는 자동화를 위한 관리된 기반을 제공하므로, 사건 관리 소프트웨어 시장에 대한 수요를 뒷받침하고 있습니다. 이러한 필요성은 불완전한 법무 기록 시스템을 대체하는 데 있어 점점 더 중요한 이유가 되고 있습니다. Mitratech는 2026년 3월, Advanced Docket Management 기능을 통해 TeamConnect ARIES의 기능을 확장하여, 모델 내에 사건 데이터를 보관하지 않고도 기업 시스템 내의 거버넌스가 적용된 데이터에 AI를 적용했습니다. 분류 체계와 기록의 품질을 향상시킨 법무 팀은 향후 AI 활용을 위한 보다 유용한 기반을 구축할 수 있습니다.
데이터 보안 및 의뢰인의 기밀성에 대한 우려
AI를 활용한 워크플로는 변호사와 의뢰인 간의 특권 통신 및 기밀성이 높은 사건 기록과 관련하여 우려를 불러일으키고 있습니다. 법무 부서의 조달 담당자들은 기밀 정보가 모델 학습에 사용되는지, 어디에 저장되는지, 접근 권한이 어떻게 제한되는지에 대해 점점 더 많은 질문을 하고 있습니다. 조달 팀은 또한 데이터 분리, 설정 가능한 저장 위치, 정보 유출 시 알림 절차에 관한 계약상 확약도 요구하고 있습니다. 이러한 요건은 특히 전담 법무 기술 전문가를 보유하지 않은 중규모 조직에서 선정 과정을 지연시킬 가능성이 있습니다. 또한, 보안 조치가 문서화되어 있고 지역 내 도입 옵션을 제공하는 플랫폼이 유리할 수도 있습니다. 데이터 보안은 여전히 프로젝트 관리 소프트웨어 시장의 제약 요인으로 작용하고 있습니다. 이는 법무 팀이 자동화를 확대함에 있어 고객 정보 처리에 대한 신뢰가 필수적이기 때문입니다.
부문 분석
2025년, 클라우드 기반 시스템은 사건 관리 소프트웨어 시장 점유율의 76.23%를 차지했습니다. 이러한 위상은 낮은 소유 비용, 자동 갱신, 여러 거점에서 업무를 수행하는 법무 팀에 대한 지원을 반영한 것입니다. 또한 클라우드 시스템은 사내 사용자나 외부 변호사에 대한 기록 접근 권한을 관리할 수도 있습니다. 법무 부서가 사건 수임, 문서, 청구서, 보고서를 통합된 운영 환경으로 통합해 나가는 과정에서 이러한 기능은 중요합니다. 이러한 도입 기반을 통해 사건 관리 소프트웨어 시장은 플랫폼의 지속적인 업그레이드를 위한 견고한 토대를 마련하고 있습니다.
하이브리드형 도입은 2031년까지 연평균 성장률(CAGR) 14.96%로 가장 높은 성장률을 나타낼 것으로 예측됩니다. 이러한 추세는 분석 및 협업에는 클라우드 서비스를 활용하면서도, 기밀성이 높은 기록이나 특권적 통신은 관리된 로컬 환경에 보관해야 할 필요성을 반영하고 있습니다. Wolters Kluwer의 조사에 따르면, 조사 대상인 유럽과 미국의 법무 부서에서 Google Drive나 SharePoint와 같은 비정형 도구의 이용률이 1년 동안 46%에서 33%로 감소했습니다. iManage는 2026년 5월, 인공지능 시스템이 일괄 내보내기나 기존 보안 제어의 변경 없이도 관리 대상 사건 컨텐츠에 접근할 수 있도록 하는 ‘Model Context Protocol Server’를 도입했습니다. 따라서 사안 관리 소프트웨어 시장에서는 클라우드 네이티브와 하이브리드 플랫폼이 시장에서 공존할 여지가 있습니다.
2025년에는 대기업이 매출의 68.54%를 차지했습니다. 이는 대기업이 더 대규모의 법무 팀을 보유하고 있으며, 엔터프라이즈 법무 관리 시스템 도입 역사가 길고, 광범위한 도입을 위한 예산도 풍부하다는 점을 반영합니다. 이러한 조직에서는 많은 사업 부문과 관할 구역에 걸쳐 일관된 프로세스가 요구되는 경우가 많습니다. 또한, 외부 변호사의 감독, 지출 관리, 감사 대응이 가능한 보고서 작성에 대해서도 상당한 요건이 부과되고 있습니다. 2025년 미국 기업법무협회(ACC)의 벤치마크 조사에 따르면, 매출액 200억 달러 이상의 조직 중 59%가 워크플로우 도구를 활용하는 반면, 매출액 10억 달러 이하의 조직에서는 16%에 그치고 있습니다. 이러한 이용 패턴은 사안 관리 소프트웨어 시장에서 지속적인 시스템 교체 및 확장 기회를 뒷받침하고 있습니다.
중소기업 시장은 2031년까지 연평균 성장률(CAGR) 13.38%를 나타낼 것으로 예측되며, 이 부문에서 가장 높은 성장률을 보이고 있습니다. 구독형 가격 정책과 기성 템플릿 덕분에, 과거 소규모 법무 팀의 소프트웨어 도입을 가로막았던 자본 부담과 맞춤 설정의 번거로움이 줄어들고 있습니다. 또한, 규정 준수 의무 역시 기존에는 일상적인 조정 업무에 스프레드시트, 이메일, 외부 변호사에 의존하던 조직에 영향을 미치고 있습니다. LawVu는 2025년 12월 ClauseBase를 인수하여, 사내 법무 팀용 법률 운영 플랫폼에 계약서 작성 자동화 기능을 추가했습니다. 정보 기술에 대한 의존도를 낮추고 도입 기간을 단축할 수 있는 벤더는 사건 관리 소프트웨어 시장의 이 미개척 부문에 대응할 수 있습니다.
지역별 분석
2025년, 북미는 매출의 38.67%를 차지했습니다. 이 지역은 기업 법무 부서가 고도로 집중되어 있고, 엔터프라이즈 법무 관리 도입이 정착되어 있으며, Thomson Reuters, Mitratech, Wolters Kluwer와 같은 벤더가 존재한다는 점에서 혜택을 보고 있습니다. LexisNexis CounselLink는 2025년 동향 보고서에서 약 180만 건의 사건과 670억 달러를 초과하는 법무 지출을 추적했습니다. 해당 보고서에 따르면, 특정 업무 부문에서 일부 파트너의 시간당 요금이 1,000달러를 초과하는 것으로 나타났습니다. 법무 비용의 상승에 따라 기업의 법무 부서는 외부 변호사를 감독하고 지출에 관한 의사결정을 내리기 위해 사건 관리 소프트웨어 시장을 활용하고 있습니다.
유럽은 두 번째로 큰 지역이며, 규정 준수 관련 플랫폼 투자에 의존하고 있습니다. 『Wolters Kluwer 벤치마크 조사 2025』에 따르면, 유럽 법무 부서의 41%가 계약 수명주기 관리 소프트웨어를 이용하고 있으며, 이는 2024년의 33%에서 증가한 수치입니다. 또한 7%는 여전히 종이 문서를 통해 계약을 관리하고 있는 것으로 나타났습니다. 이로 인해 계약 관리 소프트웨어 시장에서 여전히 분산된 프로세스를 채택하고 있는 법무 팀 전체에게 디지털화를 위한 큰 기회가 남아 있습니다. 개인정보 보호 규정 및 유럽연합(EU)의 인공지능(AI) 프레임워크의 영향으로, 지역 내 호스팅 및 계약 데이터 분리를 제공하는 벤더를 선택하는 조달 경향이 강해지고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 16.54%를 나타낼 것으로 예측되며, 사안 관리 소프트웨어 시장에서 지역별 가장 높은 성장률을 보이고 있습니다. 일본의 사법 디지털화와 인도의 기업 법무 기능 확대에 따라, 기업 법무 부서와 로펌 모두에서 새로운 사용자가 생겨나고 있습니다. Huayu Yodex는 자사 플랫폼이 40종 이상의 법률 문서를 지원하며, 2025년에는 사안 데이터 자동 추출 정확도가 90% 이상을 달성했다고 보고했습니다. 남미, 중동 및 아프리카는 여전히 규모는 작지만 성장 중인 지역이며, 인프라 구축 현황에 편차가 있어 설정 작업이 최소화되는 클라우드 기반 시스템이 선호되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.03According to Mordor Intelligence, the matter management software market size is projected to expand from USD 2.31 billion in 2025 and USD 2.58 billion in 2026 to USD 4.48 billion by 2031, registering a CAGR of 11.67% between 2026 and 2031.
This report is Segmented by Deployment (Cloud-Based, On-Premises, and Hybrid), Organization Size (Large Enterprises, and Small and Medium Enterprises), Matter Type (Litigation and Disputes, Commercial and Corporate Legal Matters, Compliance Matters, and More), End User Industry (Corporate Legal Departments, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Matter Management Software Market Trends and Insights
Accelerating Cloud Migration in Legal Operations
Cloud-based deployment represented 76.23% of the matter management software market in 2025, and organizations continued moving away from on-premises systems in 2026. The Wolters Kluwer Benchmark Study 2025 found that the use of general file-sharing tools for legal work fell from 46% to 33% in 1 year among surveyed legal professionals in Europe and the United States. This change indicates a move toward platforms that organize legal records and permissions in a more consistent way. Cloud repositories also give vendors a practical route to deliver generated summaries, spend analysis, and deadline extraction features. Organizations that retain scattered files or isolated on-premises data may face a slower path to these functions. The result is stronger pressure to treat cloud migration as part of legal operations modernization rather than a simple technology replacement.
AI-Ready Matter Data as a Prerequisite for Legal Operations Modernization
Many legal departments adopted artificial intelligence tools before establishing consistent data structures for their legal work. The 2025 Association of Corporate Counsel benchmark found that 52% of departments used artificial intelligence tools, while 32% used matter management software and 26% used workflow tools. This gap leaves many teams working with data that is incomplete, inconsistently labeled, or separated across systems. It supports demand for the matter management software market because structured matter records provide a controlled base for reliable automation. This need is becoming a more important reason to replace incomplete legal record systems. Mitratech expanded its TeamConnect ARIES capabilities with Advanced Docket Management in March 2026, applying artificial intelligence to governed data within the enterprise system without retaining matter data in the model. Legal teams that improve taxonomy and record quality can create a more useful foundation for future artificial intelligence applications.
Data Security and Client Confidentiality Concerns
Artificial intelligence-assisted workflows raise concerns about privileged communications and sensitive case records. Legal buyers increasingly ask whether sensitive information is used to train models, where it is stored, and how access is restricted. Procurement teams also expect contractual commitments on data isolation, configurable residency, and breach notification processes. These requirements can slow selection cycles, especially for mid-sized organizations without dedicated legal technology specialists. They can also favor platforms that document security controls and offer in-region deployment choices. Data security remains a restraint for the matter management software market because confidence in the handling of client information is essential before legal teams will expand automation.
Other drivers and restraints analyzed in the detailed report include:
- Growing Demand for Legal Workflow Automation
- Rising Regulatory and Privacy Compliance Requirements
- Implementation Complexity and Legacy-System Integration Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cloud-based systems held 76.23% of the matter management software market share in 2025. Their position reflects lower ownership costs, automatic updates, and support for legal teams that work across locations. Cloud systems can also provide controlled access to records for internal users and outside counsel. These capabilities are important as legal departments bring matter intake, documents, invoices, and reporting into a single operating environment. This installed base gives the matter management software market a broad foundation for continued platform upgrades.
Hybrid deployment is projected to record the highest growth rate at a 14.96% CAGR through 2031. This pattern reflects the need to keep highly sensitive records and privileged communications in controlled local environments while using cloud services for analytics and collaboration. The Wolters Kluwer study recorded a decline in the use of unstructured tools such as Google Drive and SharePoint from 46% to 33% in 1 year among surveyed European and U.S. legal departments. iManage introduced its Model Context Protocol Server in May 2026 to allow artificial intelligence systems to access governed matter content without bulk exports or changes to existing security controls. The Matter management software industry therefore has room for both cloud-native and hybrid platforms within the matter management software market.
Large enterprises held 68.54% of revenue in 2025, reflecting their larger legal teams, longer use of enterprise legal management systems, and greater budgets for broad deployments. These organizations often need consistent processes across many business units and jurisdictions. They also have substantial requirements for outside counsel oversight, spend management, and audit-ready reporting. The 2025 Association of Corporate Counsel benchmark found workflow tool use in 59% of organizations with USD 20 billion or more in revenue, compared with 16% of organizations below USD 1 billion in revenue. This use pattern supports continued replacement and expansion opportunities in the matter management software market.
Small and medium-sized enterprises are projected to grow at a 13.38% CAGR through 2031, the fastest rate within this segmentation. Subscription pricing and prebuilt templates reduce the capital and customization burden that once limited software adoption among smaller legal teams. Compliance obligations are also affecting organizations that previously relied on spreadsheets, email, and external counsel for routine coordination. LawVu acquired ClauseBase in December 2025, adding contract drafting automation to its legal operations platform for in-house teams. Vendors that limit information technology dependence and shorten deployment periods can address this open area of the matter management software market.
Complete Report Scope:
- By Deployment
- Cloud-Based
- On-Premises
- Hybrid
- By Organization Size
- Large Enterprises
- Small and Medium-Sized Enterprises
- By Matter Type
- Litigation and Disputes
- Commercial and Corporate Legal Matters
- Compliance and Regulatory Matters
- Intellectual Property Matters
- Employment and Labor Matters
- Claims and Investigations
- By End User Industry
- Corporate Legal Departments
- Law Firms
- Government and Regulatory Agencies
- Alternative Legal Service Providers
- Educational Institutions
- Other End User Industries
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Singapore
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America held 38.67% of revenue in 2025. The region benefits from a high concentration of corporate legal departments, established adoption of enterprise legal management, and the presence of vendors such as Thomson Reuters, Mitratech, and Wolters Kluwer. LexisNexis CounselLink tracked nearly 1.8 million matters and more than USD 67 billion in legal spend in its 2025 trends report. It reported that some partner billing rates exceeded USD 1,000 per hour in selected practice areas. Rising legal costs encourage corporate departments to use the matter management software market to oversee outside counsel and make spending decisions.
Europe is the second-largest region and relies on compliance-related platform investment. The Wolters Kluwer Benchmark Study 2025 found that 41% of European legal departments used contract lifecycle management software, compared with 33% in 2024. It also found that 7% continued to manage contracts through paper archives. This leaves a meaningful opportunity for digitization across legal teams that still use fragmented processes in the matter management software market. Privacy rules and the European Union artificial intelligence framework influence procurement toward vendors that provide regional hosting and contractual data separation.
Asia-Pacific is projected to grow at a 16.54% CAGR through 2031, the fastest regional rate in the matter management software market. Judicial digitization in Japan and expansion of corporate legal functions in India are creating new users in both corporate departments and law firms. Huayu Yodex reported that its platform supported more than 40 legal document types and achieved more than 90% automatic case-data extraction accuracy in 2025. South America and Middle East and Africa remain smaller but growing areas, where uneven infrastructure favors cloud-based systems that require limited configuration.
- Thomson Reuters Corporation
- Wolters Kluwer N.V.
- Mitratech Holdings, Inc.
- RELX PLC
- Themis Solutions Inc.
- Onit, Inc.
- Relativity ODA LLC
- Litera Corp.
- iManage, LLC
- Aderant Holdings, Inc.
- Filevine, Inc.
- Anaqua, Inc.
- Everlaw, Inc.
- Rocket Matter, LLC
- Smokeball, Inc.
- Paradigm Corporation
- App4Legal, Inc.
- Legal Files Software, Inc.
- NetDocuments Software, Inc.
- Lexzur
- Xakia Technologies
- Brightflag, Inc.
- SimpleLegal, Inc.
- LawVu Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerating Cloud Migration in Legal Operations
- 4.2.2 Growing Demand for Legal Workflow Automation
- 4.2.3 Rising Regulatory and Privacy Compliance Requirements
- 4.2.4 Increasing Focus on Outside Counsel Spend Control
- 4.2.5 AI-Ready Matter Data as a Prerequisite for Legal Operations Modernization
- 4.2.6 Embedded Legal Operations Across Finance and Procurement Workflows
- 4.3 Market Restraints
- 4.3.1 Data Security and Client Confidentiality Concerns
- 4.3.2 Implementation Complexity and Legacy-System Integration Costs
- 4.3.3 Fragmented Matter Taxonomies Limiting AI Accuracy
- 4.3.4 Country-Specific Data Residency Requirements
- 4.4 Industry Value-Chain Analysis
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Regulatory Landscape
- 4.6.1 Data Protection and Privacy Regulations
- 4.6.2 Legal Professional Conduct and Confidentiality Rules
- 4.6.3 Electronic Records and Digital Evidence Requirements
- 4.6.4 Artificial Intelligence Governance Requirements
- 4.7 Technological Outlook
- 4.7.1 Generative Artificial Intelligence for Matter Summarization
- 4.7.2 Predictive Legal Spend Analytics
- 4.7.3 Intelligent Document Classification
- 4.7.4 Legal Hold and Preservation Automation
- 4.7.5 Application Programming Interface and Enterprise Integration
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Buyers
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Deployment
- 5.1.1 Cloud-Based
- 5.1.2 On-Premises
- 5.1.3 Hybrid
- 5.2 By Organization Size
- 5.2.1 Large Enterprises
- 5.2.2 Small and Medium-Sized Enterprises
- 5.3 By Matter Type
- 5.3.1 Litigation and Disputes
- 5.3.2 Commercial and Corporate Legal Matters
- 5.3.3 Compliance and Regulatory Matters
- 5.3.4 Intellectual Property Matters
- 5.3.5 Employment and Labor Matters
- 5.3.6 Claims and Investigations
- 5.4 By End User Industry
- 5.4.1 Corporate Legal Departments
- 5.4.2 Law Firms
- 5.4.3 Government and Regulatory Agencies
- 5.4.4 Alternative Legal Service Providers
- 5.4.5 Educational Institutions
- 5.4.6 Other End User Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 Australia
- 5.5.4.5 South Korea
- 5.5.4.6 Singapore
- 5.5.4.7 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 United Arab Emirates
- 5.5.5.1.2 Saudi Arabia
- 5.5.5.1.3 Israel
- 5.5.5.1.4 Turkey
- 5.5.5.1.5 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Egypt
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Thomson Reuters Corporation
- 6.4.2 Wolters Kluwer N.V.
- 6.4.3 Mitratech Holdings, Inc.
- 6.4.4 RELX PLC
- 6.4.5 Themis Solutions Inc.
- 6.4.6 Onit, Inc.
- 6.4.7 Relativity ODA LLC
- 6.4.8 Litera Corp.
- 6.4.9 iManage, LLC
- 6.4.10 Aderant Holdings, Inc.
- 6.4.11 Filevine, Inc.
- 6.4.12 Anaqua, Inc.
- 6.4.13 Everlaw, Inc.
- 6.4.14 Rocket Matter, LLC
- 6.4.15 Smokeball, Inc.
- 6.4.16 Paradigm Corporation
- 6.4.17 App4Legal, Inc.
- 6.4.18 Legal Files Software, Inc.
- 6.4.19 NetDocuments Software, Inc.
- 6.4.20 Lexzur
- 6.4.21 Xakia Technologies
- 6.4.22 Brightflag, Inc.
- 6.4.23 SimpleLegal, Inc.
- 6.4.24 LawVu Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


