

|
시장보고서
상품코드
2120366
역청 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Bitumen - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
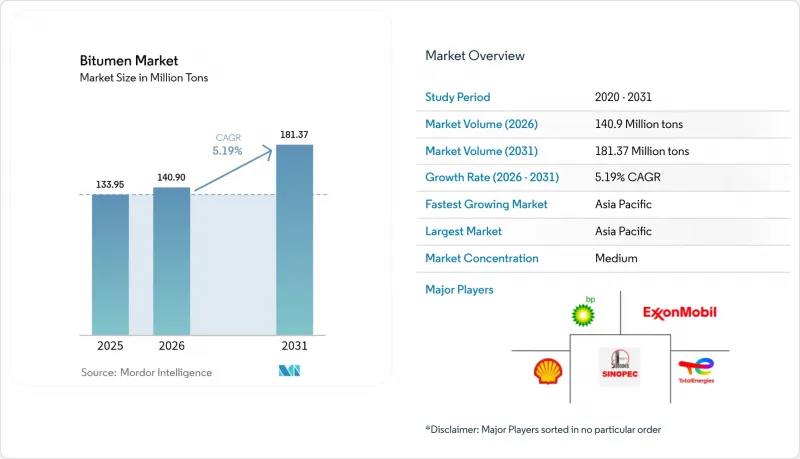
에 의하면, 역청 시장 규모는 2025년 1억 3,395만 톤으로 평가되었습니다. 2026년에는 1억 4,090만 톤으로 확대되어 2026년부터 2031년에 걸쳐 CAGR 5.19%로 성장을 지속하여, 2031년까지 1억 8,137만 톤에 이를 것으로 예측됩니다.
본 보고서는 제품 유형(침투 등급, 산화 등급, 역청 에멀젼, 폴리머 개질 역청, 기타), 용도(도로 건설, 지붕 자재, 접착제·실런트, 기타) 및 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 예측은 수량(톤) 기준으로 제시됩니다.
세계의 역청 시장 동향 및 인사이트
도로 및 고속도로 보수·개보수 비용 증가
각국 정부는 신규 건설에서 유지 관리로 예산을 재분배하고 있으며, 그 결과 침투성 바인더 및 특수 노면 처리재의 소비가 꾸준히 이어지고 있습니다. 미국의 ‘인프라 투자 및 고용법’에 따라 이미 6만 건 이상의 건설 프로젝트가 시작되었으며, 퀘벡주만 해도 2025-2026년도 예산에서 도로 정비에 358억 6,800만 캐나다 달러를 편성하고 있습니다. 각 기관은 적시에 보전에 1달러를 투자할 때마다 미래의 재건 비용을 4-7달러 절감할 수 있음을 인식하고 있으며, 이를 통해 유지 관리 수요의 선순환이 확립되고 있습니다. 독일의 5,000억 유로 규모의 현대화 기금에서는 자산 최적화에 20%를 배정하고 있으며, 기후 변화에 적응한 역청 등급 사양을 한층 더 높이는 회복탄력성 기준이 포함되어 있습니다. 포장 관리 시스템이 성숙해짐에 따라 조달 형태는 주기적인 수요 급증에서 예측 가능한 다년 계약으로 전환되어, 역청 시장 전체 수요량을 안정시키고 있습니다.
대규모 공항 활주로 확장 프로젝트
활주로 프로젝트에는 높은 바퀴 하중, 전단 응력 및 제트 연료 유출을 견딜 수 있는 고품질 결합재가 필요합니다. 걸프 지역 국가들과 아시아의 허브 공항들은 2030년까지 7,300억 달러 규모의 설비 투자 물결을 주도하고 있으며, 에너지 인프라와 항공 분야의 확장이 밀접하게 맞물려 있습니다. 프랑크푸르트 공항에서 2년에 걸쳐 실시된 캐슈넛 껍질 유래 바이오 역청를 사용한 시험 구간은 성능을 희생하지 않으면서 저탄소 소재를 추구하는 항공사들의 움직임을 여실히 보여주고 있습니다. 스티렌-부타디엔-스티렌(SBS)을 사용한 폴리머 개질 등급은 15-25%의 가격 프리미엄이 붙으며, 판매량은 여전히 적지만 이 부문의 수익성을 높이고 있습니다. 국제민간항공기구(ICAO) 기준에 부합하는 배합 설계 인증을 취득할 수 있는 공급업체는 장기적인 프레임워크 계약을 확보할 수 있는 입장에 있으며, 이를 통해 역청 시장에서의 수직 통합 전략이 강화되고 있습니다.
포장 공사에 대한 엄격한 온실가스(GHG) 및 다환 방향족 탄화수소(PAH) 배출 규제
규제 당국은 휘발성 유기 화합물(VOC) 및 다환 방향족 탄화수소(PAH)의 노출 한도치를 더욱 엄격하게 하고 있습니다. 캐나다에서는 2025년 10월까지 PAH 함량이 1,000 ppm을 초과하는 콜타르계 실란트의 사용이 금지되었으며, 이로 인해 기존 제품 카테고리가 사실상 배제되어 배합을 재검토할 수밖에 없게 되었습니다. 가스 크로마토그래피와 지도 학습을 결합한 예측 분석을 통해 현재는 악취의 원인이 되는 알칸을 특정할 수 있게 되어 규제 준수의 방향이 제시되는 한편, 소규모 생산자가 부담해야 할 분석 비용 증가를 초래하고 있습니다. 또한, 각 기관은 시공 온도를 최대 40°C 낮추는 웜믹스 기술을 권장하고 있으며, 이로 인해 현장에서의 배출량이 감소하고 핫믹스 역청의 운용 범위가 좁아짐에 따라 역청 시장 규모 확대가 제약받고 있습니다.
부문 분석
2025년 시점에서 침투용 바인더는 비투멘 시장 점유율의 66.52%를 차지했으며, 기존 핫믹스 플랜트와의 호환성과 폭넓은 기후 내성을 바탕으로 2031년까지 연평균 성장률(CAGR) 5.62%를 나타낼 것으로 예측됩니다. 산화 등급은 산화 안정성으로 인해 높은 가격 책정이 정당화되는 방수 및 지붕재와 같은 틈새 용도로 사용되고 있습니다. 전 세계적으로 800만 톤에 달하는 비투멘 에멀젼은 에너지 소비를 줄이고 작업 현장의 배출량을 감소시키기 때문에 칩 실링 및 마이크로 서피싱 분야에서 지지를 얻고 있습니다.
기술 혁신은 점도 제어와 친환경 첨가제에 초점을 맞추었습니다. 폴리인산을 1% 첨가하면 고온 안정성이 향상되지만, 2%를 초과하는 농도에서는 저장 안정성이 저하될 가능성이 있습니다. 이란산 천연 역청와 같은 바이오 개질제는 점도와 열가소성을 높이고 수명을 연장하는 동시에 합성 폴리머에 대한 의존도를 낮춥니다. 이러한 점진적인 개선을 통해 침투 등급의 우위는 유지되겠지만, 역청 시장 내에서는 점차 특수 배합 제품으로의 가치 전환이 진행되고 있습니다.
지역별 분석
아시아태평양은 2025년에 45.10%의 점유율로 1위를 차지했으며, 중국, 인도, 동남아시아의 협력적인 인프라 정비 계획에 힘입어 2031년까지 연평균 성장률(CAGR) 6.31%로 성장을 이어갈 전망입니다. 2023년 중국이 하루 1,480만 배럴의 원유를 정제한 것은 국내 역청 공급과 수출 능력 모두를 뒷받침하고 있습니다.
북미에서는 견조한 도로 보수 예산과 진화하는 환경 규제가 균형을 이루고 있습니다. IIJA(인플레이션 대응 및 인프라 법)에 따른 프로젝트가 수요를 안정시키고 있지만, 캐나다에서 곧 시행될 PAH(다환 방향족 탄화수소) 규제로 인해 에멀젼 및 저온 공정으로의 전환이 촉진되고 있습니다. 유럽에서는 정유시설의 합리화가 진행되고 있어, 폐쇄로 인해 지역 공급은 부족해지는 한편, 바이오 유래 대체재에 대한 시장 기회가 생겨나고 있습니다. 유럽의 비투멘 시장 규모는 톤수 기준으로는 소폭 축소될 가능성이 있으나, 특수 등급이 범용 등급을 상회함에 따라 금액 기준으로는 확대될 것으로 전망됩니다.
중동은 풍부한 원료와 전략적인 해운 노선을 활용하여 아시아에 공급하고 있습니다. 걸프 지역 생산자와 아시아 구매자 간의 무역액은 2030년까지 6,820억 달러에 달할 것으로 예측되며, 원유 유통 외에도 완제품용 결합제 및 개질제도 거래될 전망입니다.
아프리카와 남미는 여전히 신흥 시장이며, 수요의 급증으로 이어지는 간헐적인 메가 프로젝트가 특징입니다. 이 지역에서 인프라 구축에 대한 투자가 확대되는 가운데, 유연한 물류 체계와 신속한 대응이 가능한 공급업체는 시장에서 입지를 강화할 수 있을 것입니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.10According to Mordor Intelligence, the bitumen market size is expected to grow from 133.95 Million tons in 2025 to 140.9 Million tons in 2026 and is forecast to reach 181.37 Million tons by 2031 at 5.19% CAGR over 2026-2031.

This report is Segmented by Product Type (Penetration Grade, Oxidized Grade, Bitumen Emulsions, Polymer-Modified Bitumen, and Other Products), Application (Road Construction, Roofing, Adhesives and Sealants, and Other Applications), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Volume (Tons).
Global Bitumen Market Trends and Insights
Increasing Road and Highway Rehabilitation Spend
Governments are reallocating budgets from new builds toward preservation, leading to steady recurrent consumption of penetration-grade binders and specialty surface treatments. The U.S. Infrastructure Investment and Jobs Act has already launched more than 60,000 construction projects, and Quebec alone earmarked CAD 35.868 billion for roads in its 2025-2026 budget. Agencies recognize that every dollar invested in timely preservation avoids USD 4-7 in future reconstruction costs, locking in a virtuous cycle of maintenance demand. Germany's EUR 500 billion modernization fund assigns 20% to asset optimization, embedding resilience criteria that further elevate specifications for climate-adaptive bitumen grades. As pavement management systems mature, procurement shifts from cyclical surges to predictable multi-year contracts, stabilizing volume offtake across the bitumen market.
Large-Scale Airport Runway Expansion Programs
Runway projects require premium binders that tolerate high wheel loads, shear stresses, and jet-fuel spills. Gulf and Asian hubs are leading a USD 730 billion capex wave through 2030, intertwining energy infrastructure with aviation build-outs. Frankfurt Airport's two-year test strip using cashew-shell bio-bitumen illustrates airlines' push for lower-carbon materials without performance sacrifice. Polymer-modified grades with styrene-butadiene-styrene command price premiums of 15-25%, lifting segment profitability even though volumes remain modest. Suppliers capable of certifying mix designs to International Civil Aviation Organization standards are positioned to capture long-run framework agreements, reinforcing vertical integration strategies within the bitumen market.
Stringent GHG and PAH Emission Regulations on Paving Operations
Regulators are tightening exposure limits for volatile organic compounds and polycyclic aromatic hydrocarbons. Canada will prohibit coal-tar sealants exceeding 1,000 ppm PAHs by October 2025, effectively removing a traditional product class and forcing reformulations. Predictive analytics using gas chromatography coupled with supervised learning now pinpoint odor-causing alkanes, offering compliance pathways but raising analytical costs that smaller producers must absorb. Agencies also favor warm-mix technologies that lower placement temperatures by up to 40 °C, reducing on-site emissions and tightening the operating envelope for hot-mix asphalt, thereby constraining volume expansion in the bitumen market.
Other drivers and restraints analyzed in the detailed report include:
- Government Infrastructure Stimulus in Emerging Economies
- Shift to Polymer-Modified Bitumen for Climate-Resilient Pavements
- Crude-Oil Price Volatility Impacting Feedstock Economics
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Penetration-grade binders held 66.52% of the bitumen market share in 2025 and are projected to grow at a 5.62% CAGR through 2031, sustained by compatibility with conventional hot-mix plants and broad climatic tolerance. Oxidized grades occupy niche waterproofing and roofing roles where oxidation stability justifies premium pricing. Bitumen emulsions, totaling 8 million tons globally, are gaining favor for chip seals and microsurfacing because they reduce energy use and lower work-zone emissions.
Innovation centers on viscosity control and ecological additives. Polyphosphoric acid at 1% dosage improves high-temperature stability, though concentrations beyond 2% can undermine storage stability. Bio-based modifiers such as Iranian natural asphalt enhance viscosity and thermoplasticity, extending service life and reducing reliance on synthetic polymers. These incremental gains sustain penetration-grade primacy but gradually shift value toward specialty formulations inside the bitumen market.
Complete Report Scope:
- By Product Type
- Penetration Grade
- Oxidized Grade
- Bitumen Emulsions
- Polymer-Modified Bitumen
- Other Products (Viscosity Grade, Cutback, and Performance Grade)
- By Application
- Road Construction
- Roofing
- Adhesives and Sealants
- Other Applications (Coatings in Sectors such as Oil and Gas, Canal Lining, Tank Foundation, Railway Ballast Treatment, and Others)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Rest of Asia-Pacific
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific led with 45.10% share in 2025 and is advancing at a 6.31% CAGR to 2031, anchored by synchronized infrastructure programs across China, India, and Southeast Asia. China's processing of 14.8 million barrels per day of crude in 2023 underpins both domestic asphalt supply and export capabilities.
North America balances robust rehabilitation budgets with evolving environmental mandates. The IIJA pipeline stabilizes demand, but Canada's impending PAH restrictions catalyze a shift to emulsions and cold processes. Europe confronts refinery rationalization; closures tighten regional supply yet open market space for bio-based alternatives. The bitumen market size in Europe could contract marginally in tonnage yet expand in value as specialty grades outpace generic ones.
The Middle East leverages abundant feedstock and strategic shipping lanes to supply Asia. Trade between Gulf producers and Asian buyers is forecast to touch USD 682 billion by 2030, with finished binders and modifiers joining crude flows.
Africa and South America remain emergent, characterized by episodic megaprojects that create demand surges. Suppliers attuned to flexible logistics and rapid deployment can gain traction as these regions scale connectivity investments.
- BMI Group Holdings UK Limited
- BP p.l.c.
- China Petroleum and Chemical Corporation (Sinopec)
- ENEOS Corporation
- Exxon Mobil Corporation
- Hindustan Petroleum Corporation Limited
- Indian Oil Corporation Ltd
- Kraton Corporation
- Mangalore Refinery and Petrochemicals Limited
- Marathon Petroleum Corporation
- Nynas AB
- Rosneft
- Shell plc
- Suncor Energy Inc.
- The Bouygues Group
- TotalEnergies
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing road and highway rehabilitation spend
- 4.2.2 Large-scale airport runway expansion programs
- 4.2.3 Government infrastructure stimulus in emerging economies
- 4.2.4 Shift to polymer-modified bitumen for climate-resilient pavements
- 4.2.5 Circular-economy push for reclaimed asphalt pavement (RAP) adoption
- 4.3 Market Restraints
- 4.3.1 Stringent GHG and PAH emission regulations on paving operations
- 4.3.2 Crude-oil price volatility impacting feedstock economics
- 4.3.3 Rising share of concrete and composite pavements in urban projects
- 4.4 Value Chain Analysis
- 4.5 Feedstock Analysis
- 4.6 Porter's Five Forces
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Product Type
- 5.1.1 Penetration Grade
- 5.1.2 Oxidized Grade
- 5.1.3 Bitumen Emulsions
- 5.1.4 Polymer-Modified Bitumen
- 5.1.5 Other Products (Viscosity Grade, Cutback, and Performance Grade)
- 5.2 By Application
- 5.2.1 Road Construction
- 5.2.2 Roofing
- 5.2.3 Adhesives and Sealants
- 5.2.4 Other Applications (Coatings in Sectors such as Oil and Gas, Canal Lining, Tank Foundation, Railway Ballast Treatment, and Others)
- 5.3 By Geography
- 5.3.1 North America
- 5.3.1.1 United States
- 5.3.1.2 Canada
- 5.3.1.3 Mexico
- 5.3.2 South America
- 5.3.2.1 Brazil
- 5.3.2.2 Argentina
- 5.3.2.3 Colombia
- 5.3.2.4 Rest of South America
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Rest of Europe
- 5.3.4 Asia-Pacific
- 5.3.4.1 China
- 5.3.4.2 India
- 5.3.4.3 Japan
- 5.3.4.4 South Korea
- 5.3.4.5 ASEAN
- 5.3.4.6 Rest of Asia-Pacific
- 5.3.5 Middle East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle East and Africa
- 5.3.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (MandA/JV/Agreements)
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 BMI Group Holdings UK Limited
- 6.4.2 BP p.l.c.
- 6.4.3 China Petroleum and Chemical Corporation (Sinopec)
- 6.4.4 ENEOS Corporation
- 6.4.5 Exxon Mobil Corporation
- 6.4.6 Hindustan Petroleum Corporation Limited
- 6.4.7 Indian Oil Corporation Ltd
- 6.4.8 Kraton Corporation
- 6.4.9 Mangalore Refinery and Petrochemicals Limited
- 6.4.10 Marathon Petroleum Corporation
- 6.4.11 Nynas AB
- 6.4.12 Rosneft
- 6.4.13 Shell plc
- 6.4.14 Suncor Energy Inc.
- 6.4.15 The Bouygues Group
- 6.4.16 TotalEnergies
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment


