

|
시장보고서
상품코드
2120636
정제 촉매 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Refining Catalysts - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
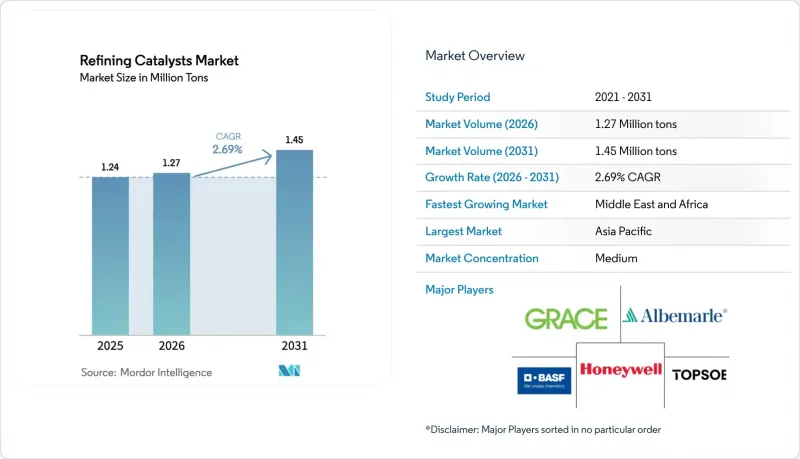
정제 촉매 시장 규모는 2025년에 124만 톤으로 평가되었습니다. 2026년 127만 톤에서 2031년까지 145만 톤에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 2.69%를 나타낼 전망입니다.
본 보고서는 제품 유형(CoMo, Nimo, 알루미나계 귀금속, Niw, 제올라이트, 기타), 공정(수소화 처리, 유동 접촉 분해, 잔사 유동 접촉 분해, 수소화 분해) 및 지역(북미, 남미, 유럽, 아시아태평양, 중동 및 아프리카)별로 분류되어 있습니다. 시장 전망은 수량(톤) 단위로 제시되어 있습니다.
세계의 정제 촉매 시장 동향 및 인사이트
전 세계 황 함량 규제 강화
2020년 1월부터 시행되고 있는 국제해사기구(IMO)의 선박용 연료에 대한 0.50% 황 함량 상한 규제는 현재, 규정을 준수하는 벙커 블렌드를 공급하기 위해 잔류유 흐름을 수소화 처리하고 있는 연안 정유시설에 여전히 영향을 미치고 있습니다. 2024년에 시행된 중국의 전국적인 ‘중국 VI’ 휘발유 및 디젤 기준에서는 황 함량이 10 ppm으로 제한되어 있으며, 이로 인해 국영 정유사는 하루 약 120만 배럴의 처리 능력에 해당하는 수소화 처리 능력을 증강해야만 했습니다. 미국 환경보호청(EPA)의 Tier 3 휘발유 프로그램 역시 10 ppm 상한선을 유지하고 있어, 적정한 수소 분압 하에서 고도의 탈황을 실현하는 귀금속-알루미나 촉매에 대한 수요를 뒷받침하고 있습니다. 유럽의 연료 품질 지침도 마찬가지로 10 ppm 기준을 채택하고 있어, 유럽 전역에서 NiMo 및 CoMo 수요를 뒷받침하고 있습니다. 여러 규제 기한이 겹치면서, 이러한 규제가 중첩됨에 따라 주로 2026년까지 연평균 성장률(CAGR)이 0.8퍼센트 포인트 상승할 것으로 전망됩니다.
아시아태평양 및 중동의 정유 능력 확대
중국, 인도, 사우디아라비아, 쿠웨이트의 그린필드 및 브라운필드 프로젝트로 인해 2024년부터 2028년까지 원유 증류 능력이 하루 약 300만 배럴 증가할 것으로 예상되며, 이로 인해 FCC, 수소화 처리, 수소화 분해 설비에 수 톤 규모의 촉매 충전량이 필요하게 됩니다. 사우디 아람코와 중국석유화공집단(시노펙)의 푸젠성 복합단지는 완전 가동 시 연간 약 1만 2,000톤의 제올라이트계 FCC 촉매를 소비할 것으로 예상되는 반면, 인도의 파니파트, 구자라트,바라우니의 확장 프로젝트는 2027년까지 현지 수소화 처리용 촉매 수요를 끌어올릴 것입니다. 쿠웨이트의 알-주르 정유시설는 하루 61만 5,000배럴의 중질 원유를 처리하고 있으며, 중간 증류분의 수율을 극대화하기 위해 NiW 및 CoMo 잔류물 수소화 분해 촉매에 의존하고 있습니다. 이러한 건설 프로젝트들이 합쳐져 예측 연평균 성장률(CAGR)을 0.9포인트 끌어올릴 것이며, 2026년부터 2028년에 걸쳐 이러한 신규 설비들이 정격 처리 능력에 도달함에 따라 정점을 맞이할 것입니다.
코발트, PGM 및 기타 주요 금속의 가격 변동
2025년에는 콩고 민주 공화국공급 부족으로 코발트 가격이 18% 상승한 반면, 남아프리카공화국의 생산 제한을 배경으로 백금과 팔라듐은 12% 상승했습니다. 중량 기준으로 2-4%의 코발트를 함유한 CoMo 수소화 처리 촉매는 규제된 연료 가격으로 인해 비용 전가가 제한되어 마진 압박에 직면해 있습니다. 백금 함유 개질 촉매도 유사한 압박에 직면해 있습니다. 팔라듐 가격이 10% 상승하면 완제품 촉매의 비용은 1kg당 약 50달러 증가합니다. 공급업체들은 가격 변동의 영향을 완화하기 위해 코발트를 포함하지 않는 NiW계 촉매 개발 및 재활용 가속화에 나서고 있지만, 상용화까지는 2-3년이 소요될 가능성이 있습니다. 가격 변동으로 인해 기본 연평균 성장률(CAGR)은 0.4% 하락할 것이며, 정유시설가 촉매 교체 주기를 연장함에 따라 그 영향은 2024년부터 2026년에 걸쳐 가장 두드러질 것으로 전망됩니다.
부문별 분석
제올라이트는 2025년에 정제 촉매 시장 점유율의 96.01%를 차지했으며, 2031년까지 연평균 2.72%의 성장이 예상됩니다. 이러한 압도적인 우위는 정제 촉매 시장이 진공 가스오일을 가솔린, 디젤, 경질 올레핀으로 분해하는 FCC(유동 접촉 분해) 공정을 중심으로 돌아가고 있음을 여실히 보여줍니다. 희토류 Y 제올라이트는 라이저 온도 500°C-550°C 범위에서 여전히 주력 제품인 반면, ZSM-5 첨가제는 프로파일렌 생산량을 끌어올렸습니다. CoMo 촉매는 주로 고황 원료를 처리하는 아시아 및 중동의 수소화 처리 설비에서 사용되고 있습니다. NiMo 배합 촉매는 항공 연료 정제업체들이 등유 탈황에 선호하여 채택하고 있습니다. 알루미나 지지체 귀금속 제품은 귀금속의 휘발성으로 인해 보급이 제한되고 있어, 개질 용도에서 틈새 시장 역할을 하고 있습니다. NiW 촉매는 중질 원유 산지에서 잔사의 수소화 분해에 일반적으로 사용되고 있습니다. 금속-유기 골격체(MOF)와 같은 실험적인 해결책도 모색되고 있습니다. 클라리언트(Clariant)사가 2025년에 출시한 미세공과 메조공을 결합한 계층형 제올라이트는 이 주요 부문에서의 점진적인 혁신을 여실히 보여주고 있습니다.
전기자동차의 보급으로 인한 영향이 있음에도 불구하고, 향후 교체 주기는 제올라이트 첨가제에 대한 지속적인 수요를 뒷받침하고 있습니다. 석유화학 통합을 목적으로 설계된 아시아태평양의 FCC 플랜트에서는 ZSM-5의 사용량 증가가 요구되는 반면, 중동의 잔류 수소 분해 플랜트에서는 내금속성이 강화된 NiW 계열이 선호되고 있어 시장의 다변화가 진행되고 있습니다. 파일럿 시험 단계에 있는 코발트 프리 NiW 배합은 향후 디젤 수소 처리 장치에서 CoMo 계열 시장 점유율을 잠식할 가능성이 있지만, 2028년 이전의 상용화는 기대하기 어려우므로 예측 기간 중반까지는 안정적인 경쟁 구도가 지속될 것으로 예측됩니다.
지역별 분석
2025년, 아시아태평양은 전 세계 정제 촉매 시장의 52.03%를 차지했습니다. 중국 및 사우디 아람코의 푸젠성 복합 단지는 최종적으로 연간 1만 2,000톤의 제올라이트를 소비하게 될 것이며, 인도의 확장 계획은 알베마르(Albemarle)사와의 4,500만 달러 규모의 계약에 따라 수소화 분해 수요를 크게 끌어올릴 전망입니다. 인도네시아, 베트남, 태국의 동남아시아 프로젝트는 2028년까지 하루 약 50만 배럴의 증류 능력을 추가하여 수소화 처리 및 FCC 기회를 확대할 것입니다.
북미와 유럽에서는 정유시설 가동 중단과 전기차 보급에 따른 휘발유 수요 감소에 직면해 있습니다. 2019년부터 2025년에 걸쳐 유럽의 휘발유 수요가 6% 감소할 전망이며, 북미에서 프로파일렌 및 디젤 연료 생산 라인으로의 재편은 촉매 사양의 재검토를 초래할 뿐, 수요 증가로 이어지지는 않을 것입니다. 미국의 Tier 3 규제로 인해 귀금속 수요는 안정적이며, 캐나다의 오일샌드 업그레이더는 특수한 하이드로크래킹 수요를 유지하고 있습니다. 그러나 이러한 성숙한 지역의 정제 촉매 시장은 플랜트 합리화가 생산 라인 업그레이드를 상쇄하고 있어 정체 상태를 이어가고 있습니다.
남미에서는 2027년 가동이 예정된 아르헨티나의 라 플라타 수소분해 설비가 연간 600톤의 새로운 수요를 창출할 것입니다. 이러한 증가분으로 인해 절대량 측면에서는 아시아가 여전히 우위를 유지하겠지만, 성장률 측면에서는 남미 지역이 주도적인 위치를 공고히할 것입니다.
중동 및 아프리카에서는 정제 촉매 수요가 크게 증가하고 있으며, 2026년부터 2031년까지 연평균 성장률(CAGR)이 2.78%로 가장 높은 성장세를 보이고 있습니다. 사우디아라비아의 ‘액체에서 화학물질로의 전환’ 전략과 쿠웨이트의 알-주르 중질 원유 플랫폼 덕분에 잔류물 수소화 분해용 촉매에 대한 안정적인 수요가 창출되고 있습니다. 아프리카에서는 나이지리아의 일일 65만 배럴 규모 단고테 정유시설가 장기적인 성장의 원동력이 되고 있습니다. 해당 정유시설가 2026년에 본격적으로 가동되면 연간 약 5,000톤의 FCC 및 수소화 처리 촉매가 필요할 것으로 전망됩니다. 또한, 남아프리카공화국의 세쿤다 정유시설 내 가스 전환 설비의 개보수를 통해 수소화 처리량은 15% 증가할 것으로 예측됩니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, the refining catalysts market size was valued at 1.24 Million tons in 2025 and is estimated to grow from 1.27 Million tons in 2026 to reach 1.45 Million tons by 2031, at a CAGR of 2.69% during the forecast period (2026-2031).
This report is Segmented by Product Type (CoMo, Nimo, Alumina-Based Noble Metal, Niw, Zeolites, and Other Products), Process (Hydrotreating, Fluid Catalytic Cracking, Residue Fluid Catalytic Cracking, and Hydrocracking), and Geography (North America, South America, Europe, Asia-Pacific, and Middle East and Africa). Market Forecasts are Provided in Terms of Volume (Tons).
Global Refining Catalysts Market Trends and Insights
Stricter Global Sulfur-Cap Regulations
The International Maritime Organization's 0.50% sulfur limit for marine fuels, effective since January 2020, still reverberates across coastal refineries that now hydrotreat residual streams to supply compliant bunker blends. China's nationwide China VI gasoline and diesel standards, implemented in 2024, limit sulfur to 10 ppm and forced state-owned refiners to add hydrotreating capacity equal to nearly 1.2 million barrels per day of throughput. The United States Environmental Protection Agency's Tier 3 gasoline program maintains a comparable 10 ppm cap, bolstering demand for noble-metal alumina catalysts that reach deep desulfurization under moderate hydrogen partial pressures. Europe's Fuel Quality Directive replicates the 10 ppm threshold, reinforcing NiMo and CoMo demand throughout the continent. Overlapping mandates deliver a 0.8 percentage-point uplift to the base CAGR mainly through 2026 as multiple deadlines converge.
Refinery Capacity Build-Out in Asia-Pacific and Middle East
Greenfield and brownfield projects in China, India, Saudi Arabia, and Kuwait add roughly 3 million barrels per day of crude distillation between 2024 and 2028, translating into multi-ton catalyst charges for FCC, hydrotreating, and hydrocracking units. Saudi Aramco and China Petrochemical Corporation's Fujian complex will consume an estimated 12,000 tons of zeolite FCC catalysts annually at full stride, while India's Panipat, Gujarat, and Barauni expansions boost local hydrotreating demand through 2027. Kuwait's Al-Zour refinery processes 615,000 barrels per day of heavy crude, relying on NiW and CoMo residue hydrocracking catalysts to maximize middle-distillate yields. The combined build-out contributes a 0.9 percentage-point push to the forecast CAGR, peaking as these new units reach nameplate throughput over 2026-2028.
Volatility in Cobalt, PGMs, and Other Critical Metals
Cobalt prices rose 18% in 2025 on tight supply from the Democratic Republic of Congo, while platinum and palladium climbed 12% amid South African output curbs. CoMo hydrotreating catalysts that contain 2-4% cobalt by weight face margin compression because regulated fuel prices limit pass-through. Platinum-bearing reforming catalysts see similar strain: a 10% palladium rise inflates finished-catalyst cost by roughly USD 50 per kilogram. Suppliers pursue cobalt-free NiW chemistries and accelerate recycling to cushion volatility, yet commercialization may take two to three years. Price swings trim 0.4 percentage points from the base CAGR, with most impact between 2024 and 2026 as refiners lengthen change-out intervals.
Other drivers and restraints analyzed in the detailed report include:
- Rising Demand for Higher-Octane Gasoline and Petro-Feedstocks
- Bio-Feed Co-Processing Needs Dual-Function Catalysts
- EV Penetration Curbing Long-Term Gasoline Demand
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Zeolites captured 96.01% of the refining catalysts market share in 2025 and are expected to grow 2.72% annually through 2031. This extensive dominance underscores how the refining catalysts market revolves around FCC operations that crack vacuum gas oil into gasoline, diesel, and light olefins. Rare-earth Y-zeolites remain the workhorse at riser temperatures of 500 °C-550 °C, while ZSM-5 additives lifted propylene production. CoMo catalysts are primarily utilized in Asian and Middle Eastern hydrotreaters processing high-sulfur feeds. NiMo formulations are preferred by aviation fuel refiners for kerosene desulfurization. Alumina-supported noble-metal products play a niche role in reforming applications, as the volatility of precious metals limits broader adoption. NiW catalysts are commonly used for residue hydrocracking in heavy-crude regions. Experimental solutions, such as metal-organic frameworks, are also being explored. Clariant's planned 2025 launch of a hierarchical zeolite combining micro- and mesopores highlights incremental innovation within the dominant segment.
The upcoming replacement cycle underscores the sustained demand for zeolite formulations, despite the impact of electric vehicle adoption. Asia-Pacific FCC units designed for petrochemical integration are specifying higher ZSM-5 doses, while Middle Eastern residue hydrocrackers are favoring NiW systems with enhanced metal tolerance, contributing to market diversity. Cobalt-free NiW formulations entering pilot trials may eventually capture share from CoMo in diesel hydrotreaters, but commercialization is unlikely before 2028, suggesting a stable competitive mix through the midpoint of the forecast window.
Complete Report Scope:
- By Product Type
- CoMo
- NiMo
- Alumina-based Noble Metal
- NiW
- Zeolites
- Other Products
- By Process
- Hydrotreating
- Gasoline
- Kerosene
- Diesel
- Vacuum Gas Oil
- Catalytic-Cracking Gasoline
- Residual Feed
- Fluid Catalytic Cracking (FCC)
- Residue Fluid Catalytic Cracking (RFCC)
- Hydrocracking
- Hydrotreating
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- Italy
- France
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- Middle-East and Africa
- South Africa
- Saudi Arabia
- Rest of Middle-East and Africa
- North America
Geography Analysis
Asia-Pacific accounted for a 52.03% share of the global refining catalyst market in 2025. China and Saudi Aramco's Fujian complex will eventually draw 12,000 tons of zeolite annually, and Indian expansions add significant hydrocracking demand under Albemarle's USD 45 million contract. Southeast Asian projects in Indonesia, Vietnam, and Thailand add about 500,000 barrels per day of distillation capacity through 2028, broadening hydrotreating and FCC opportunities.
North America and Europe face refinery shutdowns and electric-vehicle-driven gasoline decline. Europe's 6% gasoline retreat from 2019-2025 and North American unit reconfiguration toward propylene and diesel reshape catalyst specifications rather than spark volume growth. The United States Tier 3 rule keeps noble-metal demand steady, and Canada's oil-sands upgraders sustain specialized hydrocracking volume. Yet the refining catalysts market in these mature regions edges sideways as plant rationalization offsets unit upgrades.
In South America, Argentina's La Plata hydrocracker, scheduled for 2027, adds 600 tons of annual demand. These incremental additions solidify the region's leadership in growth rate terms, even if Asia alone retains absolute volume dominance.
The Middle East and Africa are witnessing a significant rise in demand for refining catalysts with the fastest 2.78% CAGR from 2026 to 2031. Saudi Arabia's liquids-to-chemicals agenda and Kuwait's Al-Zour heavy-crude platform generate constant demand for residue hydrocracking catalysts. Africa presents long-term upside through Nigeria's 650,000 barrels-per-day Dangote refinery, which when fully loaded in 2026 will require roughly 5,000 tons of FCC and hydrotreating catalysts each year. South Africa's Secunda gas-conversion retrofit will lift hydrotreating volume by 15%.
- Albemarle Corporation
- Axens
- BASF SE
- China Petrochemical Corporation
- Clariant
- CLG
- Evonik
- Exxon Mobil Corporation
- Honeywell International
- JGC C & C
- Johnson Matthey
- KNT Group
- Kuwait Catalyst Company
- Rezel Catalysts Corporation
- Shell plc
- Topsoe
- Umicore
- W. R. Grace & Co.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Stricter global sulfur-cap regulations
- 4.2.2 Refinery capacity build-out in Asia-Pacific and Middle East
- 4.2.3 Rising demand for higher-octane gasoline and petro-feedstocks
- 4.2.4 Bio-feed co-processing needs dual-function catalysts
- 4.2.5 AI-driven catalyst performance analytics adoption
- 4.3 Market Restraints
- 4.3.1 Volatility in cobalt, PGMs and other critical metals
- 4.3.2 EV penetration curbing long-term gasoline demand
- 4.3.3 Crude-to-chemicals complexes bypass traditional units
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Product Type
- 5.1.1 CoMo
- 5.1.2 NiMo
- 5.1.3 Alumina-based Noble Metal
- 5.1.4 NiW
- 5.1.5 Zeolites
- 5.1.6 Other Products
- 5.2 By Process
- 5.2.1 Hydrotreating
- 5.2.1.1 Gasoline
- 5.2.1.2 Kerosene
- 5.2.1.3 Diesel
- 5.2.1.4 Vacuum Gas Oil
- 5.2.1.5 Catalytic-Cracking Gasoline
- 5.2.1.6 Residual Feed
- 5.2.2 Fluid Catalytic Cracking (FCC)
- 5.2.3 Residue Fluid Catalytic Cracking (RFCC)
- 5.2.4 Hydrocracking
- 5.2.1 Hydrotreating
- 5.3 By Geography
- 5.3.1 North America
- 5.3.1.1 United States
- 5.3.1.2 Canada
- 5.3.1.3 Mexico
- 5.3.2 South America
- 5.3.2.1 Brazil
- 5.3.2.2 Argentina
- 5.3.2.3 Rest of South America
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 Italy
- 5.3.3.4 France
- 5.3.3.5 Spain
- 5.3.3.6 Russia
- 5.3.3.7 Rest of Europe
- 5.3.4 Asia-Pacific
- 5.3.4.1 China
- 5.3.4.2 India
- 5.3.4.3 Japan
- 5.3.4.4 South Korea
- 5.3.4.5 ASEAN Countries
- 5.3.4.6 Rest of Asia-Pacific
- 5.3.5 Middle-East and Africa
- 5.3.5.1 South Africa
- 5.3.5.2 Saudi Arabia
- 5.3.5.3 Rest of Middle-East and Africa
- 5.3.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Albemarle Corporation
- 6.4.2 Axens
- 6.4.3 BASF SE
- 6.4.4 China Petrochemical Corporation
- 6.4.5 Clariant
- 6.4.6 CLG
- 6.4.7 Evonik
- 6.4.8 Exxon Mobil Corporation
- 6.4.9 Honeywell International
- 6.4.10 JGC C & C
- 6.4.11 Johnson Matthey
- 6.4.12 KNT Group
- 6.4.13 Kuwait Catalyst Company
- 6.4.14 Rezel Catalysts Corporation
- 6.4.15 Shell plc
- 6.4.16 Topsoe
- 6.4.17 Umicore
- 6.4.18 W. R. Grace & Co.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment


