

|
시장보고서
상품코드
2124469
미국의 매니지드 서비스 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)United States Managed Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
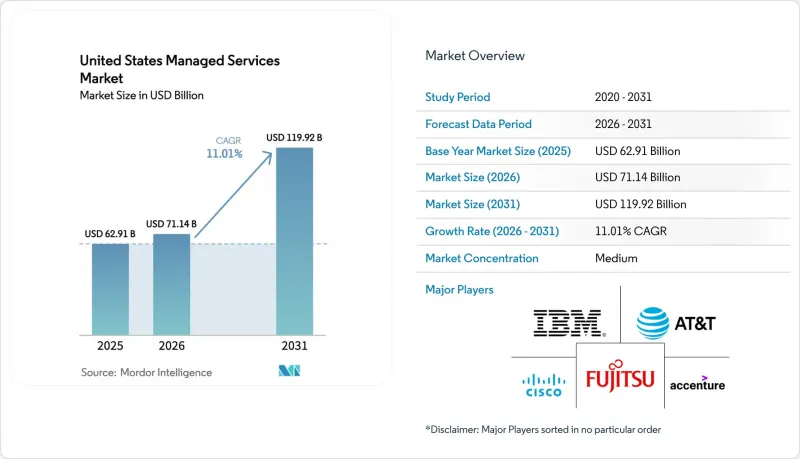
에 의하면, 미국의 매니지드 서비스 시장 규모는 2025년 629억 1,000만 달러, 2026년 711억 4,000만 달러에서 2031년까지 1,199억 2,000만 달러에 이르고, 2026-2031년 연평균 복합 성장률(CAGR)은 11.01%를 기록할 전망입니다.
본 보고서는 도입 형태(On-Premise, 클라우드), 서비스 유형(매니지드 데이터센터, 매니지드 보안, 매니지드 커뮤니케이션, 매니지드 네트워크 등), 기업 규모(중소기업, 대기업),최종 사용자 업종(IT 및 통신, 의료, 엔터테인먼트·미디어, 소매 등)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
미국의 매니지드 서비스 시장 동향 및 인사이트
기업들의 하이브리드 클라우드 관리로의 전환이 진행 중
미국 기업들은 On-Premise 데이터센터, 여러 퍼블릭 클라우드, 엣지 거점을 결합한 하이브리드 아키텍처를 운영하고 있지만, 비용과 보안을 최적화할 수 있는 사내 전문 지식을 보유한 기업은 3분의 1 미만에 그치고 있습니다. 이러한 환경에서는 구성 드리프트가 40-60% 증가하여 취약성이 발생하지만, 매니지드 서비스 제공업체(MSP)는 통합된 정책 적용과 워크로드 자동 배치를 제공함으로써 이러한 취약성을 비즈니스 기회로 전환하고 있습니다. OCC(통화감독청)의 지침에 따라 모든 중요한 제3자 의존성에 대한 복원력 테스트가 의무화됨에 따라 은행들이 도입을 주도하고 있습니다. 그 결과, 모니터링과 장애 조치 오케스트레이션을 통합하는 MSP는 인프라와 보안 서비스를 결합한 다년 계약을 수주하고 있습니다.
멀티클라우드의 복잡성이 가속화되며, 통합된 MSP에 대한 수요를 견인
현재 평균적인 기업은 3.2개의 퍼블릭 클라우드 플랫폼을 운영하고 있으며, 이는 2022년의 2.1개에서 증가한 수치입니다. 신원 및 접근 관리의 분산화로 인해 공격 표면이 확대되고 있습니다. 베라이즌은 2024년 클라우드 침해 사고의 34%가 권한 설정 오류에서 비롯되었다고 지적했습니다. 통합형 MSP는 AWS, Azure, Google Cloud를 스캔하여 Center for Internet Security(CIS) 벤치마크와의 편차를 감지하는 클라우드 보안 태세 관리 도구를 도입하고 있습니다. 소매업체와 의료 서비스 제공업체는 고객용 앱이 클라우드로 이전되고 있는 반면, 결제 시스템과 전자 건강 기록(EHR) 시스템은 여전히 On-Premise에 남아 있어 압박을 느끼고 있습니다. 각 하이퍼스케일러의 독자적인 스택에 정통한 전문가의 연봉이 18만 달러를 초과하여 중소기업의 예산을 훨씬 상회하는 상황에서 아웃소싱은 합리적인 선택지가 됩니다.
기술 인력 부족이 미국 MSP의 인건비를 상승시키고 있다.
CyberSeek의 조사에 따르면, 2025년에는 45만 건의 사이버 보안 관련 채용 공고가 채워지지 않을 전망입니다. 클라우드 보안 아키텍트의 보수 중앙값은 2023년 이후 22% 상승하여, 매니지드 네트워크 운영 등 노동 집약적인 서비스 라인의 이익률을 압박하고 있습니다. 서비스 제공업체들은 AI-Ops에 투자하여 엔지니어 1인당 관리하는 디바이스 수를 개선할지, 아니면 수익성 저하를 감수할지 선택의 기로에 서 있습니다. 독자적인 자동화 기술을 보유한 대형 MSP는 비용 면에서 우위를 점하고 있지만, 소규모 기업들은 업계 재편의 압박에 직면해 있습니다.
부문 분석
2025년, 미국의 매니지드 서비스 시장에서 클라우드 기반 서비스는 63.41%의 점유율을 차지할 것이며, 2031년까지 연평균 성장률(CAGR) 11.49%를 나타낼 것으로 예측됩니다. 하이퍼스케일러의 약정형 할인으로 인해, 다년 계약의 클라우드 비용은 감가상각이 완료된 On-Premise형 하드웨어와 동등한 수준까지 낮아져, 설비 투자 측면에서의 우위는 사라졌습니다. 따라서 클라우드 도입을 대상으로 하는 미국의 매니지드 서비스 시장은 2031년까지 750억 달러를 넘어설 전망인 반면, On-Premise 시장의 성장률은 한 자릿수에 머물며 성장 부진이 지속될 것으로 예측됩니다. On-Premise 솔루션은 국방 관련 계약, 고빈도 거래, 의료 영상 진단 분야에서 여전히 사용되고 있지만, 이러한 업계조차도 하이브리드 모델을 채택하고 있으며, 지연 시간에 대한 허용도가 높은 워크로드는 퍼블릭 클라우드로 이전하는 한편, 데이터 주권에 민감한 용도는 로컬 환경에 유지하고 있습니다.
성능 차이는 클라우드로의 이전 추세를 더욱 가속화하고 있습니다. Azure 기반 관리형 서비스는 On-Premise형 서비스에 비해 랜섬웨어를 평균 14시간 더 빨리 감지합니다. CFO들은 감지 지연으로 인한 기회 손실을 정량화하려는 경향이 강해지고 있으며, 마이그레이션을 통한 비용 절감 효과가 이미 투자된 하드웨어 비용을 상회한다고 결론짓고 있습니다. 수천 개의 테넌트에서 집계된 위협 텔레메트리 데이터가 머신 러닝 모델을 개선함에 따라 클라우드의 우위는 더욱 커지고, 더 많은 기업이 종량제 계약에 묶이게 될 것입니다.
관리형 보안 서비스는 2031년까지 연평균 성장률(CAGR) 12.13%를 나타낼 것으로 예측되며, 미국 관리형 서비스 시장 전체를 능가하는 속도로 확대되고 있습니다. 평균 454만 달러에 달하는 보안 침해 비용을 배경으로, 이사회는 지속적인 모니터링을 ‘재량적 지출’이 아닌 ‘사업 지속을 위한 필수 요소’로 인식하고 있습니다. 매니지드 데이터센터 서비스는 2025년에 24.68%의 점유율을 차지했으나, 하이퍼스케일러에 의한 프로비저닝 자동화가 진행됨에 따라 가격 면에서 압박을 받고 있습니다. 미국 보안 관련 매니지드 서비스 시장은 2031년까지 400억 달러를 넘어설 것으로 예측되지만, 데이터센터 서비스는 현재 수준에서 정체될 것으로 전망됩니다.
‘서비스형 랜섬웨어(RaaS)’로 인해 공격의 진입 장벽이 낮아지면서, 2024년 발생한 사고의 68%에서 백업 데이터가 삭제되었습니다. 이는 2022년의 42%에서 증가한 수치입니다. 연간 15만 달러의 비용으로 24시간 365일 운영되는 관리형 감지 서비스는 잠재적인 정보 유출로 인한 손실과 비교할 때 비용 효율적이기 때문에 중견 기업에서 도입이 확대되고 있습니다. 규정 준수를 촉진하는 요인, SEC(미국 증권거래위원회)의 공시 규정 등 규제 요건, 그리고 보험사의 감사가 보안 아웃소싱을 조직의 운영 예산에 확실히 반영하는 데 중요한 역할을 하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.14According to Mordor Intelligence, the United States managed services market size is projected to expand from USD 62.91 billion in 2025 and USD 71.14 billion in 2026 to USD 119.92 billion by 2031, registering a CAGR of 11.01% between 2026 to 2031.
This report is Segmented by Deployment (On-Premise, and Cloud), Service Type (Managed Data Center, Managed Security, Managed Communications, Managed Network, and More), Enterprise Size (Small and Medium Enterprises, and Large Enterprises), and End-User Vertical (IT and Telecom, Healthcare, Entertainment and Media, Retail, and More). The Market Forecasts are Provided in Terms of Value (USD).
United States Managed Services Market Trends and Insights
Growing Enterprise Shift Toward Hybrid-Cloud Management
U.S. enterprises run hybrid architectures that blend on-premise data centers, multiple public clouds, and edge locations, yet fewer than one-third possess in-house expertise to optimize costs and security. Configuration drift rises 40-60% in such estates, creating vulnerabilities that managed service providers (MSPs) monetize by offering unified policy enforcement and automated workload placement. Banks lead adoption because OCC guidance requires resilience testing across all critical third-party dependencies. MSPs that consolidate monitoring and failover orchestration, therefore, win multiyear contracts that bundle infrastructure with security services.
Surge in Multi-Cloud Complexity Driving Demand for Centralized MSPs
The average enterprise now operates 3.2 public cloud platforms, up from 2.1 in 2022. Fragmented identity and access management increase the attack surface; Verizon attributed 34% of 2024 cloud breaches to misconfigured permissions. Centralized MSPs deploy cloud security posture management tools that scan AWS, Azure, and Google Cloud for deviations from the Center for Internet Security Benchmarks. Retailers and healthcare providers feel pressure because customer-facing apps are shifting to the cloud while payment and EHR systems still reside on-premises. Outsourcing becomes rational when specialist salaries in each hyperscaler's proprietary stack top USD 180,000, well above SME budgets.
Skills Shortage Inflates U.S. MSP Labor Costs
CyberSeek recorded 450,000 unfilled cybersecurity roles in 2025. Median compensation for cloud security architects climbed 22% since 2023, compressing margins for labor-intensive service lines such as managed network operations. Providers must either invest in AI-Ops to improve engineer-to-device ratios or accept lower profitability. Large MSPs with proprietary automation gain cost advantages, while smaller firms face consolidation pressure.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Escalation of Cyber-Insurance Prerequisites
- SME Preference for OPEX-Based IT
- Rising Compliance Burden From SEC Cybersecurity Rules
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cloud-based services commanded 63.41% of the United States managed services market share in 2025 and are projected to grow at an 11.49% CAGR through 2031. Committed-use discounts from hyperscalers reduced multiyear cloud costs to parity with depreciated on-premises hardware, erasing capital-expenditure advantages. The United States managed services market for cloud deployments is therefore positioned to surpass USD 75 billion by 2031, while on-premises growth remains muted at single-digit rates. On-premises solutions persist in defense contracting, high-frequency trading, and medical imaging, yet even these verticals are adopting hybrid models, shifting latency-tolerant workloads to public cloud while retaining data-sovereignty-sensitive applications in local environments.
Performance differentials reinforce the cloud trend. Azure-based managed services detect ransomware on average 14 hours faster than on-premises equivalents. CFOs increasingly quantify the opportunity cost of delayed detection, concluding that migration savings outweigh sunk hardware costs. As threat telemetry pooled across thousands of tenants improves machine-learning models, the cloud advantage compounds, locking more enterprises into consumption-based contracts.
Managed security services are projected to grow at a 12.13% CAGR through 2031, outpacing the broader United States managed services market. Breach costs averaging USD 4.54 million motivate boards to treat continuous monitoring as business continuity rather than discretionary spend. Managed data center services held a 24.68% share in 2025 but face pricing pressure as hyperscalers automate provisioning. The United States managed services market for security offerings is forecast to eclipse USD 40 billion by 2031, while data center services are forecast to plateau near current levels.
Ransomware-as-a-service lowered barriers to attack, with 68% of incidents in 2024 deleting backups, up from 42% in 2022. A yearly fee of USD 150,000 for 24/7 managed detection compares favorably to potential breach losses, driving uptake among mid-market firms. Compliance catalysts, regulatory requirements such as SEC disclosure rules, and insurer audits are playing a significant role in firmly integrating security outsourcing into the operational budgets of organizations.
Complete Report Scope:
- By Deployment
- On-Premise
- Cloud
- By Service Type
- Managed Data Center
- Managed Security
- Managed Communications
- Managed Network
- Other Service Types
- By Enterprise Size
- Small and Medium Enterprises
- Large Enterprises
- By End-User Vertical
- Banking, financial services and insurance (BFSI)
- IT and Telecom
- Healthcare
- Entertainment and Media
- Retail
- Other End-User Verticals
List of Companies Covered in this Report:
- Accenture plc
- AT&T Inc.
- CDW Corporation
- Cisco Systems Inc.
- Cognizant Technology Solutions
- Dell Technologies Inc.
- Fujitsu Limited
- HCL Technologies Ltd.
- Hewlett Packard Enterprise Company
- IBM Corporation
- Infosys Ltd.
- Kyndryl Holdings Inc.
- Lumen Technologies Inc.
- Microsoft Corporation
- NTT DATA Services
- Rackspace Technology Inc.
- Tata Consultancy Services Ltd.
- Unisys Corporation
- Verizon Communications Inc.
- Wipro Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Enterprise Shift Toward Hybrid-Cloud Management
- 4.2.2 Surge in Multi-Cloud Complexity Driving Demand for Centralized MSPs
- 4.2.3 Rapid Escalation of Cyber-Insurance Prerequisites
- 4.2.4 SME Preference for OPEX-Based IT
- 4.2.5 Edge-Computing Rollouts in U.S. Manufacturing Hubs
- 4.2.6 AI-Ops Automation Boosting MSP Margins
- 4.3 Market Restraints
- 4.3.1 Skills Shortage Inflates U.S. MSP Labor Costs
- 4.3.2 Vendor Lock-In Fears Among Regulated Industries
- 4.3.3 Rising Compliance Burden From SEC Cybersecurity Rules
- 4.3.4 Data-Sovereignty Pushback on Offshore NOC Models
- 4.4 Industry Value Chain Analysis
- 4.5 Technological Outlook
- 4.6 Regulatory Landscape
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Deployment
- 5.1.1 On-Premise
- 5.1.2 Cloud
- 5.2 By Service Type
- 5.2.1 Managed Data Center
- 5.2.2 Managed Security
- 5.2.3 Managed Communications
- 5.2.4 Managed Network
- 5.2.5 Other Service Types
- 5.3 By Enterprise Size
- 5.3.1 Small and Medium Enterprises
- 5.3.2 Large Enterprises
- 5.4 By End-User Vertical
- 5.4.1 Banking, financial services and insurance (BFSI)
- 5.4.2 IT and Telecom
- 5.4.3 Healthcare
- 5.4.4 Entertainment and Media
- 5.4.5 Retail
- 5.4.6 Other End-User Verticals
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials As Available, Strategic Information, Market Rank/Share For Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Accenture plc
- 6.4.2 AT&T Inc.
- 6.4.3 CDW Corporation
- 6.4.4 Cisco Systems Inc.
- 6.4.5 Cognizant Technology Solutions
- 6.4.6 Dell Technologies Inc.
- 6.4.7 Fujitsu Limited
- 6.4.8 HCL Technologies Ltd.
- 6.4.9 Hewlett Packard Enterprise Company
- 6.4.10 IBM Corporation
- 6.4.11 Infosys Ltd.
- 6.4.12 Kyndryl Holdings Inc.
- 6.4.13 Lumen Technologies Inc.
- 6.4.14 Microsoft Corporation
- 6.4.15 NTT DATA Services
- 6.4.16 Rackspace Technology Inc.
- 6.4.17 Tata Consultancy Services Ltd.
- 6.4.18 Unisys Corporation
- 6.4.19 Verizon Communications Inc.
- 6.4.20 Wipro Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


