

|
시장보고서
상품코드
2124748
북미의 매니지드 서비스 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)North America Managed Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 북미의 매니지드 서비스 시장 규모는 2025년 735억 7,000만 달러에서 2026년에는 808억 9,000만 달러에 이르고, 2026-2031년 CAGR 9.96%로 성장을 지속하여 2031년에는 1,300억 6,000만 달러에 달할 것으로 예측됩니다.
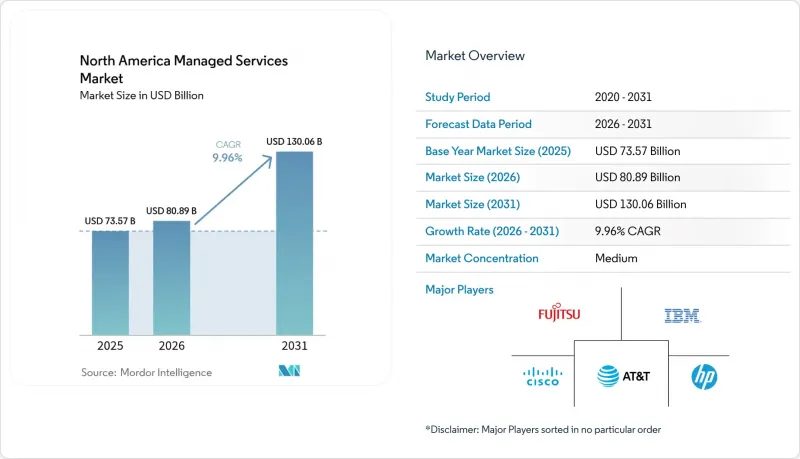
본 보고서는 도입 형태(On-Premise 등), 서비스 유형(매니지드 데이터센터, 매니지드 보안 등), 기업 규모(중소기업 및 대기업), 최종 사용자 업종(은행, 금융서비스 및 보험(BFSI), IT 및 통신, 헬스케어 및 생명과학 등), 그리고 국가별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
북미의 매니지드 서비스 시장 동향 및 인사이트
하이브리드 및 멀티 클라우드 아키텍처로의 전환을 추진하는 기업
현재, 이 지역 기업의 약 75%가 여러 퍼블릭 클라우드 및 On-Premise 인프라에 워크로드를 분산하고 있으며, 이로 인해 매니지드 오케스트레이션 및 거버넌스 서비스에 대한 수요가 증가하고 있습니다. 라이선스 비용을 인상하는 벤더의 가격 정책으로 인해 리패트리エ?ション 검토 및 하이브리드 도입 전략이 가속화되고 있습니다. 기업들은 락인을 억제하고 이식성을 단순화하기 위해 컨테이너 플랫폼의 표준화를 추진하고 있지만, 정책 적용, FinOps 최적화 및 워크로드 마이그레이션에는 여전히 외부 전문 지식이 필요합니다. 매니지드 서비스 제공업체들은 상황 파악, 마이그레이션 및 지속적인 비용 관리 서비스를 실현된 비용 절감액에 요금을 연동하는 성과 기반 계약에 포함시킴으로써 이러한 기회를 활용하기 시작했습니다. 이러한 요인들이 결합되어 북미의 매니지드 서비스 시장은 멀티 클라우드 환경에서 운영 우수성을 실현하기 위한 중요한 채널로 자리 잡고 있습니다.
심화되는 사이버 위협 상황이 매니지드 보안 도입을 촉진
현재 위협 행위자들은 인공지능(AI)을 활용하여 정찰을 자동화하고 다형성 멀웨어를 제작하고 있으며, 이로 인해 내부 보안 운영 센터는 대응에 쫓기고 있습니다. 미국 증권거래위원회(SEC)의 새로운 사고 보고 규정에 따라 상장 기업은 중대한 보안 침해 사고를 영업일 기준 4일 이내에 공개해야 할 의무가 있으며, 이에 따라 이사회는 연중무휴 24시간 감지 및 대응 체계를 요구하고 있습니다. 기업에는 위협 헌팅, 포렌식, 클라우드 네이티브 보안 대책에 대한 훈련을 받은 인력이 부족한 경우가 많기 때문에 관리형 감지·대응 서비스가 이러한 격차를 메우고 있습니다. 각 제공업체는 침입 후 체류 시간을 단축하고 엄격한 보고 기한을 충족하기 위해 AI 상관 분석 엔진에 대한 투자를 추진하고 있습니다. 사이버 보험 인수사가 제3자 모니터링을 도입하지 않은 조직에 더 높은 보험료를 부과하게 됨에 따라, 관리형 보안은 기술적 요건일 뿐만 아니라 재무적 리스크 헤지 역할도 수행하게 되었습니다.
데이터 주권과 레거시 시스템 통합의 복잡성
현재 미국 14개 주에서 거주지 및 데이터 처리에 관한 다양한 의무를 규정한 종합적인 개인정보 보호법을 시행하고 있으며, 이로 인해 국경을 넘는 데이터 아키텍처가 복잡해지고 구현 주기가 장기화되고 있습니다. 많은 대기업은 수십년전부터 사용해 온 독자적인 시스템을 여전히 보유하고 있어, 막대한 비용이 드는 리팩토링 없이는 퍼블릭 클라우드로 전환할 수 없습니다. 따라서 제공업체는 On-Premise 지원과 클라우드 네이티브 도구를 융합할 수밖에 없습니다. NIST SP 800-171과 같은 규정 준수 프레임워크나 의료·금융 분야의 산업별 규제는 세밀한 감사 추적을 요구하고 있어, 매니지드 서비스 제공업체의 운영 부담이 증가하고 있습니다. 이러한 요인으로 인해 프로젝트 시작이 지연되고, 경우에 따라서는 본래 북미의 매니지드 서비스 시장을 주도해야 할 수익 창출 가능성이 제한되고 있습니다.
부문 분석
2025년에는 클라우드 호스팅형 배포가 북미의 매니지드 서비스 시장 매출의 58.22%를 차지했지만, 하이브리드 환경은 2031년까지 연평균 성장률(CAGR) 11.03%를 나타낼 것으로 예측됩니다. 이러한 급증은 하이퍼스케일러의 견고성, 넉넉한 파트너 리베이트, 그리고 구독 조건을 간소화하는 마켓플레이스를 통한 조달을 반영합니다. 엄격한 데이터 상주 요건과 엣지 컴퓨팅의 지연 시간 목표에 따라 특정 워크로드가 사용자와 가까운 곳에 배치됨에 따라 하이브리드 환경 도입이 탄력을 받고 있습니다. 제조업 기업들은 프라이빗 5G 네트워크를 활용하여 공장 간을 연결하고, MSP가 관리하는 지역 클라우드에 데이터 분석 기능을 정착시키고 있습니다. 그 결과, 공급업체들은 단순한 ‘리프트 앤 시프트(lift-and-shift)’ 작업에서 벗어나, 다양한 인프라 전반에 걸쳐 비용, 성능, 규정 준수의 균형을 맞추는 지속적인 최적화 업무로 전환하고 있습니다. 북미의 매니지드 서비스 시장에서는 분산형 클러스터를 위한 자동 패치 적용 및 정책 적용을 실현하는 컨테이너 관리 애드온이 빈번하게 통합되고 있습니다. 서비스 카탈로그에는 현재 차지백 및 거버넌스 지표를 시각화하는 FinOps 대시보드가 포함되어 있어, 비용 관리에 대한 MSP의 관여가 더욱 공고해지고 있습니다.
매니지드 보안은 2025년 매출의 24.05%를 차지하고 있으며, 이는 AI를 악용한 공격에 대한 방어 강화의 중요성이 이사회 차원에서 인식되고 있음을 시사합니다. 매니지드 클라우드 및 용도 서비스는 10.61%라는 가장 높은 예측 연평균 성장률(CAGR)을 기록하고 있으며, 이는 맞춤형 개발을 서버리스나 컨테이너 환경으로 전환하면서도 여전히 외부 모니터링이 필요한 기업들에 의해 주도되고 있습니다. On-Premise 운영이 필수로 요구되는 규제 대상 워크로드의 경우, 기존 데이터센터 서비스가 여전히 중요하지만, 공급업체들은 수익성 향상을 위해 여기에 자동화 및 원격 관리 계층을 통합하는 경향이 강해지고 있습니다. 통합 커뮤니케이션, SD-WAN, 매니지드 네트워크는 2025년에도 지속될 하이브리드 근무 방식을 뒷받침하고 있습니다. 각 카테고리에서 AI 기반 오케스트레이션 엔진이 수작업 부담을 줄여주므로, 엔지니어는 더 높은 청구 단가를 창출하는 컨설팅 업무에 집중할 수 있게 됩니다. 이러한 전환을 통해 북미의 매니지드 서비스 시장 전체에서 가격 경쟁이 치열해지는 상황에서도 수익성을 유지할 수 있게 됩니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.14According to Mordor Intelligence, the North America managed services market size is expected to grow from USD 73.57 billion in 2025 to USD 80.89 billion in 2026 and is forecast to reach USD 130.06 billion by 2031 at 9.96% CAGR over 2026-2031.
This report is Segmented by Deployment (On-Premises, and More), Service Type (Managed Data Centre, Managed Security, and More), Enterprise Size (Small and Medium Enterprises and Large Enterprises), End-User Vertical (BFSI, IT and Telecom, Healthcare and Life Sciences, and More), and Country. The Market Forecasts are Provided in Terms of Value (USD).
North America Managed Services Market Trends and Insights
Enterprises Shifting to Hybrid and Multi-Cloud Architectures
Roughly 75% of regional organizations now distribute workloads across multiple public clouds and on-premises infrastructure, which intensifies demand for managed orchestration and governance services. Vendor pricing actions that raise licensing costs are accelerating repatriation assessments and hybrid adoption strategies. Enterprises are standardizing on container platforms to limit lock-in and simplify portability, yet they still require outside expertise for policy enforcement, FinOps optimization, and workload migration. Managed service providers are capitalizing by bundling discovery, migration, and ongoing cost-control services into outcome-based contracts that tie fees to savings delivered. These factors collectively sustain the North America managed services market as a critical channel for multicloud operational excellence.
Rising Cyber-Threat Landscape Driving Managed Security Adoption
Threat actors now deploy artificial intelligence to automate reconnaissance and build polymorphic malware, which overwhelms internal security operations centers. New U.S. Securities and Exchange Commission incident-reporting rules obligate public companies to disclose material breaches within four business days, pushing boards to demand 24 X 7 detection and response coverage. Managed detection and response services fill the gap because enterprises often lack staff trained in threat hunting, forensics, and cloud-native security controls. Providers are investing in AI correlation engines that shrink dwell time and meet the stringent reporting windows. As cyber insurance underwriters impose higher premiums for organizations without third-party monitoring, managed security becomes both a technical requirement and a financial hedge.
Data-Sovereignty and Legacy-Integration Complexity
Fourteen U.S. states now enforce comprehensive privacy statutes with varied residency and processing obligations, which complicates cross-border data architectures and lengthens implementation cycles. Many large enterprises retain decades-old proprietary systems that cannot move to public clouds without costly refactoring, forcing providers to blend on-premises support with cloud-native tooling. Compliance frameworks such as NIST SP 800-171 and sector-specific mandates in healthcare or finance require granular audit trails, adding overhead for managed service providers. These factors slow project kickoffs and in certain cases limit the revenue capture potential that otherwise fuels the North America managed services market.
Other drivers and restraints analyzed in the detailed report include:
- IT Talent Shortages and Need for Cost Optimization
- Accelerated Digital Transformation in SMEs
- Vendor Lock-in and Perceived Loss of Control
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cloud-hosted deployments generated 58.22% of North America managed services market revenue in 2025, while hybrid environments are forecast for an 11.03% CAGR through 2031. The surge reflects hyperscaler resilience, generous partner rebates, and marketplace procurement that simplify subscription terms. Hybrid adoption gains momentum as strict data-residency rules and edge-compute latency targets push certain workloads closer to users. Industrial firms use private 5G networks to link factories, then anchor data analytics in regional clouds managed by MSPs. As a result, providers rebound from purely lift-and-shift work to ongoing optimization engagements that balance cost, performance, and compliance across diverse infrastructures. The North America managed services market frequently embeds container management add-ons that deliver automated patching and policy enforcement for distributed clusters. Service catalogs now include FinOps dashboards that visualize chargeback and governance metrics, further cementing MSP involvement in cost stewardship.
Managed security accounted for 24.05% of 2025 revenue, underscoring board-level urgency to harden defenses against AI-driven attacks. Managed cloud and application services claim the fastest forecast CAGR at 10.61%, propelled by enterprises that shift custom development into serverless and container environments yet still require external oversight. Legacy data-center services remain relevant for regulated workloads that must stay on-premises, but providers increasingly wrap them in automation and remote-management layers to improve margin profile. Unified communications, SD-WAN, and managed networks support hybrid work patterns that persist in 2025. Across categories, AI-based orchestration engines reduce manual effort, freeing engineers to move into consulting roles that drive higher bill rates. This pivot helps sustain profitability even as price competition intensifies across the North America managed services market.
Complete Report Scope:
- By Deployment
- On-premises
- Cloud-hosted
- Hybrid
- By Service Type
- Managed Data Centre
- Managed Security
- Managed Communications (UCaaS)
- Managed Network (LAN/WAN, SD-WAN)
- Managed Infrastructure and Platform
- Managed Mobility and Workplace
- Managed Application and DevOps
- By Enterprise Size
- Small and Medium Enterprises
- Large Enterprises
- By End-user Vertical
- BFSI
- IT and Telecom
- Healthcare and Life Sciences
- Media and Entertainment
- Retail and E-commerce
- Manufacturing and Industrial
- Government and Public Sector
- Energy and Utilities
- Other End-user Verticals
- By Country
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- Accenture plc
- AT&T Inc.
- Capgemini SE
- CDW Corporation
- Cisco Systems, Inc.
- Citrix Systems, Inc.
- Cognizant Technology Solutions Corp.
- Dell Technologies Inc.
- DXC Technology Company
- Fujitsu Limited
- Hewlett Packard Enterprise Company
- International Business Machines Corporation
- Infosys Limited
- Kyndryl Holdings, Inc.
- Lumen Technologies, Inc.
- Microsoft Corporation
- NTT DATA Corporation
- Rackspace Technology, Inc.
- Softchoice Corporation
- Tata Consultancy Services Ltd.
- Verizon Communications Inc.
- Wipro Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Enterprises shifting to hybrid and multi-cloud architectures
- 4.2.2 Rising cyber-threat landscape driving managed security adoption
- 4.2.3 IT skill shortages and need for cost optimisation
- 4.2.4 Accelerated digital transformation in SMEs
- 4.2.5 State-level privacy laws spurring compliance-led outsourcing
- 4.2.6 Edge-compute managed services for 5G private networks and Industry 4.0
- 4.3 Market Restraints
- 4.3.1 Data-sovereignty and legacy-integration complexity
- 4.3.2 Vendor lock-in and perceived loss of control
- 4.3.3 Inflation-driven wage pressure eroding MSP margins
- 4.3.4 Sustainability-reporting costs for service providers
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
- 4.7 Impact of Macroeconomic Trends on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Deployment
- 5.1.1 On-premises
- 5.1.2 Cloud-hosted
- 5.1.3 Hybrid
- 5.2 By Service Type
- 5.2.1 Managed Data Centre
- 5.2.2 Managed Security
- 5.2.3 Managed Communications (UCaaS)
- 5.2.4 Managed Network (LAN/WAN, SD-WAN)
- 5.2.5 Managed Infrastructure and Platform
- 5.2.6 Managed Mobility and Workplace
- 5.2.7 Managed Application and DevOps
- 5.3 By Enterprise Size
- 5.3.1 Small and Medium Enterprises
- 5.3.2 Large Enterprises
- 5.4 By End-user Vertical
- 5.4.1 BFSI
- 5.4.2 IT and Telecom
- 5.4.3 Healthcare and Life Sciences
- 5.4.4 Media and Entertainment
- 5.4.5 Retail and E-commerce
- 5.4.6 Manufacturing and Industrial
- 5.4.7 Government and Public Sector
- 5.4.8 Energy and Utilities
- 5.4.9 Other End-user Verticals
- 5.5 By Country
- 5.5.1 United States
- 5.5.2 Canada
- 5.5.3 Mexico
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Accenture plc
- 6.4.2 AT&T Inc.
- 6.4.3 Capgemini SE
- 6.4.4 CDW Corporation
- 6.4.5 Cisco Systems, Inc.
- 6.4.6 Citrix Systems, Inc.
- 6.4.7 Cognizant Technology Solutions Corp.
- 6.4.8 Dell Technologies Inc.
- 6.4.9 DXC Technology Company
- 6.4.10 Fujitsu Limited
- 6.4.11 Hewlett Packard Enterprise Company
- 6.4.12 International Business Machines Corporation
- 6.4.13 Infosys Limited
- 6.4.14 Kyndryl Holdings, Inc.
- 6.4.15 Lumen Technologies, Inc.
- 6.4.16 Microsoft Corporation
- 6.4.17 NTT DATA Corporation
- 6.4.18 Rackspace Technology, Inc.
- 6.4.19 Softchoice Corporation
- 6.4.20 Tata Consultancy Services Ltd.
- 6.4.21 Verizon Communications Inc.
- 6.4.22 Wipro Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


