

|
시장보고서
상품코드
2124623
컨테이너 운송 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Container Shipping - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
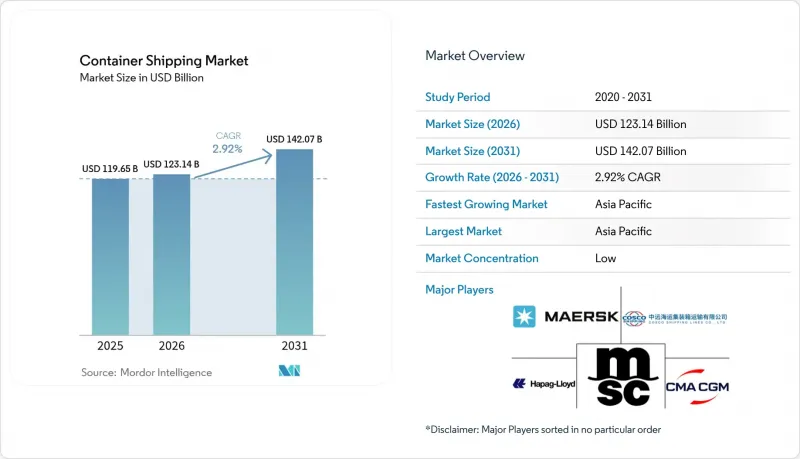
에 의하면, 컨테이너 운송 시장 규모는 2025년 1,196억 5,000만 달러로 평가되었습니다. 2026년에는 1,231억 4,000만 달러로 확대되어 2026년부터 2031년에 걸쳐 CAGR 2.92%로 성장을 지속하여, 2031년에는 1,420억 7,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 컨테이너 크기(20피트 TEU, 40피트 FEU, 기타), 컨테이너 유형(일반, 냉동), 서비스(전체 컨테이너 적재(FCL), 소량 혼재(LCL)), 최종 사용자 산업(FMCG·소매, 제조·자동차, 기타),및 지역(북미, 남미, 아시아태평양, 유럽, 중동 및 아프리카)별로 분류되어 있습니다. 시장 예측은 달러 기준 금액으로 제시되어 있습니다.
세계의 컨테이너 운송 시장 동향 및 인사이트
국제 무역량 증가
세계 상품 무역은 개인 소비의 안정화와 재고 보충 주기의 회복을 배경으로 회복되고 있으며, 이에 따라 해운사들은 유휴 선박을 북미 및 지중해의 관문으로 재배치하고 있습니다. 홍해를 우회함으로써 항로 거리가 연장되면서 일시적으로 잉여 선박 용량을 흡수하고 있으며, 신조선의 취항이 진행되는 상황에서도 운임 수준 유지에 기여하고 있습니다. 기항 데이터에 따르면, 미국 동부 해안의 허브 항구에서는 처리량이 두 자릿수 회복세를 보이고 있어, 컨테이너 운송 시장이 화물 흐름을 신속하게 재분배할 수 있는 유연성을 부각시키고 있습니다. 선박 재배치 비용은 증가하고 있지만, 귀항편의 이용률 향상으로 인해 그 부담의 일부는 상쇄되고 있습니다. 무역 성장의 지속성은 여전히 가계의 구매력과 지정학적 긴장이 얼마나 신속하게 정상화될지와 관련이 있습니다.
자유무역협정의 확대
2024년 12월에 체결된 EU-메르코수르 협정은 560억 유로(618억 달러) 규모의 추가 상품 무역을 창출하고, 남대서양 항로의 서비스 구조를 일신할 전망입니다. 이미 산토스와 부에노스아이레스의 터미널을 관리하고 있는 해운사들은 기존에 카리브해에서 환적이 이루어지던 출발지와 도착지 간의 화물량을 확보하기 위해 전용 루프 구축을 추진하고 있습니다. 동시에 USMCA(미국·멕시코·캐나다 협정)의 규정에 따라 북미의 니어쇼어링이 강화되고 있으며, 이러한 동향은 미국행 화물을 취급하는 멕시코 관문(게이트웨이)의 점유율 증가에서 확인할 수 있습니다. 지역화의 진전에 따라 선단 계획 담당자들은 장거리 동서 간선 노선에만 의존하지 않고, 더 짧은 거리와 높은 빈도의 항로를 설계하도록 권장받고 있습니다. 장기적으로 컨테이너 운송 시장은 관세 장벽의 완화뿐만 아니라, 체류 시간을 단축하고 서비스의 예측 가능성을 높이는 조화로운 통관 절차의 혜택을 받고 있습니다.
변동이 심한 선박용 연료 가격
2024년 초저유황 연료유의 평균 가격은 톤당 630달러였으나, EU 배출권 거래 제도(ETS)에 해운업이 임베디드됨에 따라 유럽 내 항로에서는 톤당 170-210달러의 추가 비용이 발생하고 있습니다. 가격의 급격한 등락으로 인해 해운사는 벙커 조정 계수를 통해 운임을 조정할 수밖에 없지만, 이러한 조정은 시장 변동에 뒤처지는 경향이 있어 이익률을 압박하고 있습니다. LNG, 메탄올 및 기존 벙커 연료 간의 가격 차이가 확대됨에 따라 다연료 조달 전략은 복잡해지고 있습니다. 헤지 거래는 일부 문제를 완화해 주지만, 모든 선사들이 갖추고 있는 것은 아닌 고도의 금융 지식이 요구됩니다. 그 결과, 컨테이너 운송 시장의 비용 충격을 흡수하기 위한 당면한 수단으로는 에너지 효율 향상을 위한 개조나 감속 항해가 여전히 유효합니다.
부문별 분석
40피트 컨테이너 부문은 2025년 매출의 50.62%를 차지하며, 선박의 적재량을 극대화하고 철도 및 트럭의 규격에도 부합하는 업계의 주력 유닛으로서의 위상을 반영했습니다. 40피트 컨테이너의 해상 운송 시장 규모는 설비 갱신 주기와 하이큐브형 컨테이너를 선호하는 내륙 인프라의 업그레이드에 따라 확대될 것으로 예측됩니다. 전자제품 및 의류 화주들의 견조한 수요가 선단의 가동률을 높이는 한편, 하이큐브형 컨테이너의 지속적인 생산으로 인해 단위당 적재율이 향상되고 있습니다. 항만 측의 더블 리프트 크레인 스프레더에 대한 투자 또한 이 크기에 대한 운영상의 선호도를 더욱 공고히 하고 있습니다. 20피트 컨테이너 부문은 고밀도 화물이나 개발도상국의 인프라가 제한적인 터미널에 여전히 필수적이지만, 화주들이 톤당 탄소 발자국을 줄이기 위해 화물을 통합함에 따라 그 상대적 점유율은 소폭 하락할 것으로 예측됩니다. 45피트 컨테이너와 같은 특수 크기는 팔레트 크기의 화물에 대한 틈새 수요를 충족시키고 있지만, 그 보급은 백홀 수요 부족과 특정 철도 회랑에서의 호환성 문제로 인해 제한되고 있습니다.
40피트 카테고리의 성장은 컨테이너 추적의 디지털화에 의해서도 뒷받침되고 있습니다. 이를 통해 문에서 문까지의 가시성이 향상되어, 대량 취급 소매업체에게 더 효율적인 재고 계획이 가능해집니다. 리스 회사는 스마트 박스 기술을 도입하기 위해 차량 갱신을 가속화하고 있으며, 이러한 움직임은 자산 회전율을 높이고 유휴 시간을 줄여줍니다. 이러한 요인들이 맞물려 2031년 내내 40피트 부문은 컨테이너 운송 시장의 중심을 유지할 것입니다.
2025년 취급량 중 범용 컨테이너가 63.40%를 차지하며, 소비자 및 산업용 무역 흐름의 대부분을 뒷받침했습니다. 그러나 온도 관리가 필요한 의약품 및 신선 식품에 대한 수요가 지속되고 있는 가운데, 냉동 컨테이너는 연평균 성장률(CAGR) 3.36%를 기록하며 표준 컨테이너를 상회하는 성장이 예상됩니다. 단열 성능 향상, 원격 측정 기능 통합, 전력 소비 감소로 인해 초기 투자 비용은 높지만, 냉장 서비스의 수익성은 향상되고 있습니다. 제약 기업들은 제품의 품질을 저해하지 않으면서 비용 절감을 실현할 수 있는 검증된 콜드체인 통로에 매력을 느끼며, 고부가가치 바이오 의약품을 항공 운송에서 해상 운송으로 전환하고 있습니다. 식품 공급망에서는 폐기물 감축을 위한 노력으로 인해 지속적인 모니터링 기능을 갖춘 고정밀 냉장 컨테이너로 운송되는 신선 식품의 비율이 증가하고 있습니다. 그 결과, 해운사들은 신조선 설계에 더 대형의 냉장용 전원 연결구를 설치하고 있으며, 이는 지속적인 프리미엄 수요에 대한 확신을 보여줍니다. 범용 컨테이너 부문은 성숙기에 접어들었으나 여전히 컨테이너 운송 시장의 중심적인 위치를 차지하고 있으며, 혁신은 획기적인 설계 변경이라기보다는 도난 방지 잠금 장치나 종단 간 추적 기능에 중점을 두고 있습니다.
이와 병행하여 CO₂ 기반 냉동 시스템의 사후 개조가 진행되고 있으며, 구형 HFC 장치에 비해 에너지 효율이 향상되고 지구온난화지수(GWP)가 감소하고 있습니다. 이러한 기술적 업그레이드는 식품 및 의약품 분야의 규제 요인과 맞물려, 냉동 컨테이너가 수익 성장의 최전선에 계속 머물게할 것으로 전망됩니다.
지역별 분석
아시아태평양은 2025년 매출의 40.55%를 차지하며, 컨테이너 운송 시장의 제조 및 수출 원동력으로서의 위상을 강화했습니다. 5%에 육박하는 중국의 GDP 성장률과 상하이, 닝보·저우산, 부산에서 가속화되고 있는 항만 자동화가 이 지역의 슬롯 수요를 뒷받침하고 있습니다. 아세안(ASEAN)공급망 통합과 전자 부품 유통에 힘입어 아시아 지역 내 무역 항로에서는 운항 빈도 증가율이 가장 높은 수준을 기록하고 있습니다. 아시아-유럽 간 화물 운송에서 여름철 대체 경로로 북극해 항로가 등장하면서 회복력이 더욱 강화되었으나, 빙해용 선박의 부족과 지정학적 리스크로 인해 그 이용은 여전히 제한되고 있습니다. 내륙 철도망과 자유무역지대에 대한 지속적인 투자가 견조한 전망을 뒷받침하고 있으며, 이 지역은 2031년까지 연평균 성장률(CAGR) 4.12%를 달성할 것으로 예측됩니다.
북미에서는 소매 업계의 재고 보충 및 전자상거래 주문 처리 수요에 힘입어 2024년 컨테이너 수입량이 13.1% 회복되었습니다. 사바나, 뉴욕·뉴저지 등 동부 해안의 관문은 서부 해안의 노동력 상황 불확실성을 피하려는 화주들의 분산화와, 더 큰 규모의 네오파나막스 선박을 수용하기 위해 수로 준설이 심화된 데 따른 혜택을 받았습니다. 멕시코 서해안의 라살로 칼데나스 항은 아시아발 직항 노선을 유치하고 있으며, 미국 중서부로의 철도 연결을 제공합니다. 롱비치 터미널에서는 제로 배출 야드 장비를 중시하는 개보수 공사가 진행되고 있으며, 이는 주 규정을 준수함과 동시에 해당 지역의 컨테이너 운송 시장의 환경 보호 노력을 강화하고 있습니다. 노사 교섭 가능성이 단기적인 변동 요인이 되는 반면, 육상 재고 완충 장치와 니어쇼어링으로의 구조적 추세가 중기적인 성장을 뒷받침하고 있습니다.
유럽의 상황은 제각각입니다. 로테르담이나 앤트워프·브뤼헤와 같은 북부 허브 항구는 2023년의 침체를 겪은 후 소폭 증가를 기록한 반면, 지중해의 환적 허브 항구에서는 해운사들이 수에즈 운하를 우회함에 따라 처리량이 약 30% 급증했습니다. 그 결과, FuelEU Maritime 및 ETS 체계 하에서 규제 비용이 상승했음에도 불구하고 남유럽의 컨테이너 운송 시장 규모는 확대되었습니다. 항만 커뮤니티 시스템 및 복합운송 철도 회랑에 대한 투자로 내륙 지역과의 연결성은 개선되고 있지만, 위기 시 우회 경로에서 지중해 지역의 허브가 과잉 물량을 수용하게 될 경우 혼잡의 위험은 여전히 남아 있습니다. 브렉시트와 관련된 통관 마찰은 진정되는 양상을 보이고 있지만, 영국의 관문에서는 2021년 이전에 비해 극동 지역에서 오는 직항편 처리량이 여전히 낮은 수준을 유지하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측(금액, 10억 달러)
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the container shipping market size is expected to grow from USD 119.65 billion in 2025 to USD 123.14 billion in 2026 and is forecast to reach USD 142.07 billion by 2031 at 2.92% CAGR over 2026-2031.
This report is Segmented by Container Size (20-Foot TEU, 40-Foot FEU, Others), Container Type (General, Reefer), Service (Full-Container-Load FCL, Less-Than-Container-Load LCL), End-User Industry (FMCG & Retail, Manufacturing and Automotive, and More), and Geography (North America, South America, Asia-Pacific, Europe, Middle East and Africa). The Market Forecasts are Provided in Terms of Value USD.
Global Container Shipping Market Trends and Insights
Rising Volume of International Trade
World merchandise trade is recovering on the back of stabilizing consumer spending and restocking cycles, prompting carriers to redeploy idle capacity onto North American and Mediterranean gateways. Longer voyage distances caused by Red Sea detours have temporarily absorbed excess tonnage, protecting rate integrity even as new vessels deliver. Port call data show double-digit throughput rebounds at U.S. East Coast hubs, highlighting the flexibility of the container shipping market to redirect flows quickly. Equipment repositioning costs have increased, yet higher backhaul utilization is offsetting part of the burden. The durability of trade growth remains linked to household purchasing power and to how swiftly geopolitical flashpoints normalize.
Expansion of Free-Trade Agreements
The EU-Mercosur deal, concluded in December 2024, is set to unlock EUR 56 billion (USD 61.80 billion) in additional goods trade and reshape South Atlantic services. Carriers that already control terminals in Santos and Buenos Aires are preparing dedicated loops to capture origin-destination volumes that were traditionally transshipped in the Caribbean. Simultaneously, USMCA provisions are reinforcing North American near-shoring, a trend visible in the rising share of Mexican gateways handling U.S.-bound cargo. Broader regionalization is nudging fleet planners to design shorter, high-frequency strings instead of relying solely on long-haul east-west trunk routes. Over the long term, the container shipping market benefits from lower tariff barriers as well as harmonized customs processes that reduce dwell times and enhance service predictability.
Volatile Bunker Fuel Prices
Very-Low-Sulfur Fuel Oil averaged USD 630 / t in 2024, and the inclusion of shipping in the EU Emissions Trading System has added USD 170-210 / t for intra-European voyages. Price gyrations compel carriers to adjust freight rates through bunker adjustment factors that often lag market swings, eroding margins. Wide spreads between LNG, methanol, and conventional bunkers complicate multi-fuel procurement strategies. Hedging offers partial relief but demands financial sophistication that not all operators possess. Consequently, energy efficiency retrofits and slow steaming remain immediate tools to absorb cost shocks within the container shipping market.
Other drivers and restraints analyzed in the detailed report include:
- Rapid E-commerce Containerization
- IMO 2023 Carbon Regulations Drive Fleet Renewal
- Escalating Geopolitical Trade Tensions
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The 40-foot segment held 50.62% of 2025 revenue, reflecting its status as the industry's workhorse unit that maximizes vessel stowage and aligns with rail and truck dimensions. The container shipping market size for 40-foot boxes is projected to grow alongside equipment replacement cycles and inland infrastructure upgrades that favor high-cube variants. Robust demand from electronics and apparel shippers reinforces fleet utilization, while sustained production of high-cube designs lifts per-unit load factors. Port-side investments in double-lift crane spreaders further cement the operational preference for this size. The 20-foot segment remains vital for dense commodities and infrastructure-limited terminals in developing economies, though its relative share is expected to edge lower as shippers consolidate loads to reduce per-tonne carbon footprints. Specialized sizes such as 45-foot units cater to pallet-wide cargo niches, yet their uptake is restricted by limited backhaul demand and compatibility gaps in certain rail corridors.
Growth in the 40-foot category is also supported by digitized container tracking, which improves door-to-door visibility and enables leaner inventory planning for high-volume retailers. Leasing companies are accelerating fleet renewal to incorporate smart-box technology, a move that enhances asset rotation and reduces idle time. Combined, these factors should keep the 40-foot segment at the core of the container shipping market through 2031.
General-purpose containers accounted for 63.40% of 2025 throughput, underpinning the bulk of consumer and industrial trade flows. However, reefer units are forecast to log a 3.36% CAGR, outpacing standard boxes on the back of sustained demand for temperature-controlled pharmaceuticals and perishables. Enhanced insulation, integrated telemetry, and lower power draw raise the profitability of refrigerated services despite higher capital costs. Pharmaceutical firms are shifting high-value biologics from air to ocean freight, lured by validated cold-chain corridors that deliver cost savings without compromising product integrity. In food supply chains, the push to cut waste is increasing the share of fresh produce shipped in high-accuracy reefers with continuous monitoring. Consequently, carriers are dedicating larger reefer plugs on newbuild designs, signaling confidence in sustained premium demand. The general-purpose segment, while mature, remains central to the container shipping market, with incremental innovation focused on theft-resistant locks and end-to-end tracking rather than on transformative design changes.
A parallel trend involves the retro-fitting of CO2-based refrigeration systems, improving energy efficiency and reducing global warming potential relative to older HFC units. These technology upgrades, combined with regulatory drivers in food and pharma, are likely to keep reefers at the forefront of revenue growth.
Complete Report Scope:
- By Container Size
- 20-Foot (TEU)
- 40-Foot (FEU)
- Others
- By Container Type
- General
- Reefer
- By Service
- Full-Container-Load (FCL)
- Less-Than-Container-Load (LCL)
- By End-User Industry
- FMCG and Retail
- Manufacturing and Automotive
- Healthcare and Pharmaceuticals
- Electronics and Electrical Equipment
- Industrial Chemicals and Raw Materials
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Peru
- Chile
- Argentina
- Rest of South America
- Asia-Pacific
- India
- China
- Japan
- Australia
- South Korea
- South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- Rest of Asia-Pacific
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- BENELUX (Belgium, Netherlands, and Luxembourg)
- NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- Rest of Europe
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Nigeria
- Rest of Middle East And Africa
- North America
Geography Analysis
Asia-Pacific commanded 40.55% of 2025 revenue, reinforcing its status as the manufacturing and export engine of the container shipping market. Chinese GDP expansion near 5% and accelerated port automation in Shanghai, Ningbo-Zhoushan, and Busan are sustaining the region's slot demand. Intra-Asian trade lanes are registering some of the highest frequency growth, propelled by ASEAN supply-chain integration and electronics component flows. The emergence of the Northern Sea Route as a summer alternative for Asia-Europe cargo offers an additional resilience layer, though uptake remains constrained by ice-class fleet scarcity and geopolitical risk. Continued investment in hinterland rail networks and free-trade zones supports a robust outlook, with the region projected to deliver a 4.12% CAGR through 2031.
North America experienced a 13.1% rebound in loaded container imports during 2024, led by retail restocking and e-commerce fulfillment demand. East Coast gateways such as Savannah and New York-New Jersey benefited from shipper diversification away from West Coast labor uncertainties and from deeper channel dredging that accommodates larger neo-Panamax vessels. Mexico's west-coast port of Lazaro Cardenas is attracting direct Asia services, offering rail connectivity into the U.S. Midwest. Long-beach terminal retrofits emphasizing zero-emission yard equipment align with state regulations and bolster the environmental credentials of the container shipping market in the region. While potential labor negotiations pose near-term volatility, the structural trend toward onshore inventory buffers and near-shoring supports medium-term growth.
Europe's picture is mixed. Northern hubs such as Rotterdam and Antwerp-Bruges posted modest gains after a soft 2023, whereas Mediterranean transshipment hubs enjoyed volume windfalls of about 30% as carriers bypassed the Suez Canal. The container shipping market size in Southern Europe therefore expanded even as regulatory costs rose under the FuelEU Maritime and ETS frameworks. Investments in port community systems and intermodal rail corridors are improving hinterland connectivity, yet congestion risk lingers when Mediterranean hubs become overflow valves during crisis reroutes. Brexit-related customs friction has stabilized, although UK gateways continue to handle lower direct Far East services than before 2021.
- MSC Mediterranean Shipping Company
- A.P. Moller - Maersk
- CMA CGM
- COSCO Shipping Lines
- Hapag-Lloyd
- ONE (Ocean Network Express)
- Evergreen Marine
- Yang Ming
- HMM Co.
- PIL (Pacific International Lines)
- ZIM Integrated Shipping
- OOCL
- Wan Hai Lines
- Matson
- X-Press Feeders
- SITC International
- Zhonggu Logistics
- Antong Holdings
- Hyundai Merchant Marine
- IRISL Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising volume of international trade
- 4.2.2 Expansion of free-trade agreements
- 4.2.3 Rapid e-commerce containerization
- 4.2.4 IMO 2023 carbon regulations drive fleet renewal
- 4.2.5 Arctic route viability (Northern Sea Route)
- 4.2.6 AI-enabled predictive routing and scheduling
- 4.3 Market Restraints
- 4.3.1 Volatile bunker fuel prices
- 4.3.2 Escalating geopolitical trade tensions
- 4.3.3 Chronic port-side congestion bottlenecks
- 4.3.4 Cyber-attacks on digital ship-to-shore systems
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Pricing Analysis
5 Market Size and Growth Forecasts (Value, USD Bn)
- 5.1 By Container Size
- 5.1.1 20-Foot (TEU)
- 5.1.2 40-Foot (FEU)
- 5.1.3 Others
- 5.2 By Container Type
- 5.2.1 General
- 5.2.2 Reefer
- 5.3 By Service
- 5.3.1 Full-Container-Load (FCL)
- 5.3.2 Less-Than-Container-Load (LCL)
- 5.4 By End-User Industry
- 5.4.1 FMCG and Retail
- 5.4.2 Manufacturing and Automotive
- 5.4.3 Healthcare and Pharmaceuticals
- 5.4.4 Electronics and Electrical Equipment
- 5.4.5 Industrial Chemicals and Raw Materials
- 5.4.6 Others
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Peru
- 5.5.2.3 Chile
- 5.5.2.4 Argentina
- 5.5.2.5 Rest of South America
- 5.5.3 Asia-Pacific
- 5.5.3.1 India
- 5.5.3.2 China
- 5.5.3.3 Japan
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- 5.5.3.7 Rest of Asia-Pacific
- 5.5.4 Europe
- 5.5.4.1 United Kingdom
- 5.5.4.2 Germany
- 5.5.4.3 France
- 5.5.4.4 Spain
- 5.5.4.5 Italy
- 5.5.4.6 BENELUX (Belgium, Netherlands, and Luxembourg)
- 5.5.4.7 NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- 5.5.4.8 Rest of Europe
- 5.5.5 Middle East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 South Africa
- 5.5.5.4 Nigeria
- 5.5.5.5 Rest of Middle East And Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 MSC Mediterranean Shipping Company
- 6.4.2 A.P. Moller - Maersk
- 6.4.3 CMA CGM
- 6.4.4 COSCO Shipping Lines
- 6.4.5 Hapag-Lloyd
- 6.4.6 ONE (Ocean Network Express)
- 6.4.7 Evergreen Marine
- 6.4.8 Yang Ming
- 6.4.9 HMM Co.
- 6.4.10 PIL (Pacific International Lines)
- 6.4.11 ZIM Integrated Shipping
- 6.4.12 OOCL
- 6.4.13 Wan Hai Lines
- 6.4.14 Matson
- 6.4.15 X-Press Feeders
- 6.4.16 SITC International
- 6.4.17 Zhonggu Logistics
- 6.4.18 Antong Holdings
- 6.4.19 Hyundai Merchant Marine
- 6.4.20 IRISL Group
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


