

|
시장보고서
상품코드
2124788
북미의 단열 운송 컨테이너 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)North America Insulated Shipping Containers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
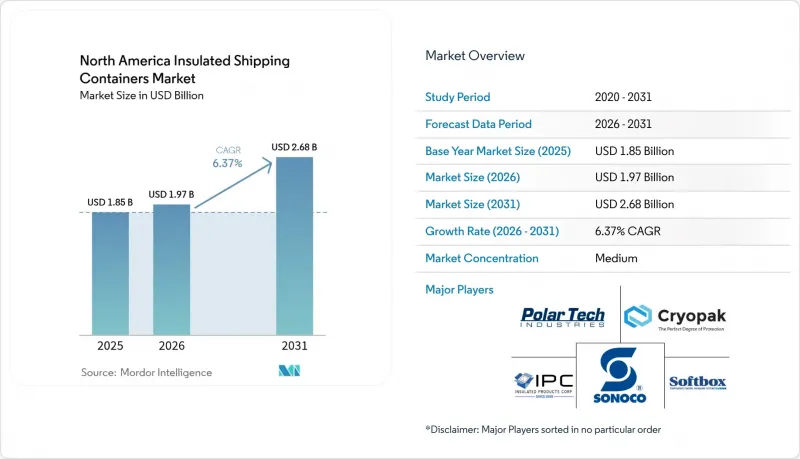
에 의하면, 2026년 북미의 단열 운송 컨테이너 시장 규모는 19억 7,000만 달러로 추정되고 2025년 18억 5,000만 달러에서 확대해, 2031년에는 26억 8,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 동안 연평균 성장률(CAGR) 6.37%로 성장할 것으로 전망됩니다.
본 보고서는 소재 유형(발포 폴리스티렌, 폴리우레탄 폼, 발포 폴리프로필렌, 기타), 최종 용도(생명과학·제약, 신선 식품, 기타), 제품 유형(일회용 경질 박스, 재사용형 경질 박스, 기타), 용량 범위(5L 이하, 5-20L, 기타), 국가별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
북미의 단열 운송 컨테이너 시장 동향 및 인사이트
온도에 민감한 밀키트 분야의 전자상거래 급증
온도에 민감한 밀키트 서비스가 급속히 확대됨에 따라, 48-72시간의 운송 기간을 견딜 수 있는 콤팩트하고 고성능의 포장이 요구되고 있습니다. SeaWell의 액티브 포장 등의 기술은 유통기한을 연장하고 품질 관련 주장을 뒷받침하는 역할을 하고 있습니다. 비용에 민감한 사업자들은 운송비를 절감할 수 있는 소형 경량 컨테이너를 채택하고 있으며, 생분해성 발포재는 브랜드가 지속가능성 노력을 어필하는 데 도움이 되고 있습니다. 산업 재편으로 사업자 수가 감소하는 가운데, 도입은 2년 이내에 정점을 맞이하겠지만 소형 컨테이너의 도입 대수는 계속해서 증가하고 있습니다. 북미의 단열 운송 컨테이너 시장은 라스트 마일의 온도 관리 목표를 여전히 충족시키면서, 벽 두께를 얇게 한 제품으로 이에 대응하고 있습니다.
의약품 콜드체인 확대에 따른 성장
생물학적 제제, 세포 치료, 맞춤형 의료 분야에서는 2-8°C에서의 정밀한 운송이 요구되며, 그 수요는 일반적인 백신 운송 경로를 넘어 확대되고 있습니다. 머크(Merck)사가 2024년에 시행한 15억 달러 규모의 콜드체인 확충 계획은 장기적인 자본 투자의 중요성을 부각시켰습니다. 진공 단열 패널(VIP) 및 상변화 물질(PCM)은 장시간 운송 중 화물을 보호하고 온도 이탈 위험을 줄여줍니다. 환자에게 직접 배송하는 사례가 늘어남에 따라, 데이터 로깅 기능을 갖춘 소형 검증 완료 운송 용기에 대한 수요가 증가하고 있습니다. 유통 네트워크가 성숙해짐에 따라, 북미의 단열 운송 컨테이너 시장에서는 국경 간 감사 요건을 충족하기 위해 실시간 모니터링 기능이 통합되고 있습니다.
바이오 유래 단열 수지의 비용 급등
바이오 유래 수지는 석유 유래 동종 제품에 비해 15-25% 비싸며, 친환경 가공 업체의 이익률을 압박하고 있습니다. 원료 공급 능력의 한계와 농산물 가격 변동이 가격 변동성을 더욱 확대시키고 있습니다. 소규모 공급업체들은 추가 비용을 흡수하는 데 어려움을 겪고 있어, 이를 고객에게 전가할 수밖에 없으며, 주문 지연 위험에 직면해 있습니다. 기술 학습 곡선과 규모의 경제에 따라 이러한 격차는 줄어들 가능성이 있지만, 단기적으로는 여전히 역풍이 지속될 전망이며, EPS에서 전면적인 전환은 더뎌질 것으로 예측됩니다.
부문별 분석
발포 폴리스티렌(EPS)은 식품 및 의약품 등 광범위한 이용 사례에서 1달러당 단열 성능이 여전히 타 소재를 압도하고 있어, 2025년 북미의 단열 운송 용기 시장에서 43.35%의 점유율을 차지했습니다. 폴리우레탄 폼은 밀도 조절이 가능하기 때문에 고부가가치의 바이오 의약품 운송에 채택되고 있으며, EPP는 더 높은 낙하 저항성이 요구되는 재사용 프로그램에서 지지를 얻고 있습니다. 생분해성 전분 혼합 폼은 기반 규모는 작지만, 규제상의 인센티브와 브랜드의 사회적 책임 활동에 힘입어 연평균 성장률(CAGR) 6.74%로 성장하고 있습니다. VIP 및 에어로겔 기술은 높은 비용 구조를 정당화할 수 있는 고급 화물에 대응하며, 북미의 단열 운송 컨테이너 시장의 총 가치 풀을 뒷받침하고 있습니다.
FDA의 검증 프로토콜과 EPA의 재활용 지침을 배경으로 단열 성능 기준이 더욱 엄격해지고 있습니다. Sealed Air와 같은 공급업체들은 온도 유지 시간을 유지하면서 포장 면적을 30% 줄여주는 얇은 VIP 패널을 제공합니다. EPS 공급업체들은 각 주의 플라스틱 관련 법규를 준수하기 위해 재생 소재를 배합한 제품의 시범 도입을 추진하고 있습니다. 그 결과, 구매자가 취득 비용과 역물류 비용 절감 효과, 폐기 비용, 고객의 지속가능성에 대한 기대를 저울질하는 점점 더 세분화된 소재 선택 매트릭스가 형성되고 있습니다.
2025년, 생명과학 및 제약 산업은 북미의 단열 운송 컨테이너 시장 점유율의 37.45%를 차지했으며, 일반적으로 2-8°C의 운송 경로에서 검증된, 누출 방지 기능과 데이터 통신 기능을 갖춘 컨테이너를 지정하고 있습니다. 규제 준수 부담은 판매 주기를 장기화시키지만, 한편으로는 프리미엄 가격대 유지와 예측 가능한 재주문 주기를 뒷받침하고 있습니다. 소비자 직배송형 단백질 서비스는 생고기 및 수산물 배송을 주도하며 연평균 성장률(CAGR) 6.79%로 성장하고 있습니다. 또한, 익일 배송 일정을 충족하기 위해서는 냉각제의 무게와 상자 벽 두께의 균형이 잘 잡힌 컨테이너가 요구됩니다.
밀키트 사업자들은 젤 팩이 장착된 중용량 EPS 상자에 대한 수요를 유지하고 있는 반면, 냉동 식품 부문에서는 안구건조증스를 적재할 수 있는 경질 상자에 대한 수요가 견조하게 유지되고 있습니다. 화훼 물류와 같은 특수한 틈새 시장에서는 시들음 위험을 줄이기 위해 습도에 강한 라이너가 필수적입니다. 의약품 부문이 시장을 주도하고 있는 것은 비용 허용도가 높고 엄격한 검증이 요구되기 때문이지만, 한편으로는 다양한 식품 부문의 확대로 인해 북미의 단열 운송 컨테이너 시장의 총 잠재 시장 규모는 확대되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, North America insulated shipping containers market size in 2026 is estimated at USD 1.97 billion, growing from 2025 value of USD 1.85 billion with 2031 projections showing USD 2.68 billion, growing at 6.37% CAGR over 2026-2031.
This report is Segmented by Material Type (Expanded Polystyrene, Polyurethane Foam, Expanded Polypropylene, and More), End-User Application (Life Sciences and Pharmaceutical, Fresh Produce, and More), Product Type (Single-Use Rigid Box, Reusable Rigid Box, and More), Capacity Range (<=5L, 5-20L, and More), and Country. The Market Forecasts are Provided in Terms of Value (USD).
North America Insulated Shipping Containers Market Trends and Insights
E-commerce Surge in Temperature-Sensitive Meal Kits
Temperature-sensitive meal kit services are scaling quickly and require compact, high-performance packaging that sustains 48-72-hour transit windows. Technology such as SeaWell active packaging lengthens shelf life and supports quality claims. Cost-conscious operators use smaller, lighter containers that cut freight expenses, and biodegradable foams help brands communicate sustainability commitments. Adoption peaks within two years as consolidation reduces operator count, yet installed volumes of small containers keep rising. The North America insulated shipping containers market responds with thinner wall profiles that still meet last-mile thermal targets.
Growth in Pharmaceutical Cold-Chain Expansion
Biologics, cell therapies, and personalized medicine demand precise 2-8 °C shipping, expanding beyond routine vaccine lanes. Merck's USD 1.5 billion cold-chain build-out in 2024 underscores the long-term capital push. Vacuum insulated panels (VIPs) and phase change materials (PCMs) safeguard payloads during extended transit and reduce excursion risk. Direct-to-patient delivery fuels the need for small, validated shippers with data-logging features. As distribution networks mature, the North America insulated shipping containers market embeds real-time monitoring to satisfy audit requirements across borders.
Escalating Cost of Bio-Based Insulation Resins
Bio-based resins cost 15-25% more than petroleum equivalents, eroding margins for eco-focused converters. Limited feedstock capacity and agricultural price swings magnify volatility. Smaller vendors struggle to absorb surcharges and must pass them to customers, risking order deferrals. Technology learning curves and scale economies could narrow the gap, yet near-term headwinds remain, slowing the wholesale shift away from EPS.
Other drivers and restraints analyzed in the detailed report include:
- Tightening U.S. FDA Biologics Stability Guidance
- Retailer Sustainability Mandates for Reusable Shippers
- Limited Reverse-Logistics Infrastructure for Returns
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Expanded polystyrene holds a 43.35% share within the North America insulated shipping containers market size in 2025 because its insulation value per dollar remains unmatched for broad food and pharma use cases. Polyurethane foam secures high-value biologics shipping through its density tunability, and EPP gains favor in reuse programs that demand higher drop resistance. Biodegradable starch-blend foams, though at a modest base, rise at a 6.74% CAGR thanks to regulatory incentives and brand stewardship. VIP and aerogel technologies serve premium payloads that justify elevated cost structures, supporting the total value pool of the North America insulated shipping containers market.
Thermal performance standards are tightening, spurred by FDA validation protocols and EPA recycling guidance. Vendors such as Sealed Air deliver thinner VIP panels that shrink package footprints by 30% while maintaining temperature hold times. EPS suppliers pilot recycled content formulations to comply with state plastics statutes. The result is an increasingly segmented material choice matrix where purchasers weigh acquisition costs against reverse-logistics savings, disposal fees, and customer sustainability expectations.
Life sciences and pharmaceuticals account for 37.45% of North America's insulated shipping containers market share in 2025 and typically specify leak-proof, data-ready containers validated for 2-8 °C lanes. Compliance burdens extend sales cycles but also sustain premium price points and predictable reorder cadence. Direct-to-consumer protein services push fresh meat and seafood shipping, growing at a 6.79% CAGR, and require containers that balance ice-pack mass with box wall thickness to meet overnight timelines.
Meal kit operators maintain demand for mid-capacity EPS boxes fitted with gel packs, while frozen food categories sustain a baseline for rigid boxes capable of dry-ice payloads. Specialty niches like floral logistics rely on humidity-resilient liners to mitigate wilting risk. Pharmaceutical dominance is anchored in higher cost tolerance and stringent validation, even as diversified food verticals broaden the total addressable volume for the North America insulated shipping containers market.
Complete Report Scope:
- By Material Type
- Expanded Polystyrene (EPS)
- Polyurethane Foam (PU)
- Expanded Polypropylene (EPP)
- Biodegradable Starch-blend Foams
- Other Materials (VIPs, Gel Packs)
- By End-User Application
- Life Sciences and Pharmaceutical
- Pre-cooked and Frozen Food
- Fresh Produce
- Fresh Meat and Seafood
- Bakery, Plants and Flowers
- Other (Cosmetics, Wine, Beverages)
- By Product Type
- Single-Use Rigid Box Shippers
- Reusable Rigid Box Shippers
- Single-Use Pouch and Mailer Shippers
- Pallet-sized Bulk Shippers
- By Capacity Range
- Upto 5 L
- 5 - 20 L
- 20 - 60 L
- Greater than 60 L (Pallet)
- By Country
- United States
- Canada
List of Companies Covered in this Report:
- Sonoco Products Company
- TemperPack Technologies Inc.
- Polar Tech Industries Inc.
- Intelsius Ltd. (DGP Intelsius)
- Cascades Inc.
- Sofrigam SA
- Softbox Systems US LLC
- Cold Chain Technologies LLC
- Cryopak Industries Inc.
- Insulated Products Corporation
- KodiaKooler, a division of Airlite Plastics Co.
- Packaging Technology Group Inc.
- Therapak LLC (Avantor, Inc.)
- NanoCool LLC (part of UPS Healthcare)
- Chill-Pak Inc.
- va-Q-tec AG
- Envirotainer AB
- Pelican BioThermal LLC
- Emball'iso S.A.
- InsulTote LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 E-commerce surge in temperature-sensitive meal kits
- 4.2.2 Growth in pharmaceutical cold-chain expansion
- 4.2.3 Tightening U.S. FDA biologics stability guidance
- 4.2.4 Retailer sustainability mandates for reusable shippers
- 4.2.5 USDA grants for food-loss reduction programs
- 4.2.6 Venture capital entering direct-to-patient logistics
- 4.3 Market Restraints
- 4.3.1 Escalating cost of bio-based insulation resins
- 4.3.2 Limited reverse-logistics infrastructure for returns
- 4.3.3 Volatile recycled EPS feedstock availability
- 4.3.4 State-level EPR (extended-producer-responsibility) fees
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material Type
- 5.1.1 Expanded Polystyrene (EPS)
- 5.1.2 Polyurethane Foam (PU)
- 5.1.3 Expanded Polypropylene (EPP)
- 5.1.4 Biodegradable Starch-blend Foams
- 5.1.5 Other Materials (VIPs, Gel Packs)
- 5.2 By End-User Application
- 5.2.1 Life Sciences and Pharmaceutical
- 5.2.2 Pre-cooked and Frozen Food
- 5.2.3 Fresh Produce
- 5.2.4 Fresh Meat and Seafood
- 5.2.5 Bakery, Plants and Flowers
- 5.2.6 Other (Cosmetics, Wine, Beverages)
- 5.3 By Product Type
- 5.3.1 Single-Use Rigid Box Shippers
- 5.3.2 Reusable Rigid Box Shippers
- 5.3.3 Single-Use Pouch and Mailer Shippers
- 5.3.4 Pallet-sized Bulk Shippers
- 5.4 By Capacity Range
- 5.4.1 Upto 5 L
- 5.4.2 5 - 20 L
- 5.4.3 20 - 60 L
- 5.4.4 Greater than 60 L (Pallet)
- 5.5 By Country
- 5.5.1 United States
- 5.5.2 Canada
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Sonoco Products Company
- 6.4.2 TemperPack Technologies Inc.
- 6.4.3 Polar Tech Industries Inc.
- 6.4.4 Intelsius Ltd. (DGP Intelsius)
- 6.4.5 Cascades Inc.
- 6.4.6 Sofrigam SA
- 6.4.7 Softbox Systems US LLC
- 6.4.8 Cold Chain Technologies LLC
- 6.4.9 Cryopak Industries Inc.
- 6.4.10 Insulated Products Corporation
- 6.4.11 KodiaKooler, a division of Airlite Plastics Co.
- 6.4.12 Packaging Technology Group Inc.
- 6.4.13 Therapak LLC (Avantor, Inc.)
- 6.4.14 NanoCool LLC (part of UPS Healthcare)
- 6.4.15 Chill-Pak Inc.
- 6.4.16 va-Q-tec AG
- 6.4.17 Envirotainer AB
- 6.4.18 Pelican BioThermal LLC
- 6.4.19 Emball'iso S.A.
- 6.4.20 InsulTote LLC
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


