

|
시장보고서
상품코드
2124694
싱가포르의 핀테크 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Singapore Fintech - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
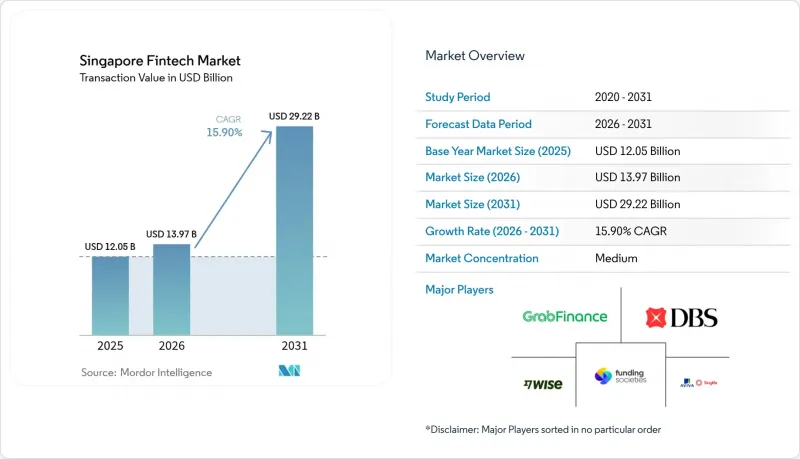
에 의하면, 2026년 싱가포르 핀테크 시장 규모는 139억 7,000만 달러로 추정되고, 2025년 120억 5,000만 달러에서 확대해, 2031년에는 292억 2,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR)은 15.9%를 나타낼 전망입니다.
본 보고서는 서비스 분야별(디지털 결제, 디지털 대출·자금 조달, 디지털 투자, 인슈어테크, 네오뱅킹), 최종 사용자별(개인, 기업), 사용자 인터페이스별(모바일 앱, 웹/브라우저,POS/IoT 기기), 그리고 지역별(중부 지역, 동부 지역, 북부 지역, 북동부 지역, 서부 지역)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
싱가포르의 핀테크 시장 동향 및 인사이트
실시간 결제 네트워크가 결제의 경제성을 혁신
‘프로젝트 넥서스’는 2026년까지 싱가포르, 말레이시아, 태국, 필리핀, 인도의 결제 네트워크를 연결하여 노스트로 계좌의 필요성을 없애고, 결제 기간을 T+2에서 실시간으로 단축할 예정입니다. 이러한 전환을 통해 약 1,200억 달러에 달하는 묶여 있던 유동성이 해방되고, 국경 간 거래 수수료가 절감됨에 따라 가맹점 및 중소기업에 즉각적인 비용 절감 효과가 나타날 것입니다. 조기에 통합을 추진하는 핀테크 기업들은 B2B 무역 금융 분야에서 시장 점유율을 확대할 것으로 전망됩니다. 이 분야에서는 실시간 결제를 통해 선적 시점과 연동된 운전자금 상품을 이용할 수 있게 됩니다. PayNow와 PromptPay, DuitNow 간에 구축된 양자 간 협력은 2024년에 250만 건 이상의 거래를 처리하며, 지역 내 실시간 결제에 대한 고객 수요가 입증되었습니다. 결제 인프라가 통합됨에 따라 전통 은행들은 레거시 API를 개편해야 하며, 그렇지 않을 경우 수익성이 높은 거래 분야를 기동력 있는 신생 기업들에게 빼앗길 위험이 있습니다. 이 새로운 인프라는 소액 결제 및 소액 보험도 지원하여 동남아시아 전역에서 적용 가능한 이용 사례를 확대되고 있습니다.
양자 내성 혁신에 대한 자금 지원이 경쟁적 차별화를 가속화
FSTI 3.0을 통해 MAS는 양자 내성 암호화 및 AI 기반 위험 분석을 도입하는 프로젝트에 대해 최대 50%의 공동 자금 지원을 제공합니다. 이 보조금을 통해 중견 핀테크 기업의 설비 투자 장벽이 낮아지고, 규제 의무화 이전에 사이버 보안 체계를 강화할 수 있게 됩니다. ‘사이버 기술 복원력 전문가(CTREX)’ 패널 내 협력을 통해 마이크로소프트, 아마존, 구글 클라우드로부터의 지식 이전이 보장되며, 국내 기준이 세계 모범 사례와 부합하도록 하고 있습니다. 선도 기업들은 이미 쇼어 알고리즘을 이용한 공격을 견딜 수 있는 양자 내성 결제 프로토콜을 시험하고 있으며, 포스트 양자암호화가 의무화되었을 때 규정 준수 요건을 충족할 수 있는 체계를 갖추고 있습니다. 양자 내성 키 교환을 채택한 은행들은 고액 자금 이동을 보호하고 있으며, 이를 통해 싱가포르는 ‘세이프 하버(Safe Harbor)’형 금융 호스팅 분야에서 선구자로서의 우위를 확립하고 있습니다. 장기적으로는 양자 기술을 활용한 최적화를 통해 신용 위험 모델링 및 포트폴리오 재조정 효율성이 향상되어, 전체 부문의 생산성이 높아질 가능성이 있습니다.
고객 확보 비용이 핀테크의 수익성 모델에 큰 부담으로 작용하고 있다.
스마트폰 보급률이 거의 100%에 달함에 따라, 타겟 고객 기반은 포화 상태에 이르렀고, 신규 고객 확보에 드는 한계 비용은 점점 더 치솟고 있습니다. 2024년에는 전자 지갑 신규 등록에 대한 인센티브 예산이 40-60%나 급증하여, 소규모 핀테크 기업의 투자 회수 기간이 30개월을 초과하는 사태가 벌어지고 있습니다. 게다가 소비자들이 차량 호출 서비스, 음식 배달, 결제 기능을 통합한 ‘Grab’과 같은 다기능 슈퍼 앱을 선호하는 경향이 있어, 앱 피로감이 마케팅 비용 대비 효과를 더욱 떨어뜨리고 있습니다. 이러한 동향으로 인해 단독으로 사업을 전개하는 벤더들은 임베디드 파이낸스(Embedded Finance) 파트너십으로 방향을 전환할 수밖에 없게 되었습니다. 즉, 가맹점이나 플랫폼의 생태계에 서비스를 통합하여 고객 확보 비용을 분담하는 것입니다. B2B2C 유통 모델 또한 단위 경제성을 향상시킵니다. 예를 들어, 중소기업용 소프트웨어 벤더는 청구서와 연동된 신용 한도를 도입함으로써 마케팅 비용을 여러 수익원으로 분산시킬 수 있습니다. 따라서 치솟은 고객 확보 비용은 선별 메커니즘으로 기능하여, 견고한 생태계나 차별화된 지적 재산(IP)을 보유한 핀테크 기업에는 보상을 주는 반면, 자금력이 약한 스타트업에게는 통합이나 철수를 강요하게 됩니다.
부문 분석
2025년, 디지털 결제는 싱가포르 핀테크 시장 규모의 26.20%를 차지했으며, 일상적인 상거래에서 중심적인 역할을 반영하고 있습니다. 이 부문은 SGQR+의 상호 운용성, 가맹점의 SoftPOS 도입, 그리고 PayNow의 지역 연동에 힘입어 2031년까지 연평균 성장률(CAGR) 16.95%로 성장할 전망입니다. 계좌 간 송금을 통한 카드 결제망 우회는 인터체인지 수수료를 절감하고, 가맹점이 QR 결제나 즉시 결제를 우선적으로 선택하도록 유도하고 있습니다. 한편, 디지털 대출 분야의 대체 신용 평가 시스템은 긱 워커를 대상으로 신속한 심사 및 대출이 가능한 소액 대출을 지속적으로 제공하고 있지만, 그 성장 속도는 결제 분야에 비해 완만합니다. 인슈어테크 기업들은 라이드셰어 및 배달 앱 내에 소액 보험을 통합하여, 별도의 보험 계약 체결 없이도 고객 도달 범위를 확대되고 있습니다. StashAway와 같은 웰스테크 플랫폼은 저비용 ETF 포트폴리오를 기반으로 규모를 확대하며, 대중 부유층의 자산을 두고 프라이빗 뱅크에 도전하고 있습니다. MAS(싱가포르 금융관리청)의 규제 샌드박스는 결제, 대출, 보험을 결합한 실험을 지원하여 종합적인 금융 서비스 제공을 촉진하고 있습니다. 2030년까지 통합 플랫폼이 국내 소매 거래액의 40% 이상을 차지할 것으로 예상되며, 결제는 보다 광범위한 핀테크 생태계의 핵심으로서 확고한 입지를 다지게 될 것입니다.
디지털 지갑 사업자들이 신용 한도나 보험 부가 서비스를 확대하고, 기존 부문 간의 경계가 모호해짐에 따라 경쟁은 격화되고 있습니다. 슈퍼앱은 자사가 보유한 소비 데이터를 활용하여 신용 심사를 정교화하는 한편, 기존 기업들은 API를 개방하여 가맹점의 결제 흐름에서 입지를 유지하려 하고 있습니다. 따라서 싱가포르 핀테크 시장에서는 판매 시점(POS)을 장악하고, 빈도가 높은 결제 이용 사례에 고마진 부가 서비스를 접목할 수 있는 사업자가 계속해서 우위를 점하는 상황이 이어지고 있습니다. 토큰화된 예금 및 네트워크 토큰화에 대한 규제 당국의 지원으로 보안과 인터체인지의 경제성이 더욱 향상되고 있습니다. 실시간 결제 인프라가 성숙해짐에 따라, 결제 수익은 거래당 수수료가 아닌 부가가치 있는 데이터 분석, 로열티 프로그램, 결제 서비스에서 얻어지는 비중이 점점 더 높아질 것입니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, Singapore fintech market size in 2026 is estimated at USD 13.97 billion, growing from 2025 value of USD 12.05 billion with 2031 projections showing USD 29.22 billion, growing at 15.9% CAGR over 2026-2031.
This report is Segmented by Service Proposition (Digital Payments, Digital Lending & Financing, Digital Investments, Insurtech, Neobanking), End-User (Retail, Businesses), User Interface (Mobile Applications, Web/Browser, POS/IoT Devices), and Geography (Central Region, East Region, North Region, North-East Region, West Region). The Market Forecasts are Provided in Terms of Value (USD).
Singapore Fintech Market Trends and Insights
Real-Time Payment Rails Transform Settlement Economics
Project Nexus will connect payment rails in Singapore, Malaysia, Thailand, the Philippines, and India by 2026, eliminating the need for nostro accounts and cutting settlement from T+2 to real-time . The shift frees up an estimated USD 120 billion in trapped liquidity and reduces cross-border transaction fees, generating immediate cost savings for merchants and SMEs. Early integrating fintech firms will gain share in B2B trade finance, where real-time settlement unlocks working-capital products tied to shipment milestones. PayNow's bilateral links with PromptPay and DuitNow processed more than 2.5 million transactions in 2024, demonstrating proven customer appetite for instant regional payments. As rails converge, traditional banks must overhaul legacy APIs or risk ceding high-margin corridors to nimble challengers. The new infrastructure also supports micropayments and micro-insurance, widening addressable use cases across Southeast Asia.
Quantum-Ready Innovation Funding Accelerates Competitive Differentiation
Through FSTI 3.0, MAS co-funds up to 50% of projects deploying quantum-resistant encryption and AI-powered risk analytics. The subsidy lowers capex barriers for mid-tier fintechs, enabling them to harden cybersecurity stacks ahead of regulatory mandates. Collaboration inside the Cyber and Technology Resilience Experts (CTREX) panel ensures knowledge transfer from Microsoft, Amazon, and Google Cloud, aligning domestic standards with global best practices. Early movers already test quantum-safe payment protocols that withstand Shor-algorithm attacks, positioning them for compliance once post-quantum cryptography becomes compulsory. Banks adopting quantum-secure key exchange safeguard high-value treasury flows, giving Singapore a first-mover lead in safe-harbor financial hosting. Over the long term, quantum-enhanced optimization may also streamline credit-risk modelling and portfolio rebalancing, boosting sector productivity.
Customer Acquisition Costs Strain Fintech Profitability Models
Nearly universal smartphone ownership produces a saturated addressable base, making marginal customer wins increasingly expensive. Incentive budgets for e-wallet sign-ups ballooned by 40-60% in 2024, pushing payback periods for small fintechs beyond 30 months. App fatigue further erodes return on marketing spend because consumers prefer multifunction super-apps such as Grab, which bundle ride-hailing, food delivery, and payments. The trend forces standalone providers to pivot toward embedded-finance partnerships, integrating services into merchant or platform ecosystems to share acquisition costs. B2B2C distribution also improves unit economics; SME software vendors, for example, can embed invoicing-linked credit lines, spreading marketing costs across multiple revenue streams. Elevated acquisition costs therefore act as a filtering mechanism, rewarding fintechs with strong ecosystems or differentiated IP, while pushing under-capitalized startups to consolidate or exit.
Other drivers and restraints analyzed in the detailed report include:
- Cross-Border E-Commerce Growth Drives Multi-Currency Innovation
- Digital Banking Licenses Create Niche Market Opportunities
- Regulatory Tightening Constrains High-Growth Fintech Segments
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, digital payments accounted for 26.20% of the Singapore fintech market size, reflecting their central role in day-to-day commerce. The segment is on track to expand at a 16.95% CAGR through 2031, propelled by SGQR+ interoperability, merchant SoftPOS adoption, and PayNow's regional links. Card-rail bypass via account-to-account transfers reduces interchange fees, encouraging merchants to prioritize QR and instant payments. Meanwhile, alternative credit scoring in digital lending continues to unlock quick-turnaround microloans for gig workers, albeit at a slower growth than payments. Insurtech firms embed bite-sized coverage within ride-hailing and delivery apps, widening reach without requiring stand-alone policy purchases. Wealth-tech platforms such as StashAway scale on low-cost ETF portfolios, challenging private banks for mass-affluent assets. MAS's regulatory sandbox supports experiments that bundle payments, lending, and insurance, fostering holistic financial offerings. By 2030, integrated platforms are expected to direct more than 40% of domestic retail transaction value, cementing payments as the linchpin of broader fintech ecosystems.
Competition intensifies as digital-wallet providers extend credit lines and insurance add-ons, blurring traditional segment boundaries. Super-apps leverage first-party consumption data to refine underwriting, while incumbents open APIs to retain relevance within merchant checkout flows. The Singapore fintech market, therefore, continues to reward providers that control the point of sale and can layer higher-margin, add-on services onto high-frequency payment use cases. Regulatory support for tokenized deposits and network tokenization further improves security and interchange economics. As real-time rails mature, payments revenue will increasingly derive from value-added data analytics, loyalty, and payment services rather than per-transaction fees.
Complete Report Scope:
- By Service Proposition
- Digital Payments
- Digital Lending & Financing
- Digital Investments
- Insurtech
- Neobanking
- By End-User
- Retail
- Businesses
- By User Interface
- Mobile Applications
- Web / Browser
- POS / IoT Devices
- By Geography
- Central Region
- East Region
- North Region
- North-East Region
- West Region
List of Companies Covered in this Report:
- Grab Financial Group
- DBS Bank
- OCBC Bank
- UOB Bank
- PayPal Singapore
- Wise
- Stripe Singapore
- Adyen Singapore
- Nium
- Thunes
- FOMO Pay
- Funding Societies
- Validus
- StashAway
- Endowus
- Singlife with Aviva
- Bolttech
- GXS Bank
- Trust Bank
- ANEXT Bank
- Revolut Singapore
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid real-time payment rail adoption (PayNow, Project Nexus)
- 4.2.2 MAS grants spurring AI & quantum-ready fintech innovation
- 4.2.3 Cross-border e-commerce fueling multi-currency wallets
- 4.2.4 Digital-only banking licences opening new niches
- 4.2.5 ESG & green-finance mandates creating new fintech revenue pools
- 4.2.6 SME credit gap boosting alternative lending platforms
- 4.3 Market Restraints
- 4.3.1 High customer-acquisition costs amid intense app competition
- 4.3.2 Tightened MAS consumer-protection rules on crypto & BNPL
- 4.3.3 Talent shortages in AI / cybersecurity raising OPEX
- 4.3.4 Interoperability & legacy core-bank integration hurdles
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Service Proposition
- 5.1.1 Digital Payments
- 5.1.2 Digital Lending & Financing
- 5.1.3 Digital Investments
- 5.1.4 Insurtech
- 5.1.5 Neobanking
- 5.2 By End-User
- 5.2.1 Retail
- 5.2.2 Businesses
- 5.3 By User Interface
- 5.3.1 Mobile Applications
- 5.3.2 Web / Browser
- 5.3.3 POS / IoT Devices
- 5.4 By Geography
- 5.4.1 Central Region
- 5.4.2 East Region
- 5.4.3 North Region
- 5.4.4 North-East Region
- 5.4.5 West Region
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Grab Financial Group
- 6.4.2 DBS Bank
- 6.4.3 OCBC Bank
- 6.4.4 UOB Bank
- 6.4.5 PayPal Singapore
- 6.4.6 Wise
- 6.4.7 Stripe Singapore
- 6.4.8 Adyen Singapore
- 6.4.9 Nium
- 6.4.10 Thunes
- 6.4.11 FOMO Pay
- 6.4.12 Funding Societies
- 6.4.13 Validus
- 6.4.14 StashAway
- 6.4.15 Endowus
- 6.4.16 Singlife with Aviva
- 6.4.17 Bolttech
- 6.4.18 GXS Bank
- 6.4.19 Trust Bank
- 6.4.20 ANEXT Bank
- 6.4.21 Revolut Singapore
7 Market Opportunities & Future Outlook
- 7.1 Embedded finance in non-financial super-apps
- 7.2 Green fintech solutions for carbon-credit trading


