

|
시장보고서
상품코드
2124813
마이크로컨트롤러(MCU) : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Microcontroller (MCU) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
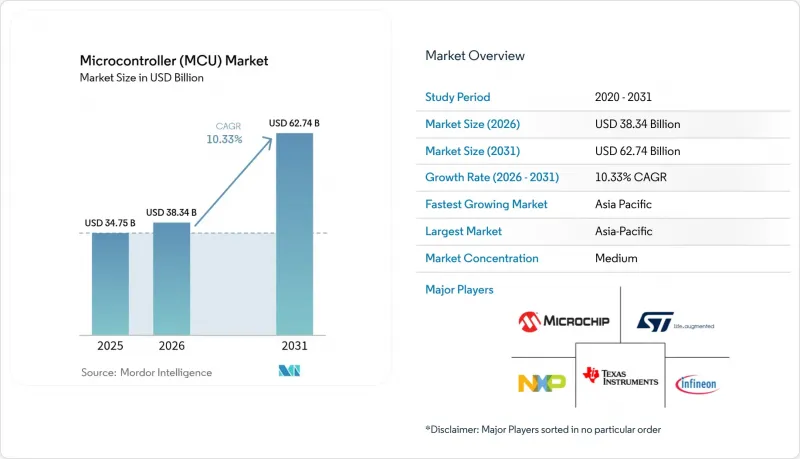
에 의하면, 마이크로컨트롤러(MCU) 시장 규모는 2025년에 347억 5,000만 달러로 평가되었습니다. 2026년 383억 4,000만 달러에서 2031년까지 627억 4,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 10.33%를 나타낼 전망입니다.
본 보고서는 비트 클래스(4비트 이하, 8비트, 16비트, 기타), 코어 아키텍처(ARM Cortex-M, RISC-V, x86, 기타), 온칩 메모리 유형(임베디드 플래시, FRAM, 기타),용도(자동차, 산업·공장 자동화, 헬스케어, 기타), 지역(북미, 유럽, 아시아태평양, 기타)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 마이크로컨트롤러(MCU) 시장 동향 및 인사이트
IoT 노드의 급증으로 임베디드 인텔리전스 수요 견인
2030년까지 연결된 엔드포인트 수는 200억 대를 넘어설 것으로 예측되며, 각 제조업체는 비용 중심의 설계에 멀티 프로토콜 무선 기능과 고효율 프로세서를 통합해야 할 필요성에 직면해 있습니다. Nordic Semiconductor의 nRF54 시리즈는 Bluetooth LE 5.4, Thread, Matter를 단일 디바이스에 통합하면서도 배터리 수명에 도움이 되는 저전력 소비를 유지함으로써 부품 비용과 펌웨어의 복잡성을 줄이고 있습니다. 고도의 로컬 처리를 통해 구현되는 고가 분석 서비스는 수익 모델을 순수한 하드웨어 판매에서 전환시키고 있습니다. Synaptics와 같은 반도체 공급업체들은 범용 컴퓨팅을 추구하기보다는 IoT에 최적화된 솔루션으로 포트폴리오 재편을 추진하고 있습니다.
자동차의 전동화와 ADAS 통합이 MCU 탑재 수 증가를 가속화
배터리식 전기차에는 최대 3,000개의 반도체 부품이 탑재되며, 내연기관 차량에 비해 MCU 탑재 수는 4배 증가했습니다. 메르세데스-벤츠는 ISO 26262를 준수하여 배터리, 열 관리, 회생 제동 시스템을 관리하기 위해 개별 마이크로컨트롤러 클러스터를 채택하고 있습니다. 콘티넨탈과 NXP의 제휴를 통해 여러 섀시 기능이 소프트웨어를 통해 업그레이드 가능한 도메인 컨트롤러로 통합되어 배선 무게가 줄어들었을 뿐만 아니라, 원활한 무선 업데이트도 가능해졌습니다. 2026년까지 모든 차종에 첨단 운전자 보조 시스템(ADAS)의 탑재를 의무화하는 EU 규제는 이러한 변화를 더욱 가속화하고 있습니다. 혼다와 르네사스의 제휴를 통한 2,000TOPS SoC의 공동 개발은 연산 능력에 대한 수요가 마이크로컨트롤러(MCU) 시장을 어떻게 변화시키고 있는지를 여실히 보여줍니다.
공급망의 주기성이 재고와 가격 변동을 초래한다.
파운드리 생산 일정의 변동으로 인해 MCU 공급업체들은 웨이퍼 할당량이 급격히 변화할 위험에 노출되어 있습니다. 최근 재고 소진 국면에서 2023년 매출이 30% 감소함에 따라 노르딕 세미컨덕터는 직원의 8%를 감원할 수밖에 없었습니다. 금속 실리콘공급 과잉으로 인해 2025년 4월 벤치마크 현물 가격은 2.3% 하락하여 1kg당 2.95달러를 기록했으나, 관세 도입으로 인해 이러한 비용 절감 효과가 역전될 우려가 있습니다. 대만, 중국 본토, 한국에 성숙 노드의 생산 능력이 집중되어 있어 지정학적 리스크 프리미엄이 확대되고 있으며, 각 OEM 기업들은 운전자금을 묶어두는 완충 재고 확보에 자금을 투입할 수밖에 없는 상황입니다.
부문별 분석
2025년, 32비트 디바이스는 마이크로컨트롤러(MCU) 시장 점유율의 56.35%를 차지하며, 복잡한 워크로드로의 결정적인 전환을 보여주었습니다. 이 부문은 ADAS(첨단 운전자 보조 시스템)의 센서 퓨전, 산업용 구동 제어, 음성 인식 기능이 탑재된 소비자용 기기에 힘입어 연평균 성장률(CAGR) 8.76%를 나타낼 것으로 예측됩니다. 32비트 아키텍처는 더 큰 주소 지정 가능 메모리를 가능하게 하고, 디지털 신호 처리(DSP) 확장 기능을 통합하여 외부 부품의 필요성을 줄여줍니다. MCU 설계자들은 현재 신경망 엔진과 사이버 보안 가속기를 칩에 직접 통합하고 있어, 별도의 코프로세서가 더 이상 필요하지 않게 되었습니다. 저가형 8비트 및 16비트 제품은 여전히 인터페이스 로직 영역에서 유효한 반면, 4비트 이하의 변형 제품은 수익성이 극히 낮은 범주에 속하는 리모컨이나 온도 조절기 등에서 여전히 사용되고 있습니다.
개발자들 사이에서는 보안 부팅, CAN-FD, 다중 프로토콜 무선 기능을 단일 패키지에 통합한 싱글 칩 프로토타입에 대한 수요가 점점 더 높아지고 있습니다. 이러한 올인원화 추세는 제품 라인 전반에 걸친 플랫폼 재사용을 가능하게 하고, 펌웨어 유지보수 부담을 줄여줍니다. 반면, 32비트 디바이스에 통합된 FRAM 옵션은 충전 펌프로 인한 오버헤드 없이 즉시 쓰기 기능을 제공하며, 이는 진동이 심한 환경에서 작동하는 데이터 로깅 센서에게 매우 중요합니다.
Cortex-M 코어는 성숙한 툴체인 및 견고한 미들웨어 스택에 힘입어 2025년 출하량의 68.25%를 차지했습니다. 고객들은 도입 직후부터 이용할 수 있는 RTOS 지원과 디버깅 주기를 단축하는 풍부한 커뮤니티 라이브러리를 높이 평가했습니다. 그러나 RISC-V의 연평균 성장률(CAGR) 15.09%는 로열티 비용 없이 명령어 세트를 맞춤화할 수 있다는 점에 대한 열망이 높아지고 있음을 보여줍니다. 각국 정부는 기술 주권을 지키기 위해 국내 RISC-V 프로그램을 전개하고 있으며, 웨어러블에서 자동차용 게이트웨이 노드에 이르기까지 오픈 ISA 치플릿에 보조금을 투입하고 있습니다. 반면, 결정적인 사이클 정밀도 응답이 요구되는 틈새 시장인 항공 전자 장비 및 산업용 드라이브 분야에서는 여전히 독점적인 코어가 사용되고 있으며, 서버급 보드 관리 컨트롤러에는 x86 프로세서가 채택되고 있습니다.
마이크로컨트롤러(MCU) 시장에서 벤더의 성공은 개발 환경의 충실도에 좌우됩니다. ARM은 TrustZone, PSA 인증 보안, M-Profile 벡터 확장 기능을 지속적으로 강화하고 있는 반면, RISC-V 그룹은 분열을 방지하기 위해 소프트웨어 계층의 통일된 조화에 투자하고 있습니다. 일부 공급업체는 동일한 제품군 내에서 핀 호환성이 있는 ARM 또는 RISC-V 대체 제품을 제공함으로써 위험을 분산시키고 있습니다.
지역별 분석
아시아태평양은 중국의 가전제품 조립 생태계와 일본의 자동차용 반도체 기술력을 바탕으로 2025년에는 전 세계 매출의 47.30%를 차지했습니다. 중국의 ‘반도체 자급’을 목표로 하는 5개년 계획은 가전제품 및 공공 충전 인프라 분야에서 국내 MCU의 테이프아웃 수요를 견인하고 있습니다. 일본공급업체들은 오랜 기간 OEM과 구축해 온 견고한 관계를 바탕으로, 하이브리드 차량의 구동 사이클에 맞게 특별히 설계된 파워트레인 인증 마이크로컨트롤러 분야에서 입지를 유지하고 있습니다. 한국의 대기업들은 네이티브 메모리 IP를 로직 블록과 통합하여 스마트폰 및 스마트 TV용 원칩 솔루션을 구축하고 있습니다. 인건비, 에너지 비용, 지정학적 리스크 증가로 인해 베트남이나 태국으로 사업을 다각화하는 기업도 일부 보이지만, 해당 지역의 결속력 있는 부품 생태계가 비교 우위를 유지하고 있어 마이크로컨트롤러(MCU) 시장에서 가장 빠르게 성장하는 시장으로서의 지위를 지키고 있습니다.
남미는 2020년부터 2031년까지 연평균 성장률(CAGR) 10.22%를 기록하며, 마이크로컨트롤러(MCU) 시장에서 가장 빠르게 성장하는 지역 중 하나로 부상하고 있습니다. 브라질의 자동차 생산에 대한 새로운 우대 조치와 멕시코의 USMCA(미국·멕시코·캐나다 협정)에 따른 수출 회랑은 현지에서 조달된 MCU가 필요한 전기차(EV) 플랫폼 조립을 유치하고 있습니다. 정부 주도의 재생에너지망 구축이 스마트 미터 도입을 촉진하고 있으며, 이는 결과적으로 보안성이 뛰어나고 저전력 소비를 자랑하는 32비트 컨트롤러에 대한 수요를 뒷받침하고 있습니다. 현지 조달 의무로 인해 전 세계 반도체 공급업체와 지역 설계 회사 간의 합작 투자가 촉진되고, 임베디드 소프트웨어 스택 분야의 인재 양성이 가속화되고 있습니다. 북미는 고부가가치이며 안전성이 극히 중요한 틈새 시장에 주력하고 있습니다. ‘CHIPS법’에서는 웨이퍼 공장 건설에 수십억 달러가 배정되었지만, 그 생산 능력의 대부분은 성숙한 MCU의 미세 구조가 아닌 10nm 미만의 노드를 대상으로 하고 있습니다. 방위 관련 기업들은 국내 생산 및 공급망 증명을 의무화하고 있어, ITAR 준수 부품에 대한 안정적인 수요가 확보되고 있습니다. 유럽에서는 자동차 및 공정 자동화 분야에서 ISO 26262 및 IEC 62443 준수에 중점을 두고 있습니다. TSMC가 계획 중인 드레스덴 공장은 유럽의 1차 공급업체에 매월 4만 장의 300mm 웨이퍼를 공급하여, 고신뢰성 마이크로컨트롤러의 리드 타임을 단축할 전망입니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the microcontroller market size was valued at USD 34.75 billion in 2025 and estimated to grow from USD 38.34 billion in 2026 to reach USD 62.74 billion by 2031, at a CAGR of 10.33% during the forecast period (2026-2031).
This report is Segmented by Bit Class (4-Bit and Below, 8-Bit, 16-Bit, and More), Core Architecture (ARM Cortex-M, RISC-V, X86, and More), On-Chip Memory Type (Embedded Flash, FRAM, and More), Application (Automotive, Industrial and Factory Automation, Healthcare, and More), and Geography (North America, Europe, Asia Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Microcontroller (MCU) Market Trends and Insights
IoT Node Proliferation Drives Embedded Intelligence Demand
Connected endpoints are projected to exceed 20 billion units by 2030, forcing manufacturers to embed multi-protocol radios and efficient processors into cost-sensitive designs. Nordic Semiconductor's nRF54 series combines Bluetooth LE 5.4, Thread, and Matter in a single device, while maintaining a battery-friendly current draw, thereby reducing the bill of materials and firmware complexity . Premium-priced analytics services, enabled by richer local processing, shift revenue models away from pure hardware sales. Semiconductor suppliers, such as Synaptics, are repositioning their portfolios toward IoT-optimized solutions rather than pursuing general-purpose computing.
Automotive Electrification and ADAS Integration Accelerate MCU Content Growth
A battery-electric vehicle can host up to 3,000 semiconductor components, quadrupling the MCU footprint versus internal-combustion models. Mercedes-Benz relies on discrete microcontroller clusters to manage the battery, thermal, and regenerative braking systems in accordance with ISO 26262. Continental's cooperation with NXP centralizes multiple chassis functions into software-upgradable domain controllers, cutting wiring weight and enabling seamless over-the-air updates. EU regulations mandating the deployment of advanced driver-assistance systems across all classes by 2026 further amplify this shift. Honda's partnership with Renesas to co-develop 2,000 TOPS SoCs highlights how computational demands are reshaping the Microcontroller market.
Supply-Chain Cyclicality Creates Inventory and Pricing Volatility
Foundry scheduling swings expose MCU vendors to abrupt wafer-allocation shifts. Recent inventory digestion phases forced Nordic Semiconductor to cut 8% of its workforce after revenue fell 30% in 2023 . The oversupply of metal-silicon pulled benchmark spot prices down 2.3% to USD 2.95/kg in April 2025, yet tariffs threaten to reverse the cost gains . The concentration of mature-node capacity in Taiwan, mainland China, and South Korea magnifies geopolitical risk premiums, prompting OEMs to fund buffer stocks that tie up working capital.
Other drivers and restraints analyzed in the detailed report include:
- Smart-Home and Appliance MCU Integration Transforms Consumer Electronics
- Shift to RISC-V Open ISA Disrupts Traditional Licensing Models
- ASP Erosion from Chinese Fabs Intensifies Pricing Competition
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, 32-bit devices captured 56.35% of the Microcontroller market share, illustrating a decisive tilt toward complex workloads. The segment is projected to grow at an 8.76% CAGR, driven by ADAS sensor fusion, industrial drive control, and voice-enabled consumer gadgets. 32-bit architectures enable larger addressable memory and integrate digital-signal-processing extensions, thereby reducing the need for external components. MCU designers now embed neural engines and cybersecurity accelerators directly on the die, eliminating the need for discrete coprocessors. Lower-cost 8-bit and 16-bit parts remain viable in interface logic, while sub-4-bit variants linger in remote controls and thermostats serving ultra-thin margin categories.
Developers are increasingly requesting single-chip prototypes that incorporate secure boot, CAN-FD, and multi-protocol radio in a single package. This all-in-one trend supports platform reuse across product lines, reducing firmware maintenance. Meanwhile, integrated FRAM options on 32-bit units provide instant-write capability without charge-pump overhead, which is critical for data-logging sensors that operate in high-vibration environments.
Cortex-M cores supplied 68.25% of shipments in 2025, bolstered by mature toolchains and robust middleware stacks. Customers value out-of-the-box RTOS support and expansive community libraries that shorten debug cycles. Yet RISC-V's 15.09% CAGR points to mounting enthusiasm for instruction-set customization at zero royalty cost. Governments deploy domestic RISC-V programs to safeguard technology sovereignty, funneling subsidies toward open-ISA chiplets spanning wearables to automotive gateway nodes. Proprietary cores persist in niche avionics and industrial drives that require deterministic, cycle-accurate responses, whereas x86 processors are used in server-class board management controllers.
For the Microcontroller market, vendor success hinges on the richness of the development environment. ARM continues to extend TrustZone, PSA-Certified security, and M-Profile Vector Extensions, whereas RISC-V groups invest in unified software-layer harmonization to stave off fragmentation. Some suppliers hedge bets by offering pin-compatible ARM or RISC-V alternatives within the same product family.
Complete Report Scope:
- By Bit Class
- 4-bit and below
- 8-bit
- 16-bit
- 32-bit
- By Core Architecture
- ARM Cortex-M
- RISC-V
- x86
- Proprietary / Others
- By On-Chip Memory Type
- Embedded Flash
- FRAM
- EEPROM/OTP
- SRAM-only (code-in-RAM)
- By Application
- Automotive
- Consumer Electronics and Home Appliances
- Industrial and Factory Automation
- Healthcare
- Aerospace and Defense
- Data-Com and Cloud Infrastructure
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Taiwan
- Rest of Asia Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
APAC retained 47.30% of global revenue in 2025 on the strength of China's consumer-electronics assembly ecosystem and Japan's automotive semiconductor depth. Chinese five-year plans targeting local silicon autonomy create pull for domestic MCU tape-outs across home appliances and public-charging infrastructure. Japanese suppliers maintain traction with powertrain-qualified microcontrollers specifically designed for hybrid drive cycles, leveraging their long-standing OEM ties. South Korean conglomerates integrate native memory IP with logic blocks to build one-chip solutions for smartphones and smart TVs. Rising labor, energy, and geopolitical costs prompt some diversification into Vietnam and Thailand, yet the region's cohesive component ecosystem preserves its comparative advantage, keeping it as the fastest-growing market for microcontrollers.
South America emerges as one of the fastest-growing regions in the microcontroller market, with a 10.22% CAGR from 2020 to 2031. Brazil's renewed automotive-production incentives and Mexico's USMCA-enabled export corridors lure EV platform assembly that requires localized MCU sourcing. Government-directed renewable energy grids are driving the rollout of smart meters, which in turn boosts demand for secure, low-power 32-bit controllers. Local-content mandates spur joint ventures between global silicon vendors and regional design houses, catalyzing the development of talent around embedded software stacks. North America centers on high-value safety-critical niches. The CHIPS Act earmarks billions for wafer-fab construction, though most capacity targets sub-10 nm nodes rather than mature MCU geometries. Defense contractors stipulate onshore production and supply-chain attestations, ensuring steady demand for ITAR-compliant parts. Europe focuses on adhering to ISO 26262 and IEC 62443 within the automotive and process automation verticals. TSMC's planned Dresden fab will supply 40,000 300 mm wafers monthly to European Tier-1s, shortening lead times for high-reliability microcontrollers .
- Infineon Technologies AG
- Microchip Technology Inc.
- NXP Semiconductors N.V.
- STMicroelectronics N.V.
- Texas Instruments Incorporated
- Renesas Electronics Corporation
- Silicon Laboratories Inc.
- Nordic Semiconductor ASA
- Espressif Systems (Shanghai) Co., Ltd.
- GigaDevice Semiconductor Inc.
- Nuvoton Technology Corporation
- Toshiba Electronic Devices and Storage Corporation
- Rohm Co., Ltd.
- onsemi Corporation
- Holtek Semiconductor Inc.
- Ambiq Micro, Inc.
- ASR Microelectronics (Shanghai) Co., Ltd.
- Realtek Semiconductor Corp.
- Zilog, Inc.
- Analog Devices, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 IoT Node Proliferation
- 4.2.2 Automotive Electrification and ADAS
- 4.2.3 Smart-Home and Appliance MCU Integration
- 4.2.4 Shift to RISC-V Open ISA
- 4.2.5 Ultra-Low-Power Edge AI MCUs
- 4.2.6 Industrial Cybersecurity Mandates
- 4.3 Market Restraints
- 4.3.1 Supply-chain Cyclicality
- 4.3.2 ASP Erosion from Chinese Fabs
- 4.3.3 Rising NRE for sub-28 nm Embedded Flash
- 4.3.4 Talent Shortage in Mixed-Signal Design
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porters Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Bit Class
- 5.1.1 4-bit and below
- 5.1.2 8-bit
- 5.1.3 16-bit
- 5.1.4 32-bit
- 5.2 By Core Architecture
- 5.2.1 ARM Cortex-M
- 5.2.2 RISC-V
- 5.2.3 x86
- 5.2.4 Proprietary / Others
- 5.3 By On-Chip Memory Type
- 5.3.1 Embedded Flash
- 5.3.2 FRAM
- 5.3.3 EEPROM/OTP
- 5.3.4 SRAM-only (code-in-RAM)
- 5.4 By Application
- 5.4.1 Automotive
- 5.4.2 Consumer Electronics and Home Appliances
- 5.4.3 Industrial and Factory Automation
- 5.4.4 Healthcare
- 5.4.5 Aerospace and Defense
- 5.4.6 Data-Com and Cloud Infrastructure
- 5.4.7 Others
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 South Korea
- 5.5.3.4 India
- 5.5.3.5 Taiwan
- 5.5.3.6 Rest of Asia Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 GCC
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Infineon Technologies AG
- 6.4.2 Microchip Technology Inc.
- 6.4.3 NXP Semiconductors N.V.
- 6.4.4 STMicroelectronics N.V.
- 6.4.5 Texas Instruments Incorporated
- 6.4.6 Renesas Electronics Corporation
- 6.4.7 Silicon Laboratories Inc.
- 6.4.8 Nordic Semiconductor ASA
- 6.4.9 Espressif Systems (Shanghai) Co., Ltd.
- 6.4.10 GigaDevice Semiconductor Inc.
- 6.4.11 Nuvoton Technology Corporation
- 6.4.12 Toshiba Electronic Devices and Storage Corporation
- 6.4.13 Rohm Co., Ltd.
- 6.4.14 onsemi Corporation
- 6.4.15 Holtek Semiconductor Inc.
- 6.4.16 Ambiq Micro, Inc.
- 6.4.17 ASR Microelectronics (Shanghai) Co., Ltd.
- 6.4.18 Realtek Semiconductor Corp.
- 6.4.19 Zilog, Inc.
- 6.4.20 Analog Devices, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


