

|
시장보고서
상품코드
2154272
필리핀의 크롤러 토공 기계 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Philippines Crawler Earthmoving Machines - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
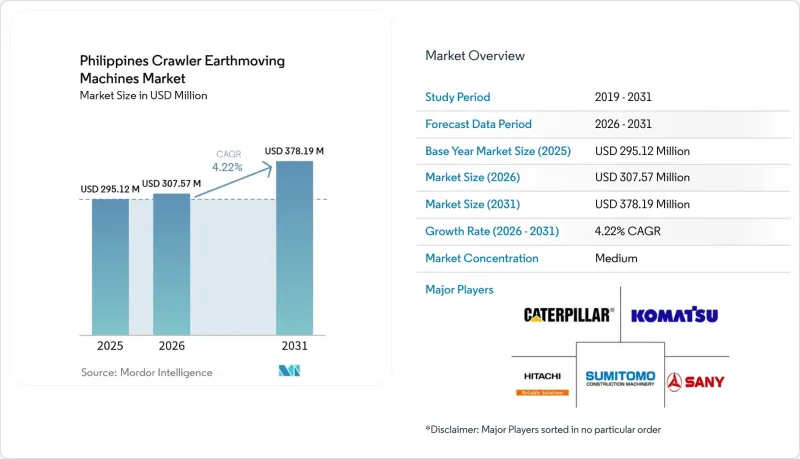
에 따르면 필리핀의 크롤러식 토목 기계 시장 규모는 2025년에 2억 9,512만 달러로 평가되며, 2026년에는 3억 757만 달러, 2031년까지 3억 7,819만 달러에 달할 것으로 예상되고 있으며, 2026-2031년에 CAGR 4.22%를 기록할 전망입니다.
필리핀 크롤러식 토목 기계 시장의 동향 및 인사이트
정부 주도의 ‘Build Better More(BBM)’ 인프라 계획
수십 개에 달하는 주요 교량, 고속도로 및 홍수 방지 시설의 건설이, 특히 기초 굴착 및 성토 공사에서 크롤러식 토공 기계의 지속적인 가동 주기를 이끌고 있습니다. 다자간 융자로 인해 국내 예산 삭감은 완화되고 있지만, 자금 지급이 지연될 경우 공사가 부분적으로 완료된 현장에서 기계가 유휴 상태가 되어 차량단의 가동률이 떨어질 가능성이 있습니다. 도급업체들은 착공 통지라는 마일스톤을 기다리는 동안 비용 면에서 유연성이 있는 계약을 선호하므로 렌탈 업체들이 혜택을 보고 있습니다. 도시로의 꾸준한 인구 유입으로 인해 지방 도시의 도로 개량 공사가 계속해서 계획에 포함되고 있으며, 메가 프로젝트의 진척이 정체되더라도 장기적인 장비 수요는 확고하게 유지되고 있습니다.
민다나오의 대규모 광업 및 채석 프로젝트 재개
북 술리가오 주에서 대규모 구리·금 프로젝트가 가동됨에 따라 가혹한 노천 채굴 주기에 연동된 수년에 걸친 크롤러 교체 수요가 발생했습니다. 가혹한 라텔라이트 지반은 언더캐리지의 마모를 가속화하므로 소유주는 더 짧은 정비 주기를 예상한 예산을 편성할 수밖에 없습니다. 세계 니켈 가격을 둘러싼 불확실성으로 인해 조달에 대한 신중함이 높아지고 있지만, 의무화된 복구 보증금으로 인해 사업자는 생산성이 높은 차량군을 유지할 수밖에 없습니다. 광산 물류와 관련된 지방 도로의 개보수는 지역 건설 수요를 더욱 부추겨, 중형 굴착기에 대한 2차 수요를 창출하고 있습니다.
고액의 초기 설비 투자와 신용 위축
중급급 굴착기의 6자리 수에 달하는 가격과 엄격해진 대출 대비 가치 비율(LTV)이 맞물리면서, 많은 도급업체들은 렌탈에 의존할 수밖에 없는 상황입니다. 금융 완화로 명목 금리는 하락하고 있지만, 담보 요건은 여전히 높아 소규모 건설업체에게는 부담이 되고 있습니다. 리스는 대차대조표 외의 대안을 제공하지만, 실효 금리는 여전히 프로젝트의 미미한 이익률을 압박하고 있습니다. 유동성 상황이 개선될 때까지는 자산을 최소화한 사업 모델이 계속해서 확산될 것이며, 딜러의 수익 구조는 부품 및 서비스 쪽으로 전환될 것입니다.
부문별 분석
2025년, 필리핀의 크롤러식 토공 기계 시장에서 크롤러식 굴착기는 55.12%의 점유율을 차지했습니다. 이는 빈번한 부착물 교체가 필요 없이 굴착, 평탄화, 철거 작업을 수행할 수 있는 능력을 반영한 것입니다. 콤팩트 트랙 로더와 스키드 스티어 로더는 4.93%라는 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 예측됩니다. 이는 좁은 도시 작업 현장에서 설치 면적이 작고 기동성이 뛰어난 기계가 유리하게 작용하기 때문입니다. 건설업체들은 굴착기를 보유 대수를 최소화할 수 있는 다목적 ‘핵심’ 자산으로 중요하게 여기고 있습니다. 퀵 어태치 커플러와의 호환성을 통해 가동 중단 시간이 단축되어 예측 가능한 일일 가동률을 실현하고 있습니다. 따라서 각 OEM 업체들은 디지털 모니터링 및 저배출가스 옵션을 도입할 때 굴착기 업그레이드를 우선시하고 있습니다.
재개발로 인해 혼잡한 비즈니스 지구에서 대형 중장비가 배제되면, 소형 크롤러 로더에 대한 수요가 높아집니다. 렌탈 업체들은 풀사이즈 크롤러를 도입할 공간이 없는 단기 프로젝트를 수주하기 위해 이러한 로더의 재고를 점점 더 늘리고 있습니다. 한편, 교량 기초 공사나 개착식 배수 공사에서는 다른 크롤러형 기계로는 동등한 리치와 안정성을 제공할 수 없기 때문에 굴착기가 여전히 지배적인 위치를 유지하고 있습니다. 딜러들은 플랫폼의 다용도성을 강조하기 위해, 새로운 굴착기 구매시 브레이커나 그래플 등의 부착 장비를 세트로 판매하고 있습니다. 이 두 부문은 필리핀에서의 구매 결정이 단순한 출력만이 아니라 유연성에 의해 좌우되고 있음을 보여줍니다.
2025년 필리핀의 크롤러식 토공 기계 시장에서는 전국적인 디젤 연료 공급망과 정비사의 숙련도를 배경으로, 내연기관식 크롤러가 96.91%라는 압도적인 시장 점유율을 유지했습니다. 전기식 및 하이브리드 모델의 경우, 시행이 임박한 유로 5/V 규제에 앞서 건설업체들이 저배출 대체 기계를 시험적으로 도입하고 있으며, 연평균 성장률(CAGR) 22.02%라는 급속한 성장이 예상됩니다. 외딴 지역의 작업 현장에서도 급유 인프라가 잘 갖춰져 있으며, 차량 관리자들은 여전히 디젤 기계를 선호하고 있습니다. 그러나 하이브리드 구동 시스템은 정지 및 재출발이 잦은 작업 주기에서 실질적인 연료비 절감을 실현하므로 비용을 중시하는 입찰자들의 관심을 끌고 있습니다. 규제가 명확해짐에 따라 미세먼지 배출 제한에 대한 규정 준수상의 불확실성이 완화되어, 하이브리드차량에 호재가 되고 있습니다.
딜러의 서비스 팀은 하이브리드차량의 정비 의뢰가 점차 증가할 것에 대비해 고전압 관련 교육에 투자하고 있습니다. 또한 각 금융 파트너사들도 하이브리드차량에 드는 추가 비용을 장기 계약에 분산시키는 리스 플랜을 수립하고 있습니다. 가동 중단에 따른 페널티가 엄격한 24시간 가동 프로젝트에서는 여전히 디젤 차량이 표준으로 자리 잡고 있습니다. 그럼에도 불구하고 하이브리드차량을 조기에 도입한 기업은 환경 기준을 중시하는 정부 입찰에서 평판상 이점을 얻을 수 있습니다. 시간이 지남에 따라 이러한 간접적인 이점들이 물류 측면에서의 우위에도 불구하고 디젤 차량이 오랫동안 구축해 온 독점적 지위를 서서히 잠식해 나갈 가능성이 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 밸류·공급망 분석
- 규제 상황
- 기술 전망
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 기기 유형별
- 추진력별
- 엔진 출력별
- 용도별
- 유통 채널별
제6장 경쟁 구도
- 시장 집중도
- 전략적 움직임과 제휴
- 시장 점유율 분석
- 기업 개요
- Caterpillar Inc.
- Komatsu Ltd.
- Hitachi Construction Machinery Co., Ltd.
- Volvo Construction Equipment AB
- Liebherr-International AG
- Sumitomo Construction Machinery
- Kobelco Construction Machinery
- SANY Group
- XCMG Group
- HD Hyundai Construction Equipment
- CNH Industrial-CASE CE
제7장 시장 기회와 향후 전망
KSA 26.10.23According to Mordor Intelligence, the Philippines crawler earthmoving machines market size was valued at USD 295.12 million in 2025 and is expected to reach USD 307.57 million in 2026 and USD 378.19 million by 2031, registering a 4.22% CAGR between 2026 and 2031.
Philippines Crawler Earthmoving Machines Market Trends and Insights
Government-backed Build Better More (BBM) Infrastructure Pipeline
Dozens of flagship bridges, expressways, and flood-control assets drive continuous crawler deployment cycles, especially around foundation excavation and embankment works. Multilateral financing cushions domestic budget cuts, but slower disbursement can leave machines idle at partially completed sites, reducing fleet utilization. Rental firms benefit because contractors prefer cost-flexible agreements while awaiting notice-to-proceed milestones. Steady urban migration ensures that secondary-city road upgrades remain on the docket, cementing long-run equipment demand even if mega-projects stagger.
Revival of Large-Scale Mining and Quarrying Projects in Mindanao
The commissioning of a major copper-gold project in Surigao del Norte opened a multi-year crawler-replacement pipeline tied to demanding open-pit cycles. Harsh laterite conditions accelerate undercarriage wear, compelling owners to budget for shorter rebuild intervals. Uncertainties around global nickel pricing heighten procurement caution, yet mandated rehabilitation bonds bind operators to maintaining productive fleets. Provincial road upgrades linked to mine logistics further lift localized construction demand, creating a secondary pull for mid-range excavators.
High Upfront CAPEX and Tightening Credit
6-figure price tags for mid-range excavators collide with stricter loan-to-value ratios, forcing many contractors to turn to rentals. Monetary easing trims headline interest rates, but collateral requirements stay high, challenging small builders. Leasing provides an off-balance-sheet option, though effective rates still erode thin project margins. Until liquidity conditions improve, asset-light operating models continue to gain ground, reshaping dealer revenue toward parts and service.
Other drivers and restraints analyzed in the detailed report include:
- Accelerated Replacement of Aging Crawler Fleets for Safety and Efficiency
- Electrification Incentives and Stage V Emission Mandates
- Raw-Material and Component Supply Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Crawler excavators accounted for 55.12% of the Philippines crawler earthmoving machine market share in 2025, reflecting their ability to handle digging, grading, and demolition without frequent tool changes. Compact tracked loaders and skid-steers are projected to post the fastest 4.93% CAGR because tight urban job sites reward machines with small footprints and high maneuverability. Contractors value excavators as multipurpose "anchor" assets that keep fleet sizes lean. Their compatibility with quick-attach couplers reduces downtime, resulting in predictable daily utilization. OEMs therefore prioritize excavator upgrades when introducing digital monitoring or low-emission options.
Demand for compact tracked loaders rises when redevelopment displaces large equipment from congested business districts. Rental firms increasingly stock these loaders to court short-term projects that lack room for full-sized crawlers. Meanwhile, excavators maintain dominance in bridge foundations and open-cut drainage because no other crawler variant offers comparable reach and stability. Dealers bundle attachments such as breakers and grapples with new excavator purchases to underscore the platform's versatility. Together, the two segments illustrate how flexibility, rather than raw power, shapes procurement choices in the Philippines.
Internal-combustion crawlers retained a commanding 96.91% market share in the Philippines crawler earthmoving machines market in 2025, supported by the nationwide diesel supply chain and mechanics' familiarity. Electric and hybrid models are anticipated to register a rapid 22.02% CAGR as contractors test lower-emission alternatives ahead of the incoming Euro 5/V rules. Fleet managers continue to favor diesel because refueling infrastructure is available even at remote job sites. However, hybrid drivetrains deliver tangible fuel savings during stop-and-go cycles, attracting interest among cost-sensitive bidders. Regulatory clarity gives hybrids an extra push by reducing compliance uncertainty around particulate limits.
Dealer service teams invest in high-voltage training to prepare for a gradual rise in hybrid maintenance calls. Financing partners also craft leasing packages that spread the premium on hybrid units over longer contracts. Diesel platforms remain standard on projects with round-the-clock duty cycles where downtime penalties are steep. Even so, early adopters of hybrids gain reputational benefits in government tenders that score highly on environmental criteria. Over time, those soft advantages may erode diesel's historic lock-in despite its logistical edge.
Complete Report Scope:
- By Equipment Type
- Crawler Excavators
- Crawler Bulldozers
- Crawler Loaders
- Crawler Cranes and Pipe-layers
- Compact Tracked Loaders and Skid-steers
- Others (Trencher, Drill Rig, etc.)
- By Propulsion
- Internal Combustion Engine (ICE)
- Electric and Hybrid
- By Engine Power Output
- Below 100 HP
- 100 to 200 HP
- 201 to 400 HP
- Above 400 HP
- By Application
- Construction
- Mining and Quarrying
- Agriculture and Forestry
- Others
- By Distribution Channel
- Direct OEM Sales
- Authorized Dealers
- Rental and Leasing Firms
List of Companies Covered in this Report:
- Caterpillar Inc.
- Komatsu Ltd.
- Hitachi Construction Machinery Co., Ltd.
- Volvo Construction Equipment AB
- Liebherr-International AG
- Sumitomo Construction Machinery
- Kobelco Construction Machinery
- SANY Group
- XCMG Group
- HD Hyundai Construction Equipment
- CNH Industrial - CASE CE
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government-Backed Build Better More (BBM) Infrastructure Pipeline
- 4.2.2 Revival of Large-Scale Mining and Quarrying Projects in Mindanao
- 4.2.3 Accelerated Replacement of Aging Crawler Fleets for Safety and Efficiency
- 4.2.4 Electrification Incentives and Stage V Emission Mandates
- 4.2.5 Digital Twins and Telematics-Driven OPEX Savings
- 4.2.6 Surge in Deconstruction and Circular-Demolition Projects
- 4.3 Market Restraints
- 4.3.1 High Upfront CAPEX and Tightening Credit
- 4.3.2 Raw-Material and Component Supply Volatility
- 4.3.3 Scarcity of Fast-Charging Infrastructure for Above 20-T Crawlers
- 4.3.4 ESG-Linked Cost of Ownership for Diesel Units
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD) & Volume (Units))
- 5.1 By Equipment Type
- 5.1.1 Crawler Excavators
- 5.1.2 Crawler Bulldozers
- 5.1.3 Crawler Loaders
- 5.1.4 Crawler Cranes and Pipe-layers
- 5.1.5 Compact Tracked Loaders and Skid-steers
- 5.1.6 Others (Trencher, Drill Rig, etc.)
- 5.2 By Propulsion
- 5.2.1 Internal Combustion Engine (ICE)
- 5.2.2 Electric and Hybrid
- 5.3 By Engine Power Output
- 5.3.1 Below 100 HP
- 5.3.2 100 to 200 HP
- 5.3.3 201 to 400 HP
- 5.3.4 Above 400 HP
- 5.4 By Application
- 5.4.1 Construction
- 5.4.2 Mining and Quarrying
- 5.4.3 Agriculture and Forestry
- 5.4.4 Others
- 5.5 By Distribution Channel
- 5.5.1 Direct OEM Sales
- 5.5.2 Authorized Dealers
- 5.5.3 Rental and Leasing Firms
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves & Partnerships
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Caterpillar Inc.
- 6.4.2 Komatsu Ltd.
- 6.4.3 Hitachi Construction Machinery Co., Ltd.
- 6.4.4 Volvo Construction Equipment AB
- 6.4.5 Liebherr-International AG
- 6.4.6 Sumitomo Construction Machinery
- 6.4.7 Kobelco Construction Machinery
- 6.4.8 SANY Group
- 6.4.9 XCMG Group
- 6.4.10 HD Hyundai Construction Equipment
- 6.4.11 CNH Industrial - CASE CE
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


