

|
시장보고서
상품코드
2154484
일회용 정맥내 요법 제품 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Disposable IV Therapy Products - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
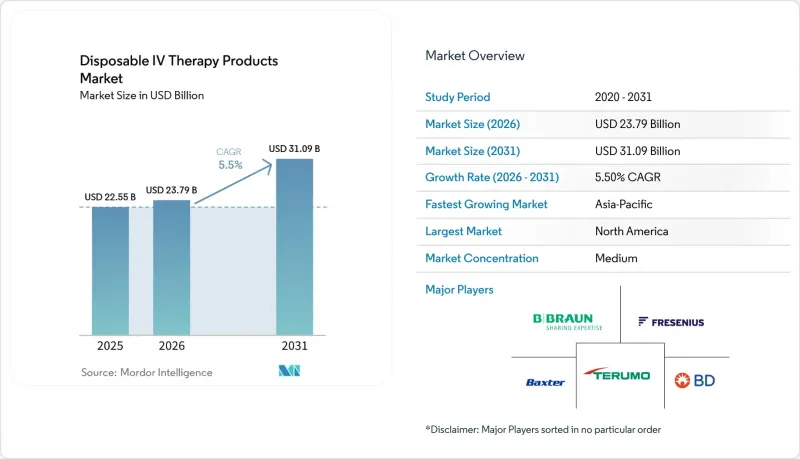
에 따르면 일회용 정맥내 요법 제품 시장 규모는 2025년 225억 5,000만 달러에서 2026년에는 237억 9,000만 달러로 확대되어, 2031년까지 310억 9,000만 달러에 달할 것으로 예상되며, 2026년부터 2031년까지 CAGR 5.5%로 성장할 것으로 전망됩니다.
전 세계 일회용 정맥내 요법 제품 시장의 동향 및 인사이트
정맥내 투여를 통한 약물 및 영양 공급의 이용 확대
정맥내 투여는 즉각적인 투여와 지속적인 투여량 조정이 가능하기 때문에 중증도 높은 약물의 투여에 있어 여전히 필수적입니다. 또한, 다른 투여 경로로는 임상적 요건을 충족할 수 없는 중환자 치료, 종양학, 영양 지원 분야에서도 여전히 매우 중요합니다. 프레제니우스 카비(Fresenius Kabi)는 2025 회계연도에 자사 포트폴리오에 170종 이상의 정맥내 투여용 의약품을 보유하고 있으며, 미국에서 15종의 새로운 정맥내 투여용 의약품을 출시했다고 보고했습니다. 이러한 신제품의 출시는 호환 가능한 투여 세트 및 일회용 정맥내 요법 제품에 대한 수요를 지속적으로 뒷받침하고 있습니다.
만성 질환, 외과 수술 및 중환자 치료 분야의 수요 확대
만성 질환, 외과 수술 및 중환자 치료로 인해 모든 의료 현장에서 정맥 접근에 대한 수요가 지속적으로 증가하고 있습니다. 호주에서는 2024년부터 2025년까지 1,280만 건의 입원과 4,360만 건의 외래 진료가 기록되었습니다. 인도의 ‘AB PM-JAY’ 제도에서는 2026년 2월까지 1,961종류의 시술에 걸친 11.69 crore건의 입원이 승인되었습니다. 화학요법, 투석, 점적 이뇨 요법 등 치료 기간이 장기화되는 경향이 카테터, 커넥터, 투여 세트의 수요를 뒷받침하고 있습니다.
입찰 및 수량 기반 조달에 따른 가격 압박
공동 구매 조직 및 공공 입찰로 인해 정맥내 투여용 소모품에는 지속적인 가격 압박이 가해지고 있습니다. 중국에서는 수량 기반 조달이 의료기기 분야로도 확대되면서, 표준적인 정맥내 요법 제품에 대한 가격 기대치가 형성되고 있습니다. 비용 구조가 높은 다국적 기업에 비해, 국내 공급업체는 이러한 기대치에 더 쉽게 부응할 수 있는 경우가 많습니다. 범용 투여 세트나 기본적인 말초 카테터는 가장 직접적인 압박에 직면해 있지만, 각 제조사는 제품의 차별화를 꾀하기 위해 항균 코팅, 폐쇄형 시스템, 연결 기능 등에 투자하고 있습니다. 또한, 병원의 결제 주기가 장기화되고 있는 점도 일회용 정맥내 요법 제품 시장 전체에 걸쳐 운전 자금에 대한 압박을 가중시키고 있습니다.
부문 분석
2025년, IV 카테터 및 캐뉼라는 일회용 IV 요법 제품 시장 규모의 45.67%를 차지하며, 급성기 의료 현장에서 말초 정맥 접근에 대한 수요가 널리 존재함을 반영하고 있습니다. 2026년 4월, BD사는 FDA의 510(k) 승인을 획득하고, FDA의 의료기기용 ‘Safer Technologies Program(더 안전한 기술 프로그램)’에 선정된 후 ‘BD CentroVena One’ 삽입 시스템을 출시했습니다. 이 시스템을 통해 삽입 절차가 30% 단축되었으며, 시뮬레이션상 삽입 시간도 50% 단축되었습니다. 또한, BD사는 ‘Insyte IV 카테터’에 대해서도 FDA의 510(k) 승인을 획득하여, 업무 흐름의 효율화와 삽입 시 안전성을 높이고 있습니다.
수액 펌프 시장은 2031년까지 연평균 성장률(CAGR) 7.76%로 성장할 것으로 예측되며, 이는 제품 유형 중 가장 높은 성장률입니다. 펌프의 교체 주기로 인해 호환 가능한 투여 세트 및 연장 세트에 대한 지속적인 수요가 발생하고 있습니다. 한편, 무바늘 커넥터와 소독용 캡은 빈번한 교체가 필요합니다. 2025년, B. Braun사는 106개 병원이 자사의 ‘Introcan Safety’ 카테터 시리즈로 전환했으며, 3만 1,000명 이상의 임상의에게 교육을 실시했다고 보고했습니다. 재택 및 외래 치료 프로토콜이 복잡해짐에 따라 특수 접근 세트, 안티사이폰 연장 세트 및 유량 조절용 액세서리의 중요성이 높아지고 있습니다.
2025년에는 일회용 및 단일 사용 제품이 매출의 76.55%를 차지할 것으로 예상되며, 2031년까지 연평균 성장률(CAGR) 8.20%로 성장할 것으로 전망됩니다. 의료 서비스 제공자들이 전문적인 용도나 신흥 시장에서 재사용 가능한 제품에서 벗어나면서, 이 카테고리는 계속해서 가장 크고 가장 빠르게 성장하는 사용성 부문으로 자리매김하고 있습니다. 감염 예방은 세척 및 재처리 요건을 제거함으로써 이러한 전환을 뒷받침하고 있습니다. 2025년에 발표된 동료 심사 논문을 통해 카테터 관련 감염 예방과 카테터 관련 합병증이 초래하는 임상적 영향이 강조되었습니다.
2026년 7월 22일, 니프로는 ‘ORCHID IV’ 라인 커넥터의 일본 내 판매를 시작했습니다. 이 커넥터는 튜브에 과도한 인장력이 가해질 때 안전하게 분리되므로, 간호 현장에서의 의도치 않은 튜브 탈락이나 피부 손상을 줄이고, 신체 구속 사용을 감소시킵니다. 재사용 가능한 제품은 충분한 멸균 인프라가 갖춰진 곳이나 비용 제약이 있는 곳에서는 여전히 중요성을 유지하고 있습니다. 그러나 일회용 제품의 비용 하락과 일관된 감염 관리 대책에 대한 집중으로 인해 일회용 제품에 대한 수요는 계속해서 증가하고 있습니다.
지역별 분석
북미는 2025년 매출 점유율의 40.56%를 차지했으며, 견고한 급성기 의료 인프라, 높은 시술 건수, 그리고 안전성을 중시하는 정맥내 투여용 소모품의 정착에 힘입었습니다. 2026년 1월 14일, 캐나다 보건부는 ICU Medical사의 ‘Plum Solo’ 및 ‘Plum Duo’ 정밀 주입 펌프를 승인하여 캐나다 의료 기관에서의 사용 기회를 확대했습니다. 외래 및 재택 치료로의 전환에 따라, 적절한 사용 편의성과 펌프와의 호환성을 갖춘 전문 소모품에 대한 수요가 증가하고 있습니다.
유럽은 독일, 영국, 프랑스를 필두로 계속해서 2위 지역 시장을 차지했습니다. 2025년 9월, 프레제니우스 카비(Fresenius Kabi)는 의료 제품 및 바이오시밀러의 생산능력을 확대하기 위해 유럽투자은행으로부터 4억 유로의 자금을 확보했습니다. 이 자금은 투여 세트 및 수액 시스템의 생산능력 강화에 사용된 한편, ‘의료기기 규정(MDR)’ 및 DEHP의 단계적 폐지에 따라 PVC에 의존하는 제품 포트폴리오의 재편이 지속적으로 진행되었습니다. 아시아태평양은 2031년까지 연평균 성장률(CAGR) 7.77%로 성장할 것으로 예측됩니다. 이는 2026년 2월까지 1,961건의 수술과 11.69 crore건의 입원을 승인한 인도의 ‘AB PM-JAY’ 프로그램에 힘입은 결과입니다.
중국은 T/CAMDI 154-2025를 통해 일회용 중력식 수액 세트의 기준을 강화하고, GB 8368의 틀 및 ISO 8536-4를 준수하도록 했습니다. BD사는 2025년 12월, 인도네시아에서 ‘Nexiva Closed IV Catheter System’을 출시했습니다. 중동 및 아프리카에서는 GCC 국가들이 3차 의료 시설을 확충함에 따라 낮은 수준에서 시장이 확대되었습니다. 한편, 남미에서는 브라질이나 아르헨티나와 같은 대규모 병원 시장과 그 외 가격 제약이 있는 시장 간에 양극화가 지속되었습니다. 2025년, 박스터(Baxter)사와 호주 정부는 시드니 서부 올드 퉁가비(Old Tungabee)에서 정맥 주사용 수액 생산 확대를 위해 4,000만 호주 달러(2,580만 달러 상당)의 공동 투자를 발표했습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
- 조사 가정과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 가치 및 공급망 분석
- 규제 상황
- 기술 전망
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 제품 유형별
- 사용성별
- 용도별
- 최종사용자별
- 지역별
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 스페인
- 기타 유럽 국가
- 아시아태평양
- 중국
- 인도
- 일본
- 호주
- 한국
- 기타 아시아태평양 국가
- 중동 및 아프리카
- GCC
- 남아프리카공화국
- 기타 중동 및 아프리카 국가
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 북미
제6장 경쟁 구도
- 시장 집중도
- 시장 점유율 분석
- 기업 개요
- AngioDynamics, Inc.
- B. Braun Melsungen SE
- Baxter International Inc.
- Becton, Dickinson and Company
- Cardinal Health, Inc.
- CODAN Medizinische Gerate GmbH
- ConvaTec Group Plc
- Edwards Lifesciences Corporation
- Fresenius SE & Co. KGaA
- ICU Medical, Inc.
- JMS Co., Ltd.
- KORU Medical Systems, Inc.
- Lepu Medical Technology(Beijing) Co., Ltd.
- Merit Medical Systems, Inc.
- Nipro Corporation
- Poly Medicure Limited
- Smiths Group plc
- Teleflex Incorporated
- Terumo Corporation
- Vygon SA
- WEGO Holding Company Limited
- Zhejiang Kindly Medical Devices Co., Ltd.
제7장 시장 기회와 향후 전망
KSM 26.10.29According to Mordor Intelligence, the disposable IV therapy products market size is expected to increase from USD 22.55 billion in 2025 to USD 23.79 billion in 2026 and reach USD 31.09 billion by 2031, growing at a CAGR of 5.5% over 2026-2031.
Global Disposable IV Therapy Products Market Trends and Insights
Rising Intravenous Medication and Nutrition Utilization
Intravenous administration remains essential for high-acuity medications, as it enables immediate delivery and continuous dose adjustment. It remains critical in intensive care, oncology, and nutritional support, where alternative routes may not meet clinical requirements. Fresenius Kabi reported more than 170 IV drug products in its portfolio and 15 new U.S. IV drug launches during fiscal year 2025. These launches continue to support demand for compatible administration sets and disposable IV therapy products.
Growth in Chronic Disease, Surgery, and Critical Care
Chronic diseases, surgical procedures, and critical care continue to increase the need for IV access across care settings. Australia recorded 12.8 million hospitalizations and 43.6 million outpatient services in 2024-2025. India's AB PM-JAY scheme had authorized 11.69 crore hospital admissions across 1,961 procedures by February 2026. Longer treatment cycles, including chemotherapy, dialysis, and IV diuretic therapy, support demand for catheters, connectors, and administration sets.
Pricing Pressure From Tendering and Volume-Based Procurement
Group purchasing organizations and public tenders place persistent pricing pressure on IV consumables. In China, volume-based procurement has extended to medical devices and sets price expectations for standard IV products. Domestic suppliers can often meet these expectations more easily than multinationals with higher cost structures. Commodity administration sets and basic peripheral catheters face the most direct pressure, while manufacturers are investing in antimicrobial coatings, closed systems, and connectivity features to support product differentiation. Longer hospital payment cycles also increase working capital pressure across the disposable IV therapy products market.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Home and Ambulatory Infusion Care
- Needleless Access and Infection Prevention Requirements
- Transition Risk From PVC, DEHP, and Other Material Restrictions
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
IV catheters and cannulas accounted for 45.67% of the disposable IV therapy products market size in 2025, reflecting the widespread need for peripheral IV access in acute-care settings. In April 2026, BD launched the BD CentroVena One Insertion System following FDA 510(k) clearance and acceptance into the FDA Safer Technologies Program for Medical Devices. The system reduced insertion steps by 30% and simulation insertion time by 50%. BD also received FDA 510(k) clearance for its Insyte IV Catheter, supporting workflow efficiency and insertion safety.
Infusion pumps are forecast to grow at a 7.76% CAGR through 2031, the highest rate among product types. Pump replacement cycles drive recurring demand for compatible administration and extension sets, while needleless connectors and disinfection caps require frequent replacement. In 2025, B. Braun reported that 106 hospitals converted to its Introcan Safety catheter family and that it trained more than 31,000 clinicians. Specialty access sets, anti-siphon extension sets, and flow-regulation accessories are gaining relevance as home and ambulatory therapy protocols become more complex.
Disposable and single-use products held 76.55% of revenue in 2025 and are forecast to grow at an 8.20% CAGR through 2031. This category remains the largest and fastest-growing usability segment as providers move away from reusable products in specialty applications and emerging markets. Infection prevention supports this shift by eliminating cleaning and reprocessing requirements. A 2025 peer-reviewed review highlighted catheter-related infection prevention and the clinical consequences of catheter-related complications.
On July 22, 2026, Nipro began domestic sales of its ORCHID IV line connector in Japan. The connector disconnects safely when tubing is exposed to excessive pulling force, reducing accidental extubation and skin damage in nursing settings with reduced use of physical restraints. Reusable products retain relevance in cost-constrained locations with adequate sterilization infrastructure. However, declining single-use product costs and the focus on consistent infection-control practices continue to strengthen demand for disposable products.
Complete Report Scope:
- By Product Type
- IV Catheters and Cannulas
- IV Administration Sets
- Extension Sets and Accessories
- Infusion Pump
- Needleless Connectors and Disinfection Caps
- Others
- By Usability
- Disposable/Single-use
- Reusable
- By Application
- Fluid Replacement & Hydration
- Medication Administration
- Parenteral Nutrition
- Blood & Blood Product Administration
- Chemotherapy
- Antibiotic Administration
- Pain Management
- Dialysis and Renal Care
- Home and Specialty Infusion
- Others
- By End User
- Hospitals
- Specialty Clinics
- Ambulatory Surgical Centers
- Home Healthcare
- Long-term Care Facilities
- Other Healthcare Facilities
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held a 40.56% revenue share in 2025, supported by robust acute-care infrastructure, high procedure volumes, and established adoption of safety-oriented IV consumables. On January 14, 2026, Health Canada cleared ICU Medical's Plum Solo and Plum Duo precision IV pumps, expanding access for Canadian healthcare organizations. The shift toward ambulatory and home-based care is increasing demand for specialized consumables with appropriate usability and pump compatibility.
Europe remained the second-largest regional market, led by Germany, the United Kingdom, and France. In September 2025, Fresenius Kabi secured a EUR 400 million loan from the European Investment Bank to expand medical product and biosimilar manufacturing capacity. The funding supported administration-set and infusion-system capacity, while the Medical Device Regulation and the DEHP sunset continued to reshape PVC-dependent portfolios. Asia-Pacific is forecast to grow at a 7.77% CAGR through 2031, supported by India's AB PM-JAY program, which had authorized 11.69 crore admissions across 1,961 procedures by February 2026.
China strengthened standards for single-use gravity-feed infusion sets through T/CAMDI 154-2025, aligning with the GB 8368 framework and ISO 8536-4. BD launched its Nexiva Closed IV Catheter System in Indonesia in December 2025. The Middle East and Africa expanded from a lower base as GCC countries developed tertiary-care facilities, while South America remained divided between larger hospital markets in Brazil and Argentina and price-constrained markets elsewhere. In 2025, Baxter and the Australian Government announced a AUD 40 million joint investment, equivalent to USD 25.8 million, to expand IV fluid manufacturing in Old Toongabbie, Western Sydney.
- AngioDynamics
- B. Braun Melsungen SE
- Baxter
- Beckton Dickinson
- Cardinal Health
- CODAN Medizinische Gerate GmbH
- Convatec
- Edward Lifesciences
- Fresenius
- ICU Medical
- JMS Co., Ltd.
- KORU Medical Systems, Inc.
- Lepu Medical Technology (Beijing) Co., Ltd.
- Merit Medical Systems
- Nipro
- Poly Medicure
- Smiths Group
- Teleflex
- Terumo
- Vygon
- WEGO Holding Company Limited
- Zhejiang Kindly Medical Devices Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Intravenous Medication and Nutrition Utilization
- 4.2.2 Growth in Chronic Disease, Surgery and Critical Care
- 4.2.3 Expansion of Home and Ambulatory Infusion Care
- 4.2.4 Dedicated-Set Pull-Through From Installed Infusion Pumps
- 4.2.5 Needleless Access and Infection-Prevention Requirements
- 4.2.6 Closed-Loop Traceability of Set, Drug and Patient Identity
- 4.3 Market Restraints
- 4.3.1 Pricing Pressure From Tendering and Volume-Based Procurement
- 4.3.2 Material, Sterility and Chemical-Compatibility Qualification Burden
- 4.3.3 Transition Risk From PVC, DEHP and Other Material Restrictions
- 4.3.4 Procedure-Volume Volatility and Hospital Inventory Destocking
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Rivalry Among Existing Competitors
5 MARKET SIZE AND GROWTH FORECASTS (VALUE, USD)
- 5.1 By Product Type
- 5.1.1 IV Catheters and Cannulas
- 5.1.2 IV Administration Sets
- 5.1.3 Extension Sets and Accessories
- 5.1.4 Infusion Pump
- 5.1.5 Needleless Connectors and Disinfection Caps
- 5.1.6 Others
- 5.2 By Usability
- 5.2.1 Disposable/Single-use
- 5.2.2 Reusable
- 5.3 By Application
- 5.3.1 Fluid Replacement & Hydration
- 5.3.2 Medication Administration
- 5.3.3 Parenteral Nutrition
- 5.3.4 Blood & Blood Product Administration
- 5.3.5 Chemotherapy
- 5.3.6 Antibiotic Administration
- 5.3.7 Pain Management
- 5.3.8 Dialysis and Renal Care
- 5.3.9 Home and Specialty Infusion
- 5.3.10 Others
- 5.4 By End User
- 5.4.1 Hospitals
- 5.4.2 Specialty Clinics
- 5.4.3 Ambulatory Surgical Centers
- 5.4.4 Home Healthcare
- 5.4.5 Long-term Care Facilities
- 5.4.6 Other Healthcare Facilities
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 AngioDynamics, Inc.
- 6.3.2 B. Braun Melsungen SE
- 6.3.3 Baxter International Inc.
- 6.3.4 Becton, Dickinson and Company
- 6.3.5 Cardinal Health, Inc.
- 6.3.6 CODAN Medizinische Gerate GmbH
- 6.3.7 ConvaTec Group Plc
- 6.3.8 Edwards Lifesciences Corporation
- 6.3.9 Fresenius SE & Co. KGaA
- 6.3.10 ICU Medical, Inc.
- 6.3.11 JMS Co., Ltd.
- 6.3.12 KORU Medical Systems, Inc.
- 6.3.13 Lepu Medical Technology (Beijing) Co., Ltd.
- 6.3.14 Merit Medical Systems, Inc.
- 6.3.15 Nipro Corporation
- 6.3.16 Poly Medicure Limited
- 6.3.17 Smiths Group plc
- 6.3.18 Teleflex Incorporated
- 6.3.19 Terumo Corporation
- 6.3.20 Vygon SA
- 6.3.21 WEGO Holding Company Limited
- 6.3.22 Zhejiang Kindly Medical Devices Co., Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


