

|
시장보고서
상품코드
2154811
수소 엔진용 인젝터 스프링 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Injector Springs For Hydrogen Engine - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
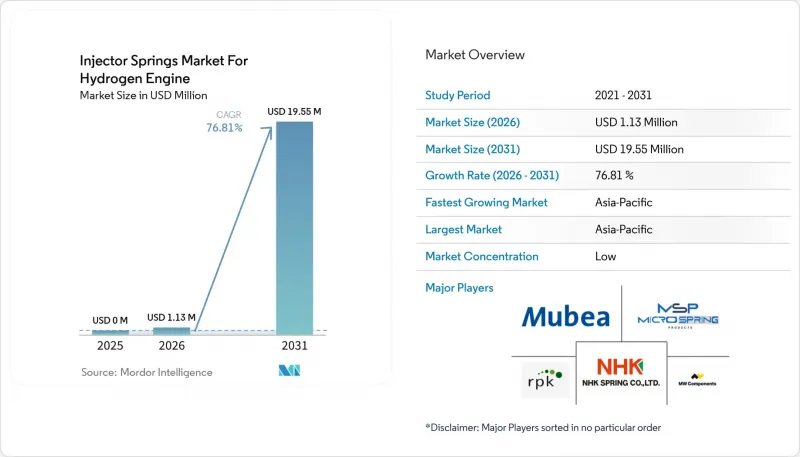
에 따르면 수소 엔진용 인젝터 스프링 시장 규모는 2026년에 113만 달러가 될 것으로 예측되며, 2031년까지 1,955만 달러에 달하고, 2026년부터 2031년까지 CAGR 76.81%로 성장할 것으로 전망됩니다.
수소 엔진용 인젝터 스프링 시장의 동향 및 전망
수소 연소 차량의 확대와 인증 수주
수소 엔진용 인젝터 스프링 시장은 보조금을 통한 실증 실험에서 일상적인 상업 운영으로의 전환에 힘입어 성장하고 있습니다. IAV사와 DEUTZ사는 2026년 3월, 공도 주행 승인을 받은 18톤 트럭 2대를 DEUTZ사 및 BMW사의 시설 내 물류 업무에 투입했습니다. 사우스웨스트 연구소는 2026년 8월, 디젤 차량과 동등한 토크를 가진 스파크 점화식 중형 수소 엔진의 개발을 완료했습니다. 이러한 진전에 따라 인젝터 부품은 현재 진행 중인 차량 개발 프로그램에 통합되게 되었습니다. 스프링 공급업체는 차량 도입 규모가 확대되기 전에 인증 프로그램에 참여해야 합니다. 인젝터의 내구성 검증에는 양산 조달이 시작되기까지 12-18개월이 소요될 수 있습니다. 따라서 수소 엔진용 인젝터 스프링 시장에서는 차량 교체 주기가 본격화되기 전에 인증 관련 수주를 확보할 가능성이 있습니다.
고압 직접 분사로 인해 인젝터 스프링에 가해지는 부하가 증가
수소 직접 분사 시스템은 분사 전략에 따라 30-200 bar의 압력 하에서 작동합니다. 압력이 높아지면 연소 제어 성능은 향상되지만, 동시에 인젝터의 리턴 스프링에 가해지는 기계적 부하도 증가합니다. 2025년에 실시된 캠 구동식 외향형 수소 인젝터에 관한 연구에 따르면, 160-200 N/mm의 강성과 560-600 N의 예압이 밸브 리프트의 거동을 결정하는 것으로 밝혀졌습니다. 이 조사에서는 분사량 편차의 5.4%가 스프링의 강성에, 30%가 예압에 기인하는 것으로 나타났습니다. 수소 엔진용 인젝터 스프링 시장에서 공차 관리는 단순한 부품의 2차적 특성이 아니라, 연료 계량 성능의 일부가 되었습니다. 또한, 레일 압력의 향상과 함께 재료의 순도, 표면 처리 및 피로 검증의 중요성도 높아지고 있습니다.
상용 엔진의 생산 대수가 제한적이기 때문에 교체 수요의 확대가 더딘 상황입니다.
수소 엔진용 인젝터 스프링 시장은 2025년 시점에서 사실상 제로에서 시작되므로, 그 전망은 차량 도입 일정에 크게 좌우되는 상황입니다. 단기적인 수요의 대부분은 교체용 부품이 아니라, 프로토타입 및 인증 시험용 수주에 의한 것입니다. 수소 트럭 프로그램은 실제 운행 단계에 접어들기 시작했지만, 광범위한 차량 도입은 아직 발전 단계에 있습니다. IAV사와 DEUTZ사가 2026년 3월에 납품한 사례는 수소 연소 트럭이 독일에서 일상적인 물류 서비스에 도입되었음을 보여줍니다. 볼보는 2030년까지 유럽에서 수소 연소 트럭의 상용화를 시작할 계획입니다. 인젝터는 교체까지 긴 점검 주기를 거쳐야 하기 때문에 교체용 부품 수요는 OEM 수요보다 뒤처지게 됩니다. 또한, 차량 함대의 연료비와 급유 편의성도 시제품 단계의 활동이 지속적인 부품 수요로 발전할지 여부를 좌우하는 요인이 됩니다.
부문 분석
다층 스프링은 2031년까지 연평균 성장률(CAGR)이 89.7%로, 유형별 부문 중 가장 빠른 성장세를 기록하고 있습니다. 제한된 축방향 공간 내에서 강성을 조절할 수 있다는 특성은 바깥쪽으로 열리는 방식의 수소 인젝터에 적합합니다. 수소 엔진용 인젝터 스프링 시장에서는 레일 압력이나 배압을 이겨내고 니들 리프트를 확보할 수 있는 설계가 요구됩니다. 2025년 인젝터 조사에 따르면, 강성과 예압의 조합이 분사량의 변동에 영향을 미치는 것으로 나타났습니다. 이러한 관계로 인해 재현성 있는 형상 제어와 힘 제어가 중요한 선정 기준이 됩니다. 다층 구조 설계는 첨단 인젝터 본체의 패키징 제약을 해결할 수 있습니다. 또한 제조사 입장에서는 인젝터의 패키지 크기를 확대하지 않고도 힘 응답을 최적화할 수 있는 수단이 됩니다.
코일 스프링은 포트 분사 시스템이나 저부하 수소 응용 분야에서 여전히 기존의 선택지로 남아 있습니다. 레일 압력이 디젤 엔진에서 유래한 검증된 한계값 범위 내에 머무르는 경우, 코일 스프링은 계속해서 유용합니다. 벨빌 스프링과 디스크 스프링은 인젝터 본체 어셈블리 내의 밀봉 및 예압 등 서로 다른 역할을 수행합니다. 디스크 스프링은 컴팩트한 치수와 높은 강성을 겸비하고 있어 전해조나 고정형 연료전지 스택 어셈블리에도 사용되고 있습니다. 수소 엔진용 인젝터 스프링 업계는 공급업체들이 여러 관련 용도를 다루고 있기 때문에 이러한 폭넓은 수소 장비 경험을 활용할 수 있을 것입니다. 스프링 선정은 앞으로도 분사 압력, 설치 공간 및 요구되는 작동 수명에 따라 결정될 것입니다.
니켈 합금은 2031년까지 연평균 성장률(CAGR)이 88.3%에 달해 가장 빠르게 성장하고 있는 소재 부문입니다. 고압 직접 분사 방식에서는 기존의 비용 우선적 사고방식보다 소재의 신뢰성이 중시되기 때문에 니켈 합금을 사용한 수소 엔진용 인젝터 스프링의 시장 규모는 확대되고 있습니다. 표준 스프링용 강은 지속적인 응력과 수소 분압이 동시에 발생하면 취화 위험에 직면할 가능성이 있습니다. 2025년 시험에서 인코넬 718은 화염 충진 상태에서 수소와 관련된 균열 및 공극 형성이 관찰되었습니다. 이 사실은 인장 강도나 내식성만으로는 수소 인젝터에 대한 사용 적합성을 확립할 수 없는 이유를 보여줍니다. 재료 선정 시에는 수소 확산, 반복 하중 및 실제 작동 조건을 반영해야 합니다. 따라서 니켈 합금의 사양은 요구 사항이 까다로운 인젝터 프로그램에서 필수적인 인증 요건이 될 수 있습니다.
스테인리스강은 저응력 구조나 포트 분사 설계에서 여전히 중요한 역할을 하고 있습니다. 그러나 인젝터 내부의 응력이나 수소 노출이 증가함에 따라 그 적합성은 떨어집니다. 석출 경화강은 성능과 비용의 균형이 요구되는 고온 환경의 스프링 용도에서 타협점이 될 수 있습니다. 첨단 복합재료 및 하이브리드 재료는 비자성 또는 경량화가 요구되는 용도에서 여전히 초기 단계의 선택지에 머물러 있습니다. 이러한 대체 재료가 인젝터의 중요한 동적 기능을 뒷받침하기 위해서는 추가적인 실제 운용 실적이 필요합니다. 스프링 재료 규격에 대한 인증 획득은 현재 기존 연료 시스템에 부품을 공급하고 있는 공급업체들에게 시장 진입 장벽을 높일 가능성이 있습니다. 가장 우수한 재료 프로그램은 실험실 검증 결과와 부품 수준의 내구성 시험을 결합한 형태가 될 것입니다.
지역별 분석
북미는 수소 엔진용 인젝터 스프링 시장에 있어 중요한 연구 거점입니다. 사우스웨스트 리서치 인스티튜트(Southwest Research Institute)는 2026년 8월, 디젤 차량과 동등한 토크를 발휘하는 중형 스파크 점화식 수소 엔진 개발을 완료했습니다. 이 프로그램은 미국 상용차에서 수소 연소 기술의 기술적 실현 가능성을 입증하는 것입니다. 또한, 토요타 하이드로젠 솔루션즈(Toyota Hydrogen Solutions)는 2026년 4월, 1MW 발전기를 지원할 수 있는 상용 고정형 유닛에 대한 연료전지 인증을 획득했습니다. 캐나다와 멕시코는 미국의 엔진 및 스프링 제조업체와의 공급망을 통해 시장에 진입할 수 있습니다. 단기적인 부품 수주는 개발 프로그램이 실제 차량 도입 단계로 넘어갈지 여부에 따라 좌우될 것입니다.
수소 엔진용 인젝터 스프링 시장에서 유럽은 가장 활발한 규제 환경을 갖추고 있습니다. 유로 7은 2028년 5월 이후의 신형 대형 차량 모델에 적용되며, 수명 연장에 따른 배기가스 성능 요건을 규정하고 있습니다. IAV와 DEUTZ는 2026년 3월부터 독일에서 수소 트럭을 활용한 일상적인 물류 업무를 시작했습니다. 다임러 트럭과 KEYOU는 HICE.40을 2027년 유럽에서 출시하는 것을 목표로 하고 있습니다. 볼보 트럭은 도로 시험을 시작했으며, 2030년 이전에 상용화를 실현할 계획입니다. 이 지역에서는 실증 차량부터 플랫폼 승인에 이르기까지, 공급업체를 대상으로 명확하면서도 엄격한 로드맵이 제시되고 있습니다.
아시아태평양은 2031년까지의 연평균 성장률(CAGR)이 99.2%로, 지역별로는 가장 빠른 성장세를 기록하고 있습니다. 일본의 수소 관련 프로그램은 운송 및 선박 용도에 걸친 하드웨어 개발을 지원하고 있습니다. 2025년 육상 및 선박용 수소 엔진 운용에는 가와사키 중공업, 얀마 파워 솔루션즈, 일본 엔진 주식회사가 참여했습니다. 중국이 내세운 “2030년까지 신에너지 대형 트럭 보급률을 40%로 끌어올리겠다”는 정책 목표는 부품 공급업체에게 시장 기회를 확대하고 있습니다. 인도의 수소 현지화 노력은 국내 엔진 및 정밀 부품 생산에 새로운 기회를 가져올 가능성이 있습니다. 남미, 중동 및 아프리카는 예측 기간 동안 여전히 초기 단계의 시장에 머물러 있습니다. 이 지역들의 장기적인 잠재력은 수소 인프라와 상용차 도입 상황에 좌우될 것입니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
- 조사 가정과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 공급망 분석
- Porter's Five Forces 분석
- 기술 동향
- 규제 상황
- 투자 분석
제5장 시장 규모와 성장 예측
- 유형별
- 소재별
- 코팅/표면 처리별
- 용도별
- 최종사용자별
- 지역별
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 영국
- 독일
- 프랑스
- 스페인
- 북유럽 국가
- 러시아
- 기타 유럽 국가
- 아시아태평양
- 중국
- 인도
- 일본
- 한국
- ASEAN 국가
- 기타 아시아태평양 국가
- 남미
- 브라질
- 아르헨티나
- 콜롬비아
- 기타 남미 국가
- 중동 및 아프리카
- 아랍에미리트
- 사우디아라비아
- 남아프리카공화국
- 이집트
- 기타 중동 및 아프리카 국가
- 북미
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- Barnes Group Inc.
- Lee Spring
- Microspring Products
- Mubea
- MW Components
- NHK Spring Co., Ltd.
- RPK, S. Coop.
- SCHERDEL GmbH
제7장 시장 기회와 향후 전망
KSM 26.10.29According to Mordor Intelligence, the injector springs market for hydrogen engine industry size is projected to be USD 1.13 million in 2026, and reach USD 19.55 million by 2031, growing at a CAGR of 76.81% from 2026 to 2031.
Insights and Trends of Injector Springs Market For Hydrogen Engine
Expansion of Hydrogen Combustion Fleets and Qualification Orders
The hydrogen engine injector springs market is supported by the transition from funded demonstrations to daily commercial operations. IAV and DEUTZ placed 2 road-approved 18-ton trucks into logistics work at DEUTZ and BMW facilities in March 2026. Southwest Research Institute completed development of a spark-ignited, medium-duty hydrogen engine with diesel-equivalent torque in August 2026. These developments place injector components within active vehicle development programs. Spring suppliers must enter qualification programs before fleet deployment reaches scale. Injector durability validation can require 12 to 18 months before series procurement. The hydrogen engine injector springs market can therefore receive qualification orders before fleets create a meaningful replacement cycle.
High-Pressure Direct Injection Raises Injector Spring Duty
Hydrogen direct-injection systems operate at 30 to 200 bar, depending on the injection strategy. Higher pressure can improve combustion control, but it also increases the mechanical demands placed on the injector return spring. A 2025 study of cam-driven outward-opening hydrogen injectors found that stiffness of 160 to 200 N/mm and preload of 560 to 600 N govern valve-lift behavior. The study attributed 5.4% of injection quantity variation to spring stiffness and 30% to preload force. In the hydrogen engine injector springs market, tolerance control becomes part of fuel-metering performance rather than a secondary component attribute. Higher rail pressures also raise the importance of material purity, surface treatment, and fatigue validation.
Limited Commercial Engine Volume Delays Replacement Demand
The hydrogen engine injector springs market begins from an effectively zero 2025 base, which makes its forecast sensitive to fleet deployment schedules. Most near-term demand comes from prototypes and qualification orders instead of replacement components. Hydrogen truck programs are beginning to enter road use, but broad fleet adoption is still developing. IAV and DEUTZ's March 2026 delivery shows that hydrogen combustion trucks have entered daily logistics service in Germany. Volvo plans a commercial European launch for its hydrogen combustion trucks before 2030. Replacement demand will lag original equipment demand because injectors must complete long service intervals before being replaced. Fleet fuel costs and refueling availability can also determine whether prototype activity becomes recurring component volume.
Other drivers and restraints analyzed in the detailed report include:
- Hydrogen-Compatible Materials and Production Reuse Improve Readiness
- Asian Localization Broadens the Supply Base
- Hydrogen Exposure and Validation Costs Limit Qualification Speed
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Multi-layer springs record the fastest growth within the type segment at an 89.7% CAGR through 2031. Their ability to provide tunable stiffness within a limited axial space suits outward-opening hydrogen injectors. The hydrogen engine injector springs market requires designs that counter needle lift against rail pressure and back pressure. The 2025 injector study showed that stiffness and preload together influence injection quantity variation. This relationship makes repeatable geometry and force control important selection criteria. Multi-layer designs can address the packaging limits of advanced injector bodies. They also give manufacturers a route to tailor force response without enlarging the injector package.
Coil springs remain the conventional choice for port-injection systems and lower-duty hydrogen applications. They can retain relevance where rail pressures remain within validated diesel-derived limits. Belleville and disc springs serve different roles, including sealing and preload within injector body assemblies. Disc springs are also used in electrolyzers and stationary fuel-cell stack assemblies because they combine compact dimensions with high stiffness. The hydrogen engine injector springs industry can draw on this wider hydrogen equipment experience as suppliers serve several related applications. Type selection will remain linked to injection pressure, available space, and the required actuation life.
Nickel alloys are the fastest-growing material segment at an 88.3% CAGR through 2031. The hydrogen engine injector springs market size for nickel-alloy applications is expanding because high-pressure direct injection places material reliability ahead of conventional cost priorities. Standard spring steels can face embrittlement risk when sustained stress and hydrogen partial pressure occur together. Inconel 718 showed hydrogen-related cracking and void formation under flame charging in 2025 testing. This evidence shows why tensile strength and corrosion resistance alone cannot establish fitness for hydrogen injector use. Material choice must reflect hydrogen diffusion, cyclic loading, and real operating conditions. Nickel-alloy specifications can therefore become a necessary qualification requirement for demanding injector programs.
Stainless steel retains a role in lower-stress configurations and port-injection designs. Its suitability declines as stress and hydrogen exposure rise within the injector. Precipitation-hardening steels can provide a middle ground for elevated-temperature spring duties where a different balance of performance and cost is needed. Advanced composites and hybrid materials remain early-stage options for nonmagnetic or weight-sensitive applications. Greater field history will be needed before these alternatives can support critical dynamic injector functions. Certification to spring-material standards can raise the entry threshold for suppliers that currently serve conventional fuel systems. The strongest material programs will combine laboratory evidence with component-level durability testing.
Complete Report Scope:
- By Type
- Coil Springs
- Belleville / Disc Springs
- Multi-layer Springs
- By Material
- Stainless Steel
- Nickel Alloys
- Precipitation Hardening Steels
- Advanced Composites & Hybrids
- By Coating/Surface Treatment
- PVD/CVD Hard Coatings
- Nitriding & Nitrocarburizing
- Ceramic & DLC Coatings
- Shot Peening & Residual Stress Treatments
- By Application
- On-road Hydrogen Engines
- Off-road Hydrogen Engines
- Stationary Hydrogen Power Systems
- By End-user
- Automotive OEMs
- Heavy-duty Engine Manufacturers
- Industrial Engine OEMs
- Hydrogen Power System Integrators
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Spain
- Nordic Countries
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Egypt
- Rest of Middle East and Africa
- North America
Geography Analysis
North America is an important research base for the hydrogen engine injector springs market. Southwest Research Institute completed a medium-duty spark-ignited hydrogen engine with diesel-equivalent torque in August 2026. The program validates the technical path for hydrogen combustion in U.S. commercial vehicles. Toyota Hydrogen Solutions also achieved fuel-cell certifications for commercial stationary units that can support 1 MW generators in April 2026. Canada and Mexico can participate through supply-chain links with U.S. engine and spring producers. Near-term component orders will depend on the conversion of development programs into fleet deployment.
Europe is the most active regulatory setting for the hydrogen engine injector springs market. Euro 7 applies to new heavy-duty vehicle models from May 2028 and establishes extended lifetime emissions performance requirements. IAV and DEUTZ began daily logistics work with hydrogen trucks in Germany during March 2026. Daimler Truck and KEYOU target a 2027 European launch for the HICE.40. Volvo Trucks has begun road testing and plans commercial availability before 2030. The region gives suppliers a clear but demanding route from demonstration vehicles to platform approval.
Asia-Pacific records the fastest regional growth at a 99.2% CAGR through 2031. Japan's hydrogen programs support hardware development across transport and marine uses. The 2025 land-based marine hydrogen-engine operation brought together Kawasaki Heavy Industries, Yanmar Power Solutions, and Japan Engine Corporation. China's policy goal of 40% new-energy heavy-truck penetration by 2030 broadens the addressable environment for component suppliers. India's hydrogen localization effort can create opportunities for domestic engine and precision-component production. South America and the Middle East and Africa remain early-stage markets within the forecast period. Their long-term potential is tied to hydrogen infrastructure and commercial-vehicle deployment.
- Barnes Group Inc.
- Lee Spring
- Microspring Products
- Mubea
- MW Components
- NHK Spring Co., Ltd.
- RPK, S. Coop.
- SCHERDEL GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of Hydrogen Internal-Combustion Engines in Heavy-Duty and Off-Highway Fleets
- 4.2.2 High-Pressure Direct Injection Increasing Injector Spring Duty Cycles
- 4.2.3 Hydrogen-Compatible Spring Materials and Coatings Improving Injector Service Life
- 4.2.4 Reuse of Established Engine Manufacturing Capacity for Hydrogen Powertrains
- 4.2.5 Hydrogen Engine Demonstration Fleets Converting Prototype Demand Into Qualification Orders
- 4.2.6 Localization Mandates Accelerating Precision Spring Manufacturing in Asia
- 4.3 Market Restraints
- 4.3.1 Limited Commercial Volume of Hydrogen Engines and Replacement Injectors
- 4.3.2 Hydrogen-Induced Embrittlement and Premature Fracture in High-Strength Spring Steels
- 4.3.3 Dry Hydrogen, Galling, and Poor Internal Lubricity Increasing Failure Risk
- 4.3.4 High Validation Cost for Multi-Billion-Cycle Injector Durability
- 4.4 Supply-Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Type
- 5.1.1 Coil Springs
- 5.1.2 Belleville / Disc Springs
- 5.1.3 Multi-layer Springs
- 5.2 By Material
- 5.2.1 Stainless Steel
- 5.2.2 Nickel Alloys
- 5.2.3 Precipitation Hardening Steels
- 5.2.4 Advanced Composites & Hybrids
- 5.3 By Coating/Surface Treatment
- 5.3.1 PVD/CVD Hard Coatings
- 5.3.2 Nitriding & Nitrocarburizing
- 5.3.3 Ceramic & DLC Coatings
- 5.3.4 Shot Peening & Residual Stress Treatments
- 5.4 By Application
- 5.4.1 On-road Hydrogen Engines
- 5.4.2 Off-road Hydrogen Engines
- 5.4.3 Stationary Hydrogen Power Systems
- 5.5 By End-user
- 5.5.1 Automotive OEMs
- 5.5.2 Heavy-duty Engine Manufacturers
- 5.5.3 Industrial Engine OEMs
- 5.5.4 Hydrogen Power System Integrators
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 United Kingdom
- 5.6.2.2 Germany
- 5.6.2.3 France
- 5.6.2.4 Spain
- 5.6.2.5 Nordic Countries
- 5.6.2.6 Russia
- 5.6.2.7 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 India
- 5.6.3.3 Japan
- 5.6.3.4 South Korea
- 5.6.3.5 ASEAN Countries
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 South America
- 5.6.4.1 Brazil
- 5.6.4.2 Argentina
- 5.6.4.3 Colombia
- 5.6.4.4 Rest of South America
- 5.6.5 Middle East and Africa
- 5.6.5.1 United Arab Emirates
- 5.6.5.2 Saudi Arabia
- 5.6.5.3 South Africa
- 5.6.5.4 Egypt
- 5.6.5.5 Rest of Middle East and Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Barnes Group Inc.
- 6.4.2 Lee Spring
- 6.4.3 Microspring Products
- 6.4.4 Mubea
- 6.4.5 MW Components
- 6.4.6 NHK Spring Co., Ltd.
- 6.4.7 RPK, S. Coop.
- 6.4.8 SCHERDEL GmbH
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


