

|
시장보고서
상품코드
2154964
북미의 5G 코어 네트워크 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)North America 5G Core Network - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
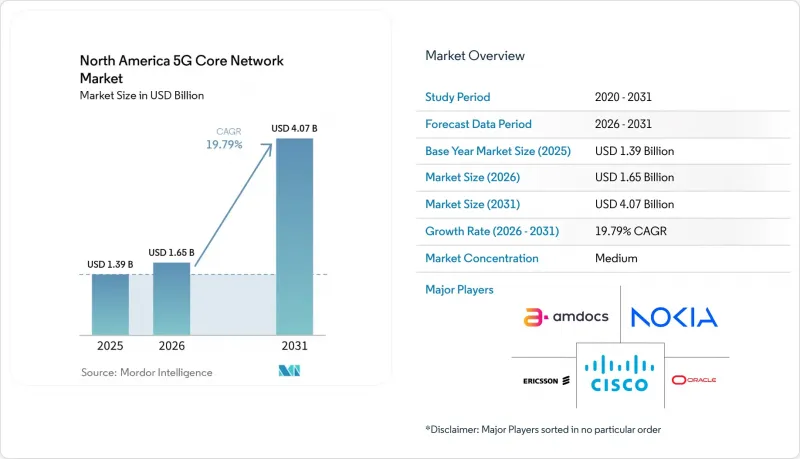
에 따르면 북미의 5G 코어 네트워크 시장 규모는 2025년 13억 9,000만 달러에서 2026년에는 16억 5,000만 달러로 확대하며, 2026-2031년에 CAGR 19.79%로 추이하며, 2031년에는 40억 7,000만 달러에 달할 것으로 예측됩니다.
북미 5G 코어 네트워크 시장의 동향과 인사이트
스탠드얼론형 5G의 확산이 전환점에 도달
AT&T와 Verizon은 2025년 하반기에 독립형 코어 네트워크 제공을 시작했으며, T-Mobile에 이어 미국의 Tier 1 통신사 3곳 모두가 상업적으로 차별화된 독립형 서비스를 제공하게 되었습니다. 이러한 변화로 인해 가입자 전환 및 서비스 개발을 독립형 아키텍처로 전환해야 한다는 압박이 커졌습니다. AT&T는 자사의 플랫폼을 Microsoft Azure 및 자사 데이터센터 전반에서 운영되는 개방형 가상화 아키텍처라고 설명하고 있습니다. VTel Wireless는 2026년 3월, 전국 규모의 통신사와의 종단 간 독립형 VoNR(Voice over New Radio) 로밍을 지원하는 듀얼 모드 5G 코어 및 무선 액세스 네트워크 구축 파트너로 에릭슨을 선정했습니다. 이는 북미 5G 코어 네트워크 시장이 대도시권의 주요 통신사업자 범위를 넘어 확대되고 있음을 보여줍니다. ATIS는 전용 주파수 대역의 부족과 비독립형 방식에서 업그레이드함에 따른 경제성 문제가 중소규모 통신사업자에게 중요한 장벽이라고 지적하고 있습니다.
북미 통신사업자의 클라우드 네이티브 코어 도입
클라우드 네이티브 코어의 도입은 주요 지역 통신사업자에서 전략적 목표에서 운영 모델로 발전하고 있습니다. 소프트웨어는 쿠버네티스(Kubernetes) 호환 인프라 위에 배포할 수 있으며, 이를 통해 소프트웨어 벤더, 시스템 통합사업자, 클라우드 플랫폼 제공업체 등이 공급업체 기반에 합류하게 됩니다. 에릭슨은 2025년 6월, Google Cloud와 공동으로 ‘On-Demand 5G Core-as-a-Service’ 플랫폼을 출시했습니다. Boost Mobile은 2025년 3월, 퍼블릭 클라우드에 노키아의 클라우드 네이티브 5G 음성 코어를 도입하여 여러 IMS 음성 기능을 하나의 클라우드 네이티브 네트워크 기능으로 통합했습니다. Mavenir사의 보고서에 따르면 조사 대상 통신사업자의 82%가 클라우드 네이티브 코어를 운영 중이거나 2026년 말까지 운영을 시작할 예정인 것으로 밝혀졌습니다. 따라서 북미의 5G 코어 네트워크 시장에서는 보다 폭넓은 도입 모델이 존재하지만, 통신사업자에게는 여전히 이를 관리하기 위한 기술이 요구되고 있습니다.
코어 네트워크 현대화에 따른 고액의 초기 비용
코어 현대화는 규모에 관계없이 모든 통신사업자에게 자본 비용과 운영 비용 절감을 요구하는 압박을 가하고 있습니다. 지방이나 농촌 지역의 통신사업자는 가입자 수가 적음에도 불구하고 사이트별 통합 비용이 Tier 1 사업자와 비슷한 수준이 되는 경우가 많습니다. 또한 수년에 걸친 전환 기간 중 Evolved Packet Core와 5G 코어 스택을 병행 운영하는 것은 전환 후 지원 비용을 상승시킬 가능성도 있습니다. 멕시코의 경우, 의회가 매년 주파수 사용료를 책정하고 있으며, 추가적인 불확실성에 직면해 있습니다. AT&T 멕시코는 향후 진행될 산업용 5G 주파수 경매에 참여하지 않을 가능성이 있음을 시사했습니다. Mavenir의 조사에 따르면 독립형(SA) 방식 도입 계획은 공급업체가 클라우드 네이티브 코어로의 전환에 관한 신뢰할 수 있는 총소유비용(TCO) 근거를 제시할 수 있는지 여부에 달려 있는 것으로 나타났습니다.
부문 분석
2025년, 북미 5G 코어 네트워크 시장 매출 중 솔루션이 63.55%를 차지했습니다. 이 부문에는 패킷 코어 소프트웨어, 네트워크 기능 가상화(NFV) 인프라, 오케스트레이션 및 관리 플랫폼이 포함됩니다. 이 점유율은 AT&T, Verizon, T-Mobile, Bell, Rogers, Telus가 Tier 1 독립형 구축을 위해 진행한 소프트웨어 주도형 투자를 반영한 것입니다. 통신사업자들이 하드웨어 기반의 레거시 시스템을 대체할 클라우드 네이티브 네트워크 기능을 필요로 하고 있으므로 패킷 코어 소프트웨어는 여전히 중심적인 위치를 차지하고 있습니다.
북미 5G 코어 네트워크 시장의 서비스는 2031년까지 연평균 성장률(CAGR) 21.21%로 확대될 것으로 예측됩니다. 이 부문에는 통합 및 구축, 컨설팅 및 자문, 지원 및 유지보수가 포함됩니다. 클라우드 네이티브 독립형 코어는 빈번한 소프트웨어 업데이트가 필요하지만, 통신사업자들은 여전히 클라우드 네이티브 운영에 필요한 기술 인력 부족에 직면해 있습니다. 에릭슨은 2025년 4월, 알래스카의 GCI Communication Corp사를 대상으로 클라우드 코어 기술, AI 툴, 지속적인 네트워크 관리를 포함한 듀얼 모드 5G 코어의 도입 및 운영에 합의했습니다. 통신사업자가 병행하여 운영하고 있는 EPC(Evolved Packet Core) 시스템을 단계적으로 폐지해 나감에 따라 지원 및 유지보수 수요는 앞으로도 지속될 것으로 예상됩니다.
2025년, 북미 5G 코어 네트워크 시장 매출 중 온프레미스/전용 구축이 51.95%를 차지했습니다. 통신사업자와 기업은 저지연, 데이터 처리 관련 규정 준수, 인프라 제어 등이 필요한 경우 이 모델을 선택했습니다. 전용 구축은 엄격한 서비스 수준 요구 사항이 필요한 공장 환경에서 특히 중요합니다. 버라이즌의 ‘지능형 엣지 네트워크’ 전략은 핵심 영역에서의 종단 간 소유권과 레벨 4 자율성을 중시하는 회사의 입장을 반영하고 있습니다.
북미 5G 코어 네트워크 시장에서 퍼블릭 클라우드는 2031년까지 연평균 성장률(CAGR) 24.76%로 확대될 것으로 예측됩니다. AT&T는 2025년 10월, Microsoft Azure 상에 전국 규모의 독립형 코어 네트워크를 구축하여 수억 명의 가입자를 대상으로 60개 이상의 컨테이너화된 네트워크 기능을 가동했습니다. 이 구축은 퍼블릭 클라우드 인프라가 Tier 1 수준의 규모와 신뢰성 요건을 충족할 수 있음을 입증했습니다. Google Cloud와 연동된 에릭슨의 플랫폼은 사내 클라우드 엔지니어링 역량이 제한적인 통신사업자에게 관리형 옵션을 제공합니다. 하이브리드 및 통신 엣지 클라우드(Telco Edge Cloud)는 온프레미스 인프라와 클라우드 네이티브 오케스트레이션을 결합한 것으로, 캐나다와 멕시코의 중견 통신사업자에게 유용하며, 레거시 패킷 코어 시스템의 교체를 지원합니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 업계 밸류체인 분석
- 규제 상황
- 기술 전망
- PESTLE 분석
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 컴포넌트별
- 배포 모델별
- 최종사용자별
- 네트워크 기능별
- 국가별
- 미국
- 캐나다
- 멕시코
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- Telefonaktiebolaget LM Ericsson
- Nokia Corporation
- Microsoft Corporation
- Samsung Electronics Co. Ltd.
- Amdocs Limited
- Cisco Systems, Inc.
- Oracle Corporation
- Hewlett Packard Enterprise Company
- Mavenir Systems, Inc.
- NEC Corporation
- VMware, Inc.
- Juniper Networks, Inc.
- Ciena Corporation
- Ribbon Communications Inc.
- Casa Systems, Inc.
- Parallel Wireless, Inc.
- Druid Software Ltd.
- Intel Corporation
- F5, Inc.
제7장 시장 기회와 향후 전망
KSA 26.10.28According to Mordor Intelligence, the North America 5G core network market size is expected to grow from USD 1.39 billion in 2025 to USD 1.65 billion in 2026 and is forecast to reach USD 4.07 billion by 2031 at 19.79% CAGR over 2026-2031.
North America 5G Core Network Market Trends and Insights
Standalone 5G Rollouts Reach an Inflection Point
AT&T and Verizon launched standalone cores in late 2025, joining T-Mobile and giving all 3 United States Tier-1 carriers commercially differentiated standalone services. This shift increased pressure to move subscribers and service development onto standalone architectures. AT&T described its platform as an open, virtualized architecture that runs across Microsoft Azure and its own data centers. VTel Wireless selected Ericsson in March 2026 for a dual-mode 5G core and radio access network that supports end-to-end standalone Voice over New Radio roaming with nationwide providers. This demonstrates that the North America 5G core network market is extending beyond large urban carriers. ATIS identified limited dedicated spectrum and the remaining economics of non-standalone upgrades as important barriers for smaller carriers.
Cloud-Native Core Adoption Across North American Operators
Cloud-native core adoption has progressed from a strategic objective to an operating model among major regional operators. Software can be deployed on Kubernetes-compatible infrastructure, which broadens the supplier base to include software vendors, systems integrators, and cloud platform providers. Ericsson launched its On-Demand 5G Core-as-a-Service platform with Google Cloud in June 2025. Boost Mobile deployed Nokia's cloud-native 5G Voice Core on a public cloud in March 2025 and consolidated multiple IMS voice functions into 1 cloud-native network function. Mavenir reported that 82% of surveyed operators either operated cloud-native cores or planned to do so by the end of 2026. The North America 5G core network market, therefore, has a wider range of implementation models, but operators still need the skills to manage them.
High Upfront Core Modernization Costs
Core modernization places pressure on carriers of all sizes to reduce capital and operating costs. Regional and rural carriers often face similar per-site integration costs to those of Tier-1 operators, despite having smaller subscriber bases. Running Evolved Packet Core and 5G core stacks during a multi-year migration can also raise post-migration support costs. Mexico faces further uncertainty because Congress sets spectrum fees annually. AT&T Mexico indicated that it might not participate in the upcoming industrial 5G spectrum auction. Mavenir found that planned standalone adoption depends on vendors providing credible total cost of ownership evidence for cloud-native core migration.
Other drivers and restraints analyzed in the detailed report include:
- Enterprise Private 5G Demand in Manufacturing and Logistics
- Network Slicing Requirements for Mission-Critical Services
- Legacy EPC Integration Complexity
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Solutions accounted for 63.55% of the North America 5G core network market revenue in 2025. The segment includes packet-core software, network function virtualization infrastructure, and orchestration and management platforms. Its position reflected software-led spending on Tier-1 standalone buildouts by AT&T, Verizon, T-Mobile, Bell, Rogers, and Telus. Packet-core software remained central because operators need cloud-native network functions to replace hardware-based legacy systems.
Services in the North America 5G core network market are projected to expand at a 21.21% CAGR through 2031. The segment covers integration and deployment, consulting and advisory, and support and maintenance. Cloud-native standalone cores require frequent software updates, while operators continue to face a shortage of cloud-native operations skills. Ericsson agreed in April 2025 to deploy and operate a dual-mode 5G core for GCI Communication Corp in Alaska, including cloud-core technology, AI tools, and ongoing network management. Support and maintenance demand is expected to continue as operators retire parallel Evolved Packet Core systems.
On-Premise/Dedicated deployments accounted for 51.95% of North America's 5G core network market revenue in 2025. Operators and enterprises selected this model when they required low latency, data-handling compliance, and infrastructure control. Dedicated deployments are particularly relevant for factory environments with strict service-level requirements. Verizon's Intelligent Edge Network strategy reflects its preference for end-to-end ownership in critical core areas and Level 4 autonomy.
Public Cloud in the North America 5G core network market is projected to expand at a 24.76% CAGR through 2031. AT&T deployed its nationwide standalone core on Microsoft Azure in October 2025, running more than 60 containerized network functions for hundreds of millions of subscribers. This deployment demonstrated that public cloud infrastructure can meet Tier-1-scale and reliability requirements. Ericsson's platform with Google Cloud gives carriers a managed option when internal cloud engineering capacity is limited. Hybrid and Telco Edge Cloud combines local infrastructure with cloud-native orchestration and is relevant to mid-tier Canadian and Mexican operators, helping them replace legacy packet-core systems.
Complete Report Scope:
- By Component
- Solutions
- Packet-Core Software
- NFV Infrastructure
- Orchestration and Management
- Services
- Integration and Deployment
- Consulting and Advisory
- Support and Maintenance
- Solutions
- By Deployment Model
- On-Premise/Dedicated
- Public Cloud
- Hybrid and Telco Edge Cloud
- By End-User
- Telecom Operators
- Enterprises
- Manufacturing
- Energy and Utilities
- Transportation and Logistics
- Public Safety and Emergency
- Smart Cities and Municipalities
- By Network Function
- Network Exposure Function (NEF)
- User Plane Function (UPF)
- Application Function (AF)
- Unified Data Management (UDM)
- Session Management Function (SMF)
- Network Slice Selection Function (NSSF)
- Policy Control Function (PCF)
- Network Repository Function (NRF)
- Authentication Server Function (AUSF)
- Access and Mobility Management Function (AMF)
- By Country
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- Telefonaktiebolaget LM Ericsson
- Nokia Corporation
- Microsoft Corporation
- Samsung Electronics Co. Ltd.
- Amdocs Limited
- Cisco Systems, Inc.
- Oracle Corporation
- Hewlett Packard Enterprise Company
- Mavenir Systems, Inc.
- NEC Corporation
- VMware, Inc.
- Juniper Networks, Inc.
- Ciena Corporation
- Ribbon Communications Inc.
- Casa Systems, Inc.
- Parallel Wireless, Inc.
- Druid Software Ltd.
- Intel Corporation
- F5, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Standalone 5G Rollouts Reaching Inflection Point
- 4.2.2 Cloud-Native Core Adoption Across North American Operators
- 4.2.3 Enterprise Private 5G Demand in Manufacturing and Logistics
- 4.2.4 Network Slicing Requirements for Mission-Critical Services
- 4.2.5 Open RAN and Interoperability Programs Requiring Flexible Core Architectures
- 4.2.6 AI-Driven Automation and Policy Control Modernization
- 4.3 Market Restraints
- 4.3.1 High Upfront Core Modernization Costs
- 4.3.2 Legacy EPC Integration Complexity
- 4.3.3 Cloud-Native Skills Shortage in Telecom Operations
- 4.3.4 Security, Sovereignty, and Compliance Constraints
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 PESTLE Analysis
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Solutions
- 5.1.1.1 Packet-Core Software
- 5.1.1.2 NFV Infrastructure
- 5.1.1.3 Orchestration and Management
- 5.1.2 Services
- 5.1.2.1 Integration and Deployment
- 5.1.2.2 Consulting and Advisory
- 5.1.2.3 Support and Maintenance
- 5.1.1 Solutions
- 5.2 By Deployment Model
- 5.2.1 On-Premise/Dedicated
- 5.2.2 Public Cloud
- 5.2.3 Hybrid and Telco Edge Cloud
- 5.3 By End-User
- 5.3.1 Telecom Operators
- 5.3.2 Enterprises
- 5.3.2.1 Manufacturing
- 5.3.2.2 Energy and Utilities
- 5.3.2.3 Transportation and Logistics
- 5.3.2.4 Public Safety and Emergency
- 5.3.2.5 Smart Cities and Municipalities
- 5.4 By Network Function
- 5.4.1 Network Exposure Function (NEF)
- 5.4.2 User Plane Function (UPF)
- 5.4.3 Application Function (AF)
- 5.4.4 Unified Data Management (UDM)
- 5.4.5 Session Management Function (SMF)
- 5.4.6 Network Slice Selection Function (NSSF)
- 5.4.7 Policy Control Function (PCF)
- 5.4.8 Network Repository Function (NRF)
- 5.4.9 Authentication Server Function (AUSF)
- 5.4.10 Access and Mobility Management Function (AMF)
- 5.5 By Country
- 5.5.1 United States
- 5.5.2 Canada
- 5.5.3 Mexico
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Telefonaktiebolaget LM Ericsson
- 6.4.2 Nokia Corporation
- 6.4.3 Microsoft Corporation
- 6.4.4 Samsung Electronics Co. Ltd.
- 6.4.5 Amdocs Limited
- 6.4.6 Cisco Systems, Inc.
- 6.4.7 Oracle Corporation
- 6.4.8 Hewlett Packard Enterprise Company
- 6.4.9 Mavenir Systems, Inc.
- 6.4.10 NEC Corporation
- 6.4.11 VMware, Inc.
- 6.4.12 Juniper Networks, Inc.
- 6.4.13 Ciena Corporation
- 6.4.14 Ribbon Communications Inc.
- 6.4.15 Casa Systems, Inc.
- 6.4.16 Parallel Wireless, Inc.
- 6.4.17 Druid Software Ltd.
- 6.4.18 Intel Corporation
- 6.4.19 F5, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


