

|
시장보고서
상품코드
2157118
북미의 금속 성형 장비 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)North America Metal Forming Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
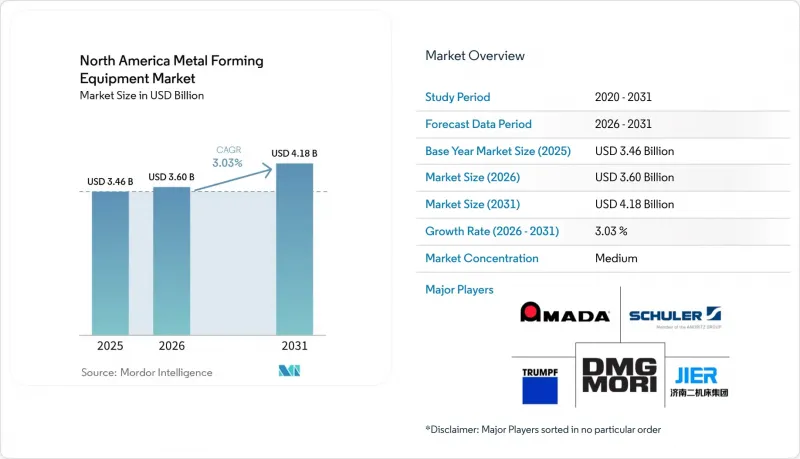
에 따르면 북미의 금속 성형 장비 시장 규모는 2025년 34억 6,000만 달러, 2026년 36억 달러에서 2031년까지 41억 8,000만 달러로 확대될 것으로 예측되고 있으며, 2026-2031년까지 연평균 성장률(CAGR)은 3.03%에 달할 전망입니다.
북미 금속 성형 장비 시장의 동향 및 인사이트
금속 집약형 제조업 분야의 리쇼어링과 니어쇼어링
리쇼어링은 해당 지역의 성형 설비에 대한 설비 투자를 촉진하고 있습니다. ‘리쇼어링 구상’ 보고서에 따르면 2024년에는 리쇼어링 및 외국인 직접 투자를 통해 미국에서 24만 4,000개의 제조업 일자리가 창출될 것이라고 발표되었습니다. 또한 2025년에는 금속 가공 관련 발표 건수가 19% 증가한 것으로 보고되었습니다. 해당 단체의 2026년 조사에 따르면 응답한 OEM 기업의 63%가 리쇼어링 또는 국내 사업 확장을 목적으로 2026년 또는 2027년에 미국내 설비 투자를 계획하고 있는 것으로 나타났습니다. 신규 시설에서는 일반적으로 기존 설비보다 더 대형의 프레스 기계, 자재 취급 시스템 및 통합 제어 시스템이 필요합니다. 그린필드 프로젝트에서 초기 단계부터 더 높은 수준의 자동화와 문서화된 품질관리가 사양으로 정해지면, 북미 금속 성형 설비 시장은 그 혜택을 누리게 될 것입니다.
전동화 및 배터리 부품 제조
배터리 부품 프로젝트는 정밀 성형 라인에 대한 수요를 창출하고 있습니다. 캐나다 정부는 퀘벡주 그랑비에 건설될 Volta Energy Solutions Canada사의 7억 6,090만 캐나다 달러(5억 4,428만 달러) 규모의 동박 제조 시설에 대해 7,000만 캐나다 달러(5,007만 달러)의 지원을 약속했습니다. 이 공장은 2027년부터 연간 2만 5,000톤의 배터리 등급 동박을 생산할 전망입니다. 배터리 케이스 및 관련 구조물에는 심압 성형, 정밀 성형, 그리고 박판 재료의 재현성 있는 취급이 필요합니다. AIDA사의 직사각형 배터리 케이스 전용 성형기 ‘DPH 시리즈’는 한 번의 스트로크로 다단계 성형이 가능한 기능 덕분에 ‘2025년 베스트 10 신제품상’을 수상했습니다. 이러한 프로젝트는 생산 공정을 줄이면서 배터리 케이스를 성형할 수 있는 설비에 대한 수요를 창출함으로써 북미 금속 성형 장비 시장을 지원하고 있습니다.
높은 자본 집약도와 긴 투자 회수 기간
서보식 트랜스퍼 프레스, 자동 자재 취급 시스템 및 통합형 품질관리 시스템은 라인당 수백만 달러의 비용이 소요될 수 있습니다. 이러한 비용으로 인해 자금 조달 수단이 제한적인 중소규모 제조업체에게는 설비의 전면적인 갱신이 어렵습니다. 설비 구입 외에도 구매자는 금형, 시설 개조, 전기 설비 업그레이드, 소프트웨어 통합, 작업자 교육 및 시운전 비용도 고려해야 하므로, 이로 인해 자동화 프로젝트에 필요한 총 투자액이 증가합니다. 자동화 라인의 투자 회수 기간은 3-5년으로, 기존의 2-3년 범위에 비해 길어졌습니다. 투자 회수 기간이 길어지면, 특히 수주량이 변동하기 쉽고 향후 생산 요건을 예측하기 어려운 수주 생산형 공장의 경우 자금 조달 승인이 더욱 어려워질 가능성이 있습니다. 또한 시운전에는 공인 전기 기술자나 제어 엔지니어가 필요하며, 생산 개시까지 6-12주의 추가 기간이 소요될 수 있습니다. 설치 기간이 길어지면, 특히 새로운 라인이 가동되기 전에 기존 프레스 기계를 중단해야 하는 경우 일시적인 생산 손실을 초래할 수 있습니다. 2023년 및 2024년의 금리 상승으로 인해 내구 연한이 긴 자본 자산의 차입 비용이 상승했습니다. 그 결과, 일부 제조업체는 전체 라인을 교체하기보다는 단계적 자동화, 개조 프로그램 또는 선택적 업그레이드를 선호할 가능성이 있습니다. 이러한 상황은 북미 지역의 구매 결정을 지연시키는 요인이 될 수 있습니다.
부문별 분석
2025년, 프레스 기계는 북미 금속 성형 장비 시장의 41.5%를 차지했습니다. 이 범주에는 블랭킹, 순차 프레스 및 관련 작업을 위한 기계식, 유압식, 서보식, 범용 시스템이 포함됩니다. 그 규모는 다양한 성형 용도 및 최종 용도 분야의 활용을 반영합니다. 수요는 자동차 부품, 전기·전자 부품, 가전제품, 산업 기계 및 일관된 성형 정밀도와 사이클 타임이 중요한 기타 대량 생산 용도에 의해 지원되고 있습니다. 구매자들은 또한 재현성 있는 생산, 가동 데이터 수집 및 첨단 자동화를 지원하는 설비를 중요하게 여깁니다. 이러한 요구 사항으로 인해 프레스 본체와 제어 시스템, 수명주기 서비스를 결합한 공급업체가 유리한 입지를 차지하고 있습니다. 자동 공급, 로봇을 이용한 부품 취급, 인라인 검사, 생산 모니터링 시스템과의 통합 또한 포괄적인 프레스 솔루션의 가치를 높이고 있습니다.
서보 프레스 시장은 2031년까지 연평균 성장률(CAGR) 5.2%로 확대될 것으로 예측됩니다. 구매자들은 이러한 시스템에 대해 낮은 에너지 소비와 보다 정밀한 모션 제어를 요구하고 있습니다. 또한 프로그래밍 가능한 슬라이드 동작을 통해 제조업체는 다양한 재료 및 금형 요구 사항에 맞춰 성형 프로파일을 최적화할 수 있을 뿐만 아니라, 설비 전환 시간을 단축하고 공정 일관성을 향상시킬 수도 있습니다. 공유 DC 버스를 통한 에너지 관리 기능을 갖춘 서보 스핀들 프레스 플랫폼은 기존 유압 시스템에 비해 스트로크당 에너지 소비량을 70-85% 절감할 수 있습니다. 이러한 효율성 이점은 장시간 생산 사이클에서 여러 대의 프레스를 가동하는 시설에서 더욱 중요해질 수 있습니다. 프레스 브레이크 및 굽힘 가공기는 두 번째로 큰 설비 그룹인 반면, 단조, 롤 성형, 하이드로포밍 및 압출 성형 설비는 각각 서로 다른 용도에 대응합니다. 이러한 기술의 조합을 통해 제조업체는 재료의 두께, 부품의 형상, 생산량, 성형력 및 요구되는 치수 정밀도에 따라 장비를 선택할 수 있습니다. TRUMPF사는 2026년, 코네티컷주 파밍턴에 위치한 공장에서 TruBend 3000 시리즈 프레스 브레이크의 생산을 시작했습니다.
2025년, 북미 금속 성형 설비 시장에서 스탬핑 및 펀칭이 30.5%의 점유율을 차지했습니다. 자동차 차체 생산에서는 미시간주, 온타리오주 및 멕시코 북부 전역에서 대량 생산용 블랭킹 및 순차 금형 라인이 사용되고 있습니다. 경량 차체 구조와 초고장력강의 사용 확대에 따라 더 높은 프레스 힘, 더 엄격한 공정 관리 및 특수 금형에 대한 요구가 높아지고 있습니다. 딥 드로잉 및 굽힘 가공은 제조 및 부품 생산에서 중요합니다. 이러한 공정은 가전제품, HVAC 시스템, 전기 인클로저, 산업 기계 등의 용도도 지원하고 있으며, 자동차 수요에 대한 의존도를 낮추고 있습니다. 단조는 높은 신뢰성이 요구되는 파워트레인 부품 및 항공우주 부품에 활용되고 있는 반면, 압연 및 롤 성형은 건축용 프로파일 및 태양광발전용 마운트의 수요로 인해 혜택을 보고 있습니다. 코일 공급, 로봇 이송, 인라인 검사, 금형 교환 시스템을 통한 자동화로 인해 대량 생산의 처리량이 더욱 향상되고 있습니다. 이러한 다양한 수요 구성으로 인해 북미 금속 성형 장비 시장은 여러 제조 투자 주기의 영향을 받게 될 것입니다.
하이드로포밍은 2031년까지 연평균 성장률(CAGR) 5.1%로 성장할 것으로 예측됩니다. EV의 언더바디 어셈블리 및 섀시 프레임에는 용접 이음매의 수를 줄일 수 있는 복잡한 형상이 채택되고 있습니다. 이 공정은 필요한 강도와 치수의 일관성을 유지하면서 경량 구조 설계를 실현할 수 있으므로, 차량 경량화 프로그램에서 중요한 역할을 하고 있습니다. 슐러 북미(Schuler North America)는 미시간주 캔턴에 위치한 하이드로포밍 생산 센터에 기존의 3,500톤 및 8,500톤 설비에 더해 5,000톤 프레스기를 도입했습니다. 프로그래밍 가능한 제어 시스템을 통해 첨단 고장력 강판이나 알루미늄을 가공할 수 있는 유연성이 높은 생산 라인은 여전히 큰 잠재력을 지니고 있습니다. 이러한 유연성 덕분에 제조사는 용도별로 개별 성형 라인에 투자하지 않고도 변화하는 차량 플랫폼 및 재료 사양에 대응할 수 있게 됩니다. 이미 도입된 설비의 대부분은 두 재료를 모두 효율적으로 가공하기 위해 설정을 변경해야 합니다. 이로 인해 새로운 하이드로포밍 설비 외에도 제어 시스템 업그레이드, 금형 최적화, 자동 설정 시스템 및 공정 모니터링 솔루션 도입의 기회가 생겨납니다.
기타 이점:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 가치 및 공급망 분석
- 규제 상황
- 기술 전망
- 지정학적 이벤트가 시장에 미치는 영향의 평가
제5장 시장 규모와 성장 예측
- 기기 유형별
- 성형 프로세스별
- 성형 재료별
- 최종 용도 산업별
- 지역별
- 미국
- 캐나다
- 멕시코
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- TRUMPF Group
- AMADA Co., Ltd.
- Schuler AG
- JIER Machine-Tool Group Co., Ltd.
- DMG MORI Co., Ltd.
- Komatsu Ltd.
- AIDA Engineering, Ltd.
- Bystronic AG
- Salvagnini Italia S.p.A.
- Prima Industrie S.p.A.
- LVD Company NV
- Cincinnati Incorporated
- Haas Automation, Inc.
- Mazak Corporation
- Okuma Corporation
- The Lincoln Electric Company
- ESAB Corporation
- Mitsubishi Heavy Industries, Ltd.
- Accurpress
- Pacific Press Technologies
- Wilson Tool International
- WardJet
- OMAX Corporation
- Magna International Inc.
- Gestamp Automocion S.A.
- Martinrea International Inc.
- Flex-N-Gate Corporation
- Autokiniton US Holdings, Inc.
제7장 시장 기회와 향후 전망
KSA 26.10.30According to Mordor Intelligence, the North America metal forming equipment market size is projected to expand from USD 3.46 billion in 2025 and USD 3.60 billion in 2026 to USD 4.18 billion by 2031, registering a CAGR of 3.03% between 2026 and 2031.
North America Metal Forming Equipment Market Trends and Insights
Reshoring and Nearshoring of Metal-Intensive Manufacturing
Reshoring is supporting capital spending on forming equipment in the region. The Reshoring Initiative reported 244,000 United States manufacturing jobs announced through reshoring and foreign direct investment in 2024. It also reported that fabricated metals announcements increased 19% in 2025. Its 2026 survey found that 63% of responding OEMs plan United States capital investment in 2026 or 2027 for reshoring or domestic expansion. New facilities commonly require larger presses, material handling, and integrated controls than the equipment they replace. The North America metal forming equipment market benefits when greenfield projects specify higher levels of automation and documented quality controls from the start.
Electrification and Battery-Component Manufacturing
Battery-component projects are creating demand for precision forming lines. The Government of Canada committed CAD 70 million (USD 50.07 million) to Volta Energy Solutions Canada's CAD 760.9 million (USD 544.28 million) copper foil facility in Granby, Quebec. The plant is expected to produce 25,000 tonnes of battery-grade copper foil per year from 2027. Battery enclosures and related structures require deep drawing, controlled forming, and repeatable handling of thin materials. AIDA's DPH Series Dedicated Former for rectangular storage battery cases received the 2025 Ten Greatest New Products Award for its single-stroke, multi-step forming capability. Such projects support the North America metal forming equipment market by adding demand for equipment that can form battery cases with fewer production stages.
High Capital Intensity and Long Payback Periods
Servo transfer presses, automated material handling, and integrated quality controls can cost multiple millions of dollars per line. These costs make complete replacements difficult for small and mid-sized fabricators with limited financing access. Beyond the equipment purchase, buyers must account for tooling, facility modifications, electrical upgrades, software integration, operator training, and commissioning costs, increasing the total investment required for automation projects. The payback periods for automated lines are 3-5 years, compared with conventional 2-3 year ranges. Longer payback periods can make capital approval more difficult, particularly for job shops with variable order volumes and limited visibility into future production requirements. Commissioning also requires certified electricians and controls engineers, which can add 6-12 weeks before production begins. Extended installation periods can create temporary production losses, particularly when an existing press must be taken offline before the new line is operational. Higher interest rates in 2023 and 2024 raised borrowing costs for long-lived capital assets. As a result, some manufacturers may favor phased automation, retrofit programs, or selective upgrades rather than full-line replacement. These conditions can slow purchase decisions in North America.
Other drivers and restraints analyzed in the detailed report include:
- Demand for Lightweight and High-Strength Components
- Aging Press Fleet Replacement and Retrofit Demand
- Steel, Servo-Drive, and Controls Cost Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Press Machines held 41.5% of the North America metal forming equipment market in 2025. The category covers mechanical, hydraulic, servo, and general-purpose systems for blanking, progressive-die stamping, and related work. Its scale reflects use across many forming applications and end-use sectors. Demand is supported by automotive components, electrical and electronics parts, appliances, industrial machinery, and other high-volume manufacturing applications where consistent forming accuracy and cycle times are important. Buyers also value equipment that supports repeatable production, operational data capture, and higher levels of automation. These requirements favor suppliers that combine press hardware with controls and lifecycle services. Integration with automated feeding, robotic part handling, in-line inspection, and production-monitoring systems is also increasing the value of complete press solutions.
Servo Presses are projected to expand at a 5.2% CAGR through 2031. Buyers seek lower energy use and more precise motion control from these systems. Programmable slide motion also allows manufacturers to optimize forming profiles for different materials and tooling requirements, while supporting faster changeovers and improved process consistency. Servo spindle press platforms with shared DC-bus energy management can reduce energy use by 70-85% per stroke compared with conventional hydraulic systems. These efficiency benefits can become more relevant for facilities operating multiple presses for extended production cycles. Press Brakes and Bending Machines are the second-largest equipment group, while Forging, Roll Forming, Hydroforming, and Extrusion equipment serve distinct applications. The mix of technologies allows manufacturers to select equipment according to material thickness, component geometry, production volume, forming force, and required dimensional accuracy. TRUMPF began producing TruBend 3000 series press brakes at its Farmington, Connecticut, facility in 2026.
Stamping and Punching held 30.5% of the North America metal forming equipment market in 2025. Automotive body production uses high-volume blanking and progressive-die lines across Michigan, Ontario, and northern Mexico. The growing use of lightweight vehicle structures and advanced high-strength steels is increasing requirements for higher press forces, tighter process control, and specialized tooling. Deep Drawing and Bending are important for fabrication and component production. These processes also support applications in appliances, HVAC systems, electrical enclosures, and industrial machinery, reducing dependence on automotive demand alone. Forging serves high-integrity powertrain and aerospace parts, while Rolling and Roll Forming benefit from construction-profile and solar-mounting demand. Automation through coil feeding, robotic transfer, in-line inspection, and die-change systems is further improving throughput in high-volume operations. This mix exposes the North America metal forming equipment market to several manufacturing investment cycles.
Hydroforming is projected to grow at a 5.1% CAGR through 2031. EV underbody assemblies and chassis frames use complex geometries that can reduce the number of welded joints. The process can support lightweight structural designs while maintaining required strength and dimensional consistency, making it relevant to vehicle weight-reduction programs. Schuler North America is adding a 5,000-ton press to its Canton, Michigan Hydroforming Production Center, alongside existing 3,500-ton and 8,500-ton equipment. Flexible lines that run advanced high-strength steel and aluminum through programmable controls remain a potential opportunity. Such flexibility can help manufacturers accommodate changing vehicle platforms and material specifications without investing in separate forming lines for every application. Much of the installed base requires setup changes to process both materials efficiently. This creates opportunities for upgraded controls, tooling optimization, automated setup systems, and process-monitoring solutions alongside new hydroforming equipment.
Complete Report Scope:
- By Equipment Type
- Press Machines
- Mechanical Presses
- Hydraulic Presses
- Servo Presses
- Other General-Purpose Presses
- Press Brakes and Bending Machines
- Hydraulic Press Brakes
- Servo / Electric Press Brakes
- Mechanical Press Brakes
- Other Bending Machines
- Forging Equipment
- Forging Presses
- Forging Hammers
- Upsetting and Heading Machines
- Other Forging Equipment
- Roll Forming and Plate/Profile Rolling Equipment
- Roll Forming Machines
- Plate Rolling Machines
- Section and Profile Rolling Machines
- Other Secondary Rolling/Forming Equipment
- Wire, Tube and Profile Forming Equipment
- Wire and Bar Drawing/Forming Equipment
- Tube Forming and Bending Equipment
- Profile Forming Equipment
- Extrusion Presses
- Hydroforming Equipment
- Other Metal Forming Equipment
- Press Machines
- By Forming Process
- Stamping and Punching
- Deep Drawing
- Bending
- Forging
- Rolling and Roll Forming
- Extrusion
- Hydroforming
- Other Forming Processes
- By Material Formed
- Carbon and Low-Alloy Steel
- Stainless Steel
- Aluminum and Aluminum Alloys
- Copper and Copper Alloys
- Titanium, Nickel and Other Non-Ferrous Metals
- Other Materials
- By End-Use Industry
- Automotive and Transportation
- Aerospace and Defense
- Industrial Machinery and Capital Equipment
- Metal Products and Fabrication
- Electrical and Electronics
- Construction and Infrastructure
- Energy and Power
- Consumer Appliances and Durable Goods
- Medical and Precision Manufacturing
- Other End-Use Industries
- By Geography
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- TRUMPF Group
- AMADA Co., Ltd.
- Schuler AG
- JIER Machine-Tool Group Co., Ltd.
- DMG MORI Co., Ltd.
- Komatsu Ltd.
- AIDA Engineering, Ltd.
- Bystronic AG
- Salvagnini Italia S.p.A.
- Prima Industrie S.p.A.
- LVD Company NV
- Cincinnati Incorporated
- Haas Automation, Inc.
- Mazak Corporation
- Okuma Corporation
- The Lincoln Electric Company
- ESAB Corporation
- Mitsubishi Heavy Industries, Ltd.
- Accurpress
- Pacific Press Technologies
- Wilson Tool International
- WardJet
- OMAX Corporation
- Magna International Inc.
- Gestamp Automocion S.A.
- Martinrea International Inc.
- Flex-N-Gate Corporation
- Autokiniton US Holdings, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Reshoring and Nearshoring of Metal-Intensive Manufacturing
- 4.2.2 Electrification and Battery-Component Manufacturing
- 4.2.3 Demand for Lightweight and High-Strength Components
- 4.2.4 Aging Press Fleet Replacement and Retrofit Demand
- 4.2.5 Automation to Offset Skilled Labor Shortages
- 4.2.6 Traceable, Cybersecure and Energy-Efficient Forming Lines
- 4.3 Market Restraints
- 4.3.1 High Capital Intensity and Long Payback Periods
- 4.3.2 Steel, Servo-Drive and Controls Cost Volatility
- 4.3.3 Shortage of Tool-and-Die and Commissioning Specialists
- 4.3.4 Cybersecurity Exposure in Connected Press Lines
- 4.4 Value and Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.5.1 OSHA Machine Guarding and Mechanical Power Press Requirements
- 4.5.2 ANSI B11.1 and ANSI B11.2 Safety Standards
- 4.5.3 ISO 9001 and IATF 16949 Supplier Requirements
- 4.5.4 USMCA Regional Content Requirements
- 4.5.5 Buy America and Infrastructure-Linked Procurement
- 4.5.6 Section 301 Tariffs and Import Compliance
- 4.6 Technological Outlook
- 4.6.1 Servo and Advanced Drive Technologies
- 4.6.2 CNC and Advanced Process Controls
- 4.6.3 Robotics and Automated Material Handling
- 4.6.4 Connected Machines and IIoT
- 4.6.5 Predictive Maintenance and Condition Monitoring
- 4.6.6 Energy-Efficient Forming Systems
- 4.6.7 Advanced High-Strength and Lightweight Material Forming
- 4.7 Impact Assessment of Geopolitical Events on the Market
5 Market Size & Growth Forecasts
- 5.1 By Equipment Type
- 5.1.1 Press Machines
- 5.1.1.1 Mechanical Presses
- 5.1.1.2 Hydraulic Presses
- 5.1.1.3 Servo Presses
- 5.1.1.4 Other General-Purpose Presses
- 5.1.2 Press Brakes and Bending Machines
- 5.1.2.1 Hydraulic Press Brakes
- 5.1.2.2 Servo / Electric Press Brakes
- 5.1.2.3 Mechanical Press Brakes
- 5.1.2.4 Other Bending Machines
- 5.1.3 Forging Equipment
- 5.1.3.1 Forging Presses
- 5.1.3.2 Forging Hammers
- 5.1.3.3 Upsetting and Heading Machines
- 5.1.3.4 Other Forging Equipment
- 5.1.4 Roll Forming and Plate/Profile Rolling Equipment
- 5.1.4.1 Roll Forming Machines
- 5.1.4.2 Plate Rolling Machines
- 5.1.4.3 Section and Profile Rolling Machines
- 5.1.4.4 Other Secondary Rolling/Forming Equipment
- 5.1.5 Wire, Tube and Profile Forming Equipment
- 5.1.5.1 Wire and Bar Drawing/Forming Equipment
- 5.1.5.2 Tube Forming and Bending Equipment
- 5.1.5.3 Profile Forming Equipment
- 5.1.6 Extrusion Presses
- 5.1.7 Hydroforming Equipment
- 5.1.8 Other Metal Forming Equipment
- 5.1.1 Press Machines
- 5.2 By Forming Process
- 5.2.1 Stamping and Punching
- 5.2.2 Deep Drawing
- 5.2.3 Bending
- 5.2.4 Forging
- 5.2.5 Rolling and Roll Forming
- 5.2.6 Extrusion
- 5.2.7 Hydroforming
- 5.2.8 Other Forming Processes
- 5.3 By Material Formed
- 5.3.1 Carbon and Low-Alloy Steel
- 5.3.2 Stainless Steel
- 5.3.3 Aluminum and Aluminum Alloys
- 5.3.4 Copper and Copper Alloys
- 5.3.5 Titanium, Nickel and Other Non-Ferrous Metals
- 5.3.6 Other Materials
- 5.4 By End-Use Industry
- 5.4.1 Automotive and Transportation
- 5.4.2 Aerospace and Defense
- 5.4.3 Industrial Machinery and Capital Equipment
- 5.4.4 Metal Products and Fabrication
- 5.4.5 Electrical and Electronics
- 5.4.6 Construction and Infrastructure
- 5.4.7 Energy and Power
- 5.4.8 Consumer Appliances and Durable Goods
- 5.4.9 Medical and Precision Manufacturing
- 5.4.10 Other End-Use Industries
- 5.5 By Geography
- 5.5.1 United States
- 5.5.2 Canada
- 5.5.3 Mexico
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 TRUMPF Group
- 6.4.2 AMADA Co., Ltd.
- 6.4.3 Schuler AG
- 6.4.4 JIER Machine-Tool Group Co., Ltd.
- 6.4.5 DMG MORI Co., Ltd.
- 6.4.6 Komatsu Ltd.
- 6.4.7 AIDA Engineering, Ltd.
- 6.4.8 Bystronic AG
- 6.4.9 Salvagnini Italia S.p.A.
- 6.4.10 Prima Industrie S.p.A.
- 6.4.11 LVD Company NV
- 6.4.12 Cincinnati Incorporated
- 6.4.13 Haas Automation, Inc.
- 6.4.14 Mazak Corporation
- 6.4.15 Okuma Corporation
- 6.4.16 The Lincoln Electric Company
- 6.4.17 ESAB Corporation
- 6.4.18 Mitsubishi Heavy Industries, Ltd.
- 6.4.19 Accurpress
- 6.4.20 Pacific Press Technologies
- 6.4.21 Wilson Tool International
- 6.4.22 WardJet
- 6.4.23 OMAX Corporation
- 6.4.24 Magna International Inc.
- 6.4.25 Gestamp Automocion S.A.
- 6.4.26 Martinrea International Inc.
- 6.4.27 Flex-N-Gate Corporation
- 6.4.28 Autokiniton US Holdings, Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-Space and Unmet-Need Assessment
- 7.1.1 Flexible Multi-Material Forming Lines
- 7.1.2 Battery-Enclosure and EV Structural Forming
- 7.1.3 Retrofit Kits for Legacy Press Fleets
- 7.1.4 Cybersecure Remote-Service Platforms
- 7.1.5 Low-Energy Servo and Hybrid Systems
- 7.1.6 Workforce-Embedded Training and Commissioning Services


