

|
시장보고서
상품코드
2124625
해상 화물 운송 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Maritime Freight Transport - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
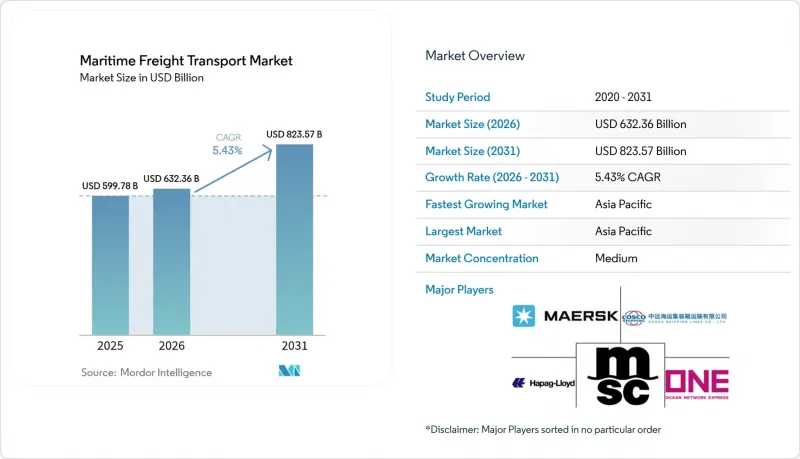
에 의하면, 해상 화물 운송 시장 규모는 2025년에 5,997억 8,000만 달러로 평가되었습니다. 2026년 6,323억 6,000만 달러에서 2031년까지 8,235억 7,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 5.43%를 나타낼 전망입니다.
본 보고서는 화물 유형별(컨테이너 화물, 건식 벌크 화물, 액체 벌크 화물, 일반 화물, 롤온/롤오프 화물), 최종 사용자 산업별(일렉트로믹스 및 반도체, 화학제품 및 석유화학제품, 식품 및 음료 등), 지역별(북미, 남미, 아시아태평양, 유럽, 중동 및 아프리카)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 해상 화물 운송 시장 동향 및 인사이트
아시아 역내 남남 무역 회랑의 급증
2023년, 아세안(ASEAN)은 4,688억 달러의 무역액으로 유럽연합(EU)을 제치고 중국의 최대 무역 상대국이 되었으며, 10.5%의 급증세를 기록했습니다. 이에 따라 아시아 역내 화물 순환망이 새로운 성장 동력으로서의 입지를 확고히 하고 있습니다. ACFTA(중국-아세안 자유무역협정)에 따른 단계적 관세 철폐로 서쪽의 환적 허브를 거치지 않는 물류 흐름이 효율화되는 한편, 2026년 개통이 예정된 총 길이 84마일의 중국 평루 운하는 연간 8,900만 톤의 화물을 운송하여 공급망 비용을 7억 2,500만 달러 절감하게 될 것입니다. 동남아시아로의 제조업 이전은 항만 인근의 산업 클러스터를 강화하고, 2차 게이트웨이로의 피더 수요를 증가시키고 있습니다. 그 결과 발생하는 화물 밀도는 단거리 운송이면서도 높은 순환 빈도를 실현하도록 최적화된 1만 5,000 TEU급 주력 선박에 대한 대규모 투자를 뒷받침하고 있습니다. 이러한 동향들이 종합적으로 해상 화물 운송 시장 예측 기간 동안 연평균 성장률(CAGR)에 약 1.2% 기여할 것으로 예측됩니다.
니어쇼어링이 근해 피더 수요를 견인
2024년, 미국과 멕시코 간 트럭 국경 통과 횟수가 사상 최고치를 기록하며, 니어쇼어링이 멕시코만 및 카리브해의 피더 항로에 파급되고 있음을 입증했습니다. 주요 해운사들은 현재 멕시코만의 소규모 항구를 우회하고, 지역 전문 업체와 계약하여 허브 앤 스포크 방식의 셔틀 서비스를 운영하고 있으며, 이를 통해 도어 투 도어 운송 주기를 2-4일 단축하고 있습니다. X-Press Feeders사가 6개 유럽 항만과 체결한 ‘그린 코리도(Green Corridor)’ 구축 협정은 스코프 3 배출량 목표를 달성하면서 증가하는 근해 운송 물량을 확보하려는 사업자들의 노력을 상징합니다. 경영진은 물류 비용 절감을 가장 큰 동기로 꼽고 있으며, 41%는 세계 규모보다 근접성을 우선시하고 있습니다. 수요 증가에 따라 1,500-2,000 TEU급 선박의 가동률과 일일 용선료가 상승하고 있으며, 이로 인해 해상 화물 운송 시장의 성장 궤도가 0.8포인트 상승했습니다.
만성적인 항만 인프라 병목 현상
2025년에는 싱가포르와 콜롬보가 케이프 루트 항로의 선박을 수용하면서 혼잡이 정점에 달했고, 야드 이용률이 90%를 넘어섰으며, 평균 버스 대기 시간이 3배로 증가했습니다. 상하이에서는 미국의 관세 발효에 앞서 2025년 1월 사상 최대인 500만 TEU를 처리했고, 18개의 완전 자동화 터미널을 추가했음에도 불구하고 야드 시설에 부담이 가중되었습니다. 로스앤젤레스와 롱비치는 섀시 부족으로 어려움을 겪고 있는 반면, 말라카 해협은 지정학적 혼란과 기후 변화로 인한 선박 침수 제한에 직면해 있습니다. 게이트 자동화 및 내륙 철도 연결에 대한 투자가 지연되면서 화물 유통 속도가 저해되고 있으며, 이는 해상 화물 운송 시장의 장기 연평균 성장률(CAGR)을 1.1% 하락시키고 있습니다.
부문별 분석
건화물이 가장 큰 점유율을 차지하고 있으며, 중국의 1억 6,500만 톤에 달하는 철광석 및 석탄 비축량 확대를 배경으로 2025년 해상 화물 운송 시장 규모의 28.65%를 차지했습니다. 그러나 2025년에 시행된 3,600만 dwt 규모의 선박 인도에 따라, 톤수 수요가 견조하게 증가함에도 불구하고 TCE(선박 총용선료) 요율이 하락할 위험이 있습니다. 따라서 선사는 하방 리스크를 완화하기 위해 지수 연동형 용선 계약으로 중심을 옮기고 있습니다. 공급 과잉에 대한 우려로 인해 핸디사이즈 선박의 조기 해체가 촉진되고 있으며, 이로 인해 틈새 항로공급이 억제되어 운임 하락 압력이 완화되고 있습니다.
액체 벌크 운송은 두드러진 성장 동력이 되고 있으며, LNG 액화량 확대 및 화학제품 무역의 다양화에 따라 2031년까지 연평균 성장률(CAGR)은 4.02%를 기록할 전망입니다. 2025년 VLCC의 현물 수익은 하루 5만 1,600달러로 기록되어, 주요 에너지 기업들의 정기 용선 계약에 대한 관심을 높였습니다. 유조선 선주들은 그린 프리미엄 화물을 확보하기 위해 듀얼 연료화를 추진하고 있으며, 한편 항만 운영사들은 암모니아 대응 선박에 대비하기 위해 극저온 수출 설비에 투자하고 있습니다. 액체 벌크 화물의 견조한 성장세는 해상 화물 운송 시장에 필요한 다양성을 가져다주며, 다른 화물 흐름의 변동을 완화하고 있습니다.
지역별 분석
아시아태평양은 2025년에 해상 화물 운송 시장 점유율의 37.65%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 5.02%로 성장할 전망입니다. 이는 지역 내 무역 의존도가 57%에 달하는 데 힘입은 것으로, 서유럽 시장 수요 주기에 좌우되지 않는 다양한 성장을 실현하고 있습니다. 상하이의 자동화 계획인 ‘블루프린트 18’(완전 무인 터미널)은 시간당 크레인 가동 횟수의 편차를 줄여, 부두 생산성에 새로운 기준을 제시하고 있습니다. 2026년까지 연간 8,900만 톤의 처리 능력을 갖출 중국의 핑루 운하는 내륙 수송의 병목 현상을 해소하고, 연간 7억 2,500만 달러의 비용 절감을 가져올 전망입니다.
북미에서는 2025년 10월부터 관세 재검토와 섹션 301에 따른 부과금으로 인해 중국산 선박의 비용이 상승하면서, 컨테이너 취급량이 1%라는 이례적인 감소를 겪었습니다. 그러나 멕시코에서의 무역 회복이 이를 부분적으로 상쇄하고 있으며, 니어쇼어링이 멕시코만 연안의 피더 서비스 및 내륙 철도 확충을 촉진하고 있습니다. 유럽에서는 연간 100억 유로(110억 3,000만 달러)에 달하는 배출권 거래 제도(ETS) 준수 비용에 직면하고 있으며, 이로 인해 운송 경로의 우선순위 재조정과 연료 보급 전략의 재검토가 진행되고 있습니다. 동시에, 그린 코리도(Green Corridor) 시범 사업을 통해 유럽의 항만들은 대체 연료 보급의 조기 도입 거점으로서의 입지를 확립해 가고 있습니다.
중동에서는 사우디아라비아의 45억 달러 규모 항만 투자를 활용하여, 2026년까지 지역 물류 수익을 388억 달러로 끌어올릴 전망입니다. IMEC는 철도와 항만의 통합적 연계를 통해 아시아-유럽 간 운송 시간을 40% 단축하겠다고 약속하며, 다극적 무역 흐름에서 이 지역의 역할을 부각시키고 있습니다. 남미는 중립적인 입지를 활용하여 공급망 혼란을 배경으로, 브라질에서 중국으로의 대두 수출이 확대되고 있습니다. 러시아와 나이지리아를 연결하는 항로가 BRICS 회원국을 위한 농업 회랑을 개척함에 따라, 아프리카의 점유율은 서서히 상승하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, the maritime freight transport market size was valued at USD 599.78 billion in 2025 and estimated to grow from USD 632.36 billion in 2026 to reach USD 823.57 billion by 2031, at a CAGR of 5.43% during the forecast period (2026-2031).
This report is Segmented by Cargo Type (Containerized Cargo, Dry Bulk Cargo, Liquid Bulk Cargo, General Cargo, Roll-On/Roll-Off Cargo), End-User Industry (Electronics & Semiconductors, Chemicals & Petrochemicals, Food & Beverage, and More), and Geography (North America, South America, Asia-Pacific, Europe, Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Maritime Freight Transport Market Trends and Insights
Surge in South-South Intra-Asian Trade Corridors
ASEAN surpassed the European Union as China's top trading partner in 2023 at USD 468.8 billion, a 10.5% jump that cements intra-Asian cargo loops as the new growth engine. Progressive tariff eliminations under ACFTA streamline flows that bypass Western transshipment hubs, while China's 84-mile Pinglu Canal slated for 2026 will move 89 million tons annually and slice USD 725 million from supply-chain costs. Manufacturing migration toward Southeast Asia reinforces near-port industrial clusters, amplifying feeder demand to secondary gateways. The resulting cargo density underpins scale investments in 15,000 TEU workhorses optimized for shorter hauls yet higher turn-round frequencies. Collectively, these dynamics contribute an estimated 1.2 percentage-points to the Maritime freight transport market CAGR forecast period.
Near-shoring Drives Short-Sea Feeder Demand
U.S.-Mexico truck crossings hit record levels in 2024, validating near-shoring's spillover into Gulf and Caribbean feeder loops. Mainline carriers now skip smaller Gulf ports, contracting regional specialists for hub-and-spoke shuttles that compress door-to-door cycles by two to four days. X-Press Feeders' pact with six European ports to create green corridors exemplifies operators capturing rising short-sea volumes while satisfying Scope 3 emission objectives. Executives cite logistics cost reduction as the single largest incentive, with 41% prioritizing proximity over global scale. Elevated demand lifts vessel utilization and daily charter rates for 1,500-2,000 TEU ships, translating into a 0.8 percentage-point uptick in the Maritime freight transport market growth trajectory.
Chronic Port-Side Infrastructure Bottlenecks
Congestion peaked in 2025 as Singapore and Colombo absorbed Cape-routed vessels, causing yard utilization to exceed 90% and average berth wait times to triple. Shanghai processed a record 5 million TEU in January 2025 ahead of U.S. tariff enactments, stressing yard equipment even after adding 18 fully automated terminals. Los Angeles and Long Beach struggle with chassis shortages, while the Malacca Strait faces geopolitical disruptions and climate-driven draft limitations. Investment lags in gate automation and hinterland rail links hamper cargo velocity, subtracting 1.1 percentage-points from the Maritime freight transport market's long-run CAGR.
Other drivers and restraints analyzed in the detailed report include:
- EU-ETS on Maritime Emissions Reshapes Fleet Economics
- Digital Freight Platforms Enable Real-Time Capacity Matching
- Oversupply Risk from Record Container-Ship Orderbook 2023-26
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Dry bulk holds the lion's share, accounting for 28.65% of Maritime freight transport market size in 2025 on the back of China's 165 million-ton iron-ore and coal restocking drive. However, a 36 million dwt delivery slate scheduled for 2025 risks dampening TCE rates despite robust tonnage demand growth. Operators therefore pivot to index-linked charters to mitigate downside exposure. Overcapacity fears spur early scrapping of Handysize vessels, constraining supply in niche routes and moderating rate compression.
Liquid bulk is the standout growth engine, posting a 4.02% CAGR through 2031 as LNG liquefaction volumes scale and chemicals trades diversify. Spot VLCC earnings are forecast at USD 51,600 per day for 2025, stimulating time-charter interest among energy majors. Tanker owners install dual-fuel capability to capture green-premium cargoes, while port operators invest in cryogenic export arms to service ammonia-ready tonnage. The strengthening liquid bulk trajectory adds needed diversity to the Maritime freight transport market, cushioning volatility in other cargo streams.
Complete Report Scope:
- By Cargo Type
- Containerized Cargo
- Dry
- Reefer
- Dry Bulk Cargo
- Liquid Bulk Cargo
- General Cargo
- Roll-On/Roll-Off Cargo
- Containerized Cargo
- By End-User Industry
- Electronics & Semiconductors
- Chemicals & Petrochemicals
- Food & Beverage
- Pharmaceuticals & Healthcare
- Retail & E-commerce
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Peru
- Chile
- Argentina
- Rest of South America
- Asia-Pacific
- India
- China
- Japan
- Australia
- South Korea
- South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- Rest of Asia-Pacific
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- BENELUX (Belgium, Netherlands, and Luxembourg)
- NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- Rest of Europe
- Middle East and Africa
- United Arab of Emirates
- Saudi Arabia
- South Africa
- Nigeria
- Rest of Middle East And Africa
- North America
Geography Analysis
Asia-Pacific commands 37.65% of Maritime freight transport market share in 2025 and is set to expand at a 5.02% CAGR to 2031, buoyed by 57% intra-regional trade dependence that diversifies growth away from Western demand cycles. Shanghai's automation blueprint-18 fully unmanned terminals-cuts crane moves per hour variance and sets new benchmarks for berth productivity. China's Pinglu Canal, capable of handling 89 million tons a year by 2026, will reduce inland transit bottlenecks and save USD 725 million annually.
North America confronts a rare 1% contraction in container throughput as tariff realignments and Section 301 levies raise costs on Chinese-built vessels beginning October 2025. Yet Mexico's trade renaissance offers partial offset, with near-shoring catalyzing Gulf feeder services and inland rail upgrades. Europe faces EUR 10 billion (USD 11.03 billion) annual ETS compliance costs that reprioritize corridor routing and bunker strategies. Simultaneously, green-corridor pilots position European ports as early-adoption nodes for alternative-fuel bunkering.
The Middle East leverages USD 4.5 billion in Saudi port investments to lift regional logistics revenue to USD 38.8 billion by 2026. IMEC promises to shorten Asia-Europe transit times by 40% via integrated rail-port linkages, underscoring the region's role in multipolar trade flows. South America capitalizes on its neutral stance; Brazilian soybean exports to China expand under disrupted supply chains. Africa's share gradually rises as Russia-Nigeria services unlock agricultural corridors for BRICS members.
- Mediterranean Shipping Company (MSC)
- A.P. Moller-Maersk
- COSCO Shipping Lines
- Hapag-Lloyd
- Ocean Network Express (ONE)
- Evergreen Marine Corp.
- HMM Co., Ltd.
- Yang Ming Marine Transport
- ZIM Integrated Shipping
- Pacific International Lines (PIL)
- SITC International
- X-Press Feeders
- Matson Inc.
- Swire Shipping
- NYK Line
- K Line
- MOL Logistics
- CMA CGM
- Wan Hai Lines
- Emirates Shipping Line
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in South-South intra-Asian trade corridors
- 4.2.2 Near-shoring drives short-sea feeder demand
- 4.2.3 EU-ETS on maritime emissions reshapes fleet economics
- 4.2.4 Digital freight platforms enable real-time capacity matching
- 4.2.5 Alternative fuels adoption lowers long-term OPEX
- 4.2.6 Suez diversions & Panama expansion boost ton-miles
- 4.3 Market Restraints
- 4.3.1 Chronic port-side infrastructure bottlenecks
- 4.3.2 Oversupply risk from record container-ship orderbook 2023-26
- 4.3.3 Escalating maritime cyber-security threats
- 4.3.4 Inflation-driven bunker price volatility
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of COVID-19 and Geo-Political Events
- 4.8 Porters Five Forces
- 4.8.1 Bargaining Power of Buyers
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Cargo Type
- 5.1.1 Containerized Cargo
- 5.1.1.1 Dry
- 5.1.1.2 Reefer
- 5.1.2 Dry Bulk Cargo
- 5.1.3 Liquid Bulk Cargo
- 5.1.4 General Cargo
- 5.1.5 Roll-On/Roll-Off Cargo
- 5.1.1 Containerized Cargo
- 5.2 By End-User Industry
- 5.2.1 Electronics & Semiconductors
- 5.2.2 Chemicals & Petrochemicals
- 5.2.3 Food & Beverage
- 5.2.4 Pharmaceuticals & Healthcare
- 5.2.5 Retail & E-commerce
- 5.2.6 Others
- 5.3 By Geography
- 5.3.1 North America
- 5.3.1.1 United States
- 5.3.1.2 Canada
- 5.3.1.3 Mexico
- 5.3.2 South America
- 5.3.2.1 Brazil
- 5.3.2.2 Peru
- 5.3.2.3 Chile
- 5.3.2.4 Argentina
- 5.3.2.5 Rest of South America
- 5.3.3 Asia-Pacific
- 5.3.3.1 India
- 5.3.3.2 China
- 5.3.3.3 Japan
- 5.3.3.4 Australia
- 5.3.3.5 South Korea
- 5.3.3.6 South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- 5.3.3.7 Rest of Asia-Pacific
- 5.3.4 Europe
- 5.3.4.1 United Kingdom
- 5.3.4.2 Germany
- 5.3.4.3 France
- 5.3.4.4 Spain
- 5.3.4.5 Italy
- 5.3.4.6 BENELUX (Belgium, Netherlands, and Luxembourg)
- 5.3.4.7 NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- 5.3.4.8 Rest of Europe
- 5.3.5 Middle East and Africa
- 5.3.5.1 United Arab of Emirates
- 5.3.5.2 Saudi Arabia
- 5.3.5.3 South Africa
- 5.3.5.4 Nigeria
- 5.3.5.5 Rest of Middle East And Africa
- 5.3.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Mediterranean Shipping Company (MSC)
- 6.4.2 A.P. Moller-Maersk
- 6.4.3 COSCO Shipping Lines
- 6.4.4 Hapag-Lloyd
- 6.4.5 Ocean Network Express (ONE)
- 6.4.6 Evergreen Marine Corp.
- 6.4.7 HMM Co., Ltd.
- 6.4.8 Yang Ming Marine Transport
- 6.4.9 ZIM Integrated Shipping
- 6.4.10 Pacific International Lines (PIL)
- 6.4.11 SITC International
- 6.4.12 X-Press Feeders
- 6.4.13 Matson Inc.
- 6.4.14 Swire Shipping
- 6.4.15 NYK Line
- 6.4.16 K Line
- 6.4.17 MOL Logistics
- 6.4.18 CMA CGM
- 6.4.19 Wan Hai Lines
- 6.4.20 Emirates Shipping Line
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


