

|
시장보고서
상품코드
2124831
트랜지스터 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Transistor - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
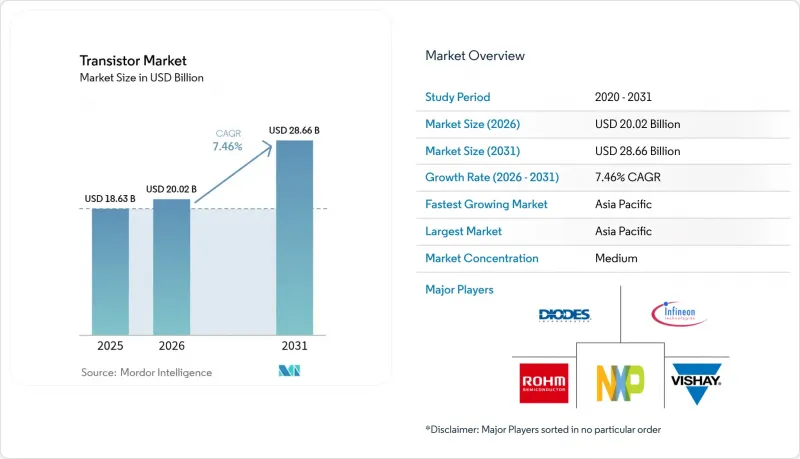
에 의하면, 2026년 트랜지스터 시장 규모는 200억 2,000만 달러로 추정되며, 2025년 186억 3,000만 달러에서 2031년에는 286억 6,000만 달러에 달할 것으로 예측됩니다.
또한 2026-2031년 연평균 성장률(CAGR) 7.46%를 기록할 전망입니다.

본 보고서는 트랜지스터의 유형(바이폴라 접합형 트랜지스터(BJT) 등), 재료(실리콘(Si) 등), 기술 노드(65나노미터 이상 등), 패키지 유형(스루홀, 표면 실장 등), 최종 사용자 산업(소비자 가전, 정보통신기술(ICT) 등) 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 트랜지스터 시장 동향 및 인사이트
저전력 모바일 SoC에 대한 수요 급증
모바일용 시스템 온 칩(SoC) 공급업체들은 배터리 소모 없이 기기에서 추론 작업을 수행할 수 있는 AI 가속기를 통합하기 위해 트랜지스터 수를 늘리고 있습니다. 칩 아키텍처에서는 고성능 로직과 10mW 미만의 대기 전력에 최적화된 아날로그 블록이 융합되어 있으며, 구매 기준은 단가에서 ‘작업당 줄(joule)’로 전환되고 있습니다. TSMC의 3nm 제조 라인은 주로 스마트폰용 SoC를 지원하기 위해 2025년에 양산을 시작했습니다. 이는 노드 전환이 여전히 모바일 워크로드에 뿌리를 두고 있음을 여실히 보여줍니다. 설계자들이 신경망 처리 코어와 전원 관리 회로를 단일 웨이퍼 위에 배치함에 따라, 이종 집적화를 통해 웨이퍼 레벨 패키징의 채택이 촉진되고 있습니다. 전 세계 스마트폰 출하량은 정점에 도달했지만, 기기당 실리콘 사용량 증가로 인해 트랜지스터 시장 전체의 매출 성장세가 유지되고 있습니다.
교통 수단 및 충전 인프라의 급속한 전기화
전기자동차에는 내연 기관 차량에 비해 약 10배의 반도체가 탑재되어 있으며, 그 대부분은 트랙션 인버터, 차량용 충전기, DC-DC 컨버터를 제어하는 대전류 트랜지스터입니다. 업계에서 400V 시스템에서 800V 시스템으로의 전환은 실리콘 소자의 안전 동작 영역을 초과하기 때문에 자동차 제조업체들은 정격 1,200V의 SiC MOSFET 및 IGBT 모듈을 지정하고 있습니다. 도시바의 새로운 300mm 제조 시설은 자동차용 파워 반도체의 생산량을 3배로 늘리는 것을 목표로 하고 있으며, 이는 이러한 장기적인 비즈니스 기회에 대한 공급업체의 대응을 보여줍니다. 공공 급속 충전기의 도입 확대도 추가적인 호재가 되고 있습니다. 각 충전소에는 여러 개의 IGBT 스택과 게이트 드라이버가 내장되어 있기 때문입니다. AEC-Q100 규격 준수를 위해서는 최대 2년이나 되는 설계 주기가 필요하기 때문에 수요 전망과 공급 확보 사이에 지속적인 격차가 발생하고 있으며, 이것이 견조한 가격 형성을 뒷받침하고 있습니다.
3nm 이하 노드에서의 양자 터널링 효과의 한계
3nm 미만의 미세 구조에서는 양자 터널 효과로 인해 허용할 수 없는 수준의 누설 전류가 발생하여, 그동안 노드 미세화를 정당화해 온 에너지 및 지연 시간상의 이점이 훼손되고 있습니다. 게이트 올 어라운드(GAA) 나노시트 트랜지스터는 정전 손실을 부분적으로 경감시키지만, 복잡한 패터닝 절차와 고비용의 EUV 멀티패터닝 공정이 필요합니다. 따라서 각 파운드리 업체들은 순수한 리소그래피 미세화를 추구하는 대신, 게이트 길이의 점진적인 단축과 3D 적층 및 치플릿과 같은 시스템 수준의 혁신을 결합하여 성능 로드맵의 연장을 도모하고 있습니다. 현재 3nm 미만의 마스크 세트 1세트 비용은 1,000만 달러를 초과하기 때문에 금형 비용을 상각할 수 있는 것은 생산량이 가장 많은 소비자용 및 클라우드용 프로세서로 한정됩니다.
부문 분석
세계 IGBT 매출액은 2026-2031년 연평균 성장률(CAGR) 8.66%로 확대될 것으로 예측되며, e-모빌리티 및 재생에너지용 인버터가 고효율 스위칭 부품을 필요로 하고 있기 때문에 트랜지스터 시장 전체의 성장률을 상회할 전망입니다. 기존의 BJT 카테고리는 고속 스위칭이나 극한의 내전압이 필요하지 않은 비용 중심의 소비자용 및 산업용 설계에 대응함으로써 2025년 트랜지스터 시장 규모에서 48.35%의 점유율을 유지했습니다. 각 공급업체들은 웨이퍼 레벨 패키지를 활용하여 스위칭 손실을 경쟁력 있는 수준으로 억제하는 한편, IGBT의 정격 전류를 1,000A 이상으로 높이는 노력을 추진하고 있습니다.
ISO 26262를 포함한 자동차 안전 기준은 확장 미션 프로파일 시험을 의무화함으로써 진입 장벽을 높이고 있으며, 이러한 요인이 프리미엄 가격 책정을 뒷받침하고 업계의 적정한 집중화를 강화하고 있습니다. Nexperia의 GaN 및 SiC 공정에 대한 2억 달러 규모의 투자 확대는 실리콘 IGBT 구조의 내구성 한계를 뛰어넘는 대체 소재를 찾는 고객의 로드맵과 부합합니다. 전계 효과 트랜지스터(FET)는 로직 용도에서 여전히 필수적이지만, 노드 미세화가 둔화되고 스마트폰 및 PC에서 이산 소자의 사용 수가 정점에 도달함에 따라 시장 점유율 확대는 완만한 수준에 그치고 있습니다.
2025년 트랜지스터 시장 점유율에서 실리콘은 68.85%를 유지했으나, 트랙션 인버터,태양광 발전용 인버터, 산업용 드라이브가 스위칭 손실 감소 효과가 높이 평가되는 1,200V 설계로 전환됨에 따라, 실리콘 카바이드(SiC) 소자는 2031년까지 8.86%라는 최고 연평균 성장률(CAGR)을 보일 것으로 전망됩니다. RF 및 급속 충전기의 파워 스테이지 분야에서 갈륨 질화물의 틈새 시장은 확대되고 있지만, 기판 비용과 웨이퍼 수율이 대량 보급의 장벽이 되고 있습니다.
SiC 파일럿 라인을 위한 ‘CHIPS법’에 기반한 전용 보조금 등 정부의 인센티브로 인해 국내 팹의 초기 비용이 경감되고, 결정 성장에 대한 투자 회수 기간이 단축될 것입니다. 그러나 광대역 갭 소재의 웨이퍼 수율은 실리콘보다 20-30퍼센트 포인트 낮아 다이 비용을 상승시키고 있으므로, 그 채택은 성능상의 이점으로 인해 높은 비용이 정당화되는 용도로 제한되고 있습니다. SiC JFET 오디오 앰프의 실험실 검증 결과는 전력 변환 이외의 분야로 적용 범위가 확대되고 있음을 보여주며, 광대역 갭 소재 공급업체에게 향후 다각화의 방향을 시사하고 있습니다.
지역별 분석
아시아태평양은 2025년에 매출의 55.90%를 차지할 것으로 예상되며, 2031년까지 연평균 성장률(CAGR) 10.62%를 나타낼 것으로 전망됩니다. 중국의 국내 파운드리 업체들은 정책 요구에 따라 28nm 및 14nm 라인 확장을 추진하고 있지만, 최첨단 기술의 제약으로 인해 대만 및 한국의 팹에서 조달이 진행되고 있습니다. 인도의 생산 연계형 인센티브 프로그램에 따라 여러 OSAT 기업의 진출이 발표되고 있지만, 물류 및 숙련된 인력 부족으로 인해 여전히 단기적인 생산량이 제한되고 있습니다. 일본은 포토레지스트, 실리콘 웨이퍼, 성막 장비 공급에서 중요한 역할을 유지하고 있으며, 웨이퍼 팹의 생산 능력은 제한적이지만 트랜지스터 시장에서 입지를 유지하고 있습니다. 베트남이나 말레이시아와 같은 신흥 동남아시아 거점은 다국적 기업들이 중국 연안 지역으로부터의 다각화를 추진하는 가운데, 대체 공급원으로서의 선택지로 부상하고 있습니다.
북미는 클라우드 데이터센터의 확장, 전기차 조립 생산의 확대, 그리고 국내 조달을 우선시하는 방위 프로그램의 요건으로부터 혜택을 받고 있습니다. 『CHIPS법』에 따른 520억 달러의 예산 배정으로 TSMC, 삼성,인텔의 여러 팹에 대한 투자가 실현되어 장기적인 공급 안정성이 향상되고 있습니다. 캐나다에서는 5G 인프라와 배터리식 전기 버스에 대한 집중이 RF 디바이스 및 고출력 디바이스에 대한 전문적인 수요를 불러일으키고 있습니다. 한편, 미국 국경과 인접한 멕시코의 EMS 클러스터는 자동차 업계의 1차 공급업체를 대상으로 서비스를 제공하는 트랜지스터 조립 라인을 유치하고 있습니다. 공급망의 회복탄력성을 중시하는 지역 정책은 인건비 및 건설비 급등을 부분적으로 상쇄하는 가격 프리미엄을 뒷받침하고 있습니다.
유럽의 트랜지스터 시장은 독일의 e-모빌리티 전환, 프랑스의 항공우주 부문, 그리고 비효율적인 전력 변환에 벌금을 부과하는 지역 차원의 ‘그린 딜’을 중심으로 전개되고 있습니다. 독일의 각 OEM 기업들은 인버터 로드맵을 안정화하기 위해 SiC 소자를 단독으로 조달하고 있는 반면, 프랑스의 방위 프로그램에서는 가혹한 우주선 환경을 견딜 수 있는 내방사선 트랜지스터가 지정되어 있습니다. 유럽 칩 합작 기업(European Chips Joint Undertaking)은 전략적 자립과 측정 가능한 탄소 발자국 감축이라는 두 가지 목표를 내걸고, 첨단 노드 파일럿 라인에 자금을 지원하고 있습니다. 브렉시트와 관련된 무역 마찰로 인해 영국의 OEM 기업들은 유럽 대륙의 OSAT로부터 조립 부품을 이중 조달하도록 권장받고 있으며, 이는 베네룩스 지역의 현지 공급업체들에게 시장 점유율 확대의 기회가 되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.14According to Mordor Intelligence, the transistor market size in 2026 is estimated at USD 20.02 billion, growing from 2025 value of USD 18.63 billion with 2031 projections showing USD 28.66 billion, growing at 7.46% CAGR over 2026-2031.
This report is Segmented by Transistor Type (Bipolar Junction Transistors (BJT), and More), Material (Silicon (Si), and More), Technology Node (Greater Than Equal To 65 Nm, and More), Packaging Type (Through-Hole, Surface-Mount, and More), End-User Industry (Consumer Electronics, Information and Communication Technology, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Transistor Market Trends and Insights
Surging Demand for Power-Efficient Mobile SoCs
Mobile system-on-chip suppliers are lengthening transistor counts to integrate AI accelerators that execute on-device inference tasks without draining batteries. Chip architectures blend high-performance logic with analog blocks optimized for standby below 10 mW, shifting purchasing criteria from unit price to joules-per-operation. TSMC's 3 nm production lines entered mass production during 2025 mainly to serve smartphone SoCs, underscoring how node migration remains anchored in mobility workloads. Heterogeneous integration is reinforcing wafer-level packaging adoption as designers co-locate neural-processing cores and power-management circuitry on a single substrate. Although global smartphone shipments plateaued, rising silicon per handset is sustaining revenue growth across the transistor market.
Rapid Electrification of Transportation and Charging Infrastructure
Electric vehicles embed roughly 10 times more semiconductors than combustion models, most of which are high-current transistors handling traction inverters, on-board chargers, and DC-DC converters. The industry shift from 400 V to 800 V systems exceeds the safe-operating area of silicon devices, prompting automakers to specify SiC MOSFETs and IGBT modules rated at 1,200 V. Toshiba's new 300 mm facility aims to triple automotive-grade power semiconductor output, illustrating supplier responses to this long-cycle opportunity. Public fast-charger rollouts add further upside, as each station integrates multiple IGBT stacks and gate drivers. Qualification to AEC-Q100 extends design cycles by up to two years, creating a persistent gap between demand visibility and supply availability that underpins healthy pricing.
Quantum-Tunneling Limits Below 3 nm Nodes
Sub-3 nm geometries experience prohibitive leakage due to quantum tunneling, eroding the energy-delay benefit that historically justified node shrinks. Gate-all-around nanosheet transistors partially mitigate electrostatic loss yet demand intricate patterning sequences and expensive EUV multi-patterning steps. Foundries are therefore combining modest gate-length reductions with system-level innovations such as 3D stacking and chiplets to extend performance roadmaps rather than chasing pure lithographic scaling. The cost of a single sub-3 nm mask set now exceeds USD 10 million, meaning only the highest-volume consumer and cloud processors can amortize tooling expenses.
Other drivers and restraints analyzed in the detailed report include:
- AI/ML Inference at the Edge Driving Discrete Power Devices
- 5G-to-6G RF Front-End Upgrades
- Supply-Chain Concentration in Taiwan and South China
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Global IGBT revenue is projected to advance at 8.66% CAGR between 2026 and 2031, outpacing overall transistor market growth as e-mobility and renewable inverters demand high-efficiency switching components. The legacy BJT category retained 48.35% share of the transistor market size in 2025 by serving cost-sensitive consumer and industrial designs that do not need fast switching or extreme voltage tolerance. Suppliers are leveraging wafer-level packages to drive IGBT current ratings beyond 1,000 A while keeping switching loss at competitive levels.
Automotive safety standards, including ISO 26262, elevate barriers to entry by mandating extended mission-profile testing, a factor that supports premium pricing and reinforces moderate industry concentration. Nexperia's USD 200 million expansion into GaN and SiC processes aligns with customer roadmaps seeking alternative materials that can surpass the ruggedness limits of silicon IGBT structures. Field-effect transistors remain indispensable in logic applications, but their share gains are modest as node scaling slows and discrete counts plateau in smartphones and PCs.
Silicon kept 68.85% of the 2025 transistor market share, yet silicon-carbide devices are forecast to log the highest 8.86% CAGR to 2031 as traction inverters, solar inverters, and industrial drives transition to 1,200 V designs that reward lower switching loss. Gallium-nitride's niche in RF and fast-charger power stages is expanding, although substrate cost and wafer yield remain hurdles to mass penetration.
Government incentives, such as dedicated CHIPS Act grants for SiC pilot lines, ease upfront costs for domestic fabs and shorten the payback period on crystal-growth investments. Still, wide-bandgap wafer yields trail silicon by 20-30 percentage points, inflating die cost and confining adoption to applications where performance benefits justify premiums. Lab demonstrations of SiC JFET audio amplifiers highlight the broadening scope beyond power conversion, signaling future diversification paths for wide-bandgap suppliers.
Complete Report Scope:
- By Transistor Type
- Bipolar Junction Transistors (BJT)
- Field Effect Transistors (FET)
- Insulated Gate Bipolar Transistors (IGBT)
- Heterojunction Bipolar Transistors (HBT)
- By Material
- Silicon (Si)
- Silicon Carbide (SiC)
- Gallium Nitride (GaN)
- Germanium (Ge)
- By Technology Node
- Greater than Equal to 65 nm
- 45 - 28 nm
- 22 - 16 nm
- 14 - 10 nm
- Less than 10 nm
- By Packaging Type
- Through-Hole
- Surface-Mount
- Chip-Scale Package (CSP)
- Wafer-Level Package (WLP)
- By End-User Industry
- Consumer Electronics
- Information and Communication Technology
- Automotive and Transportation
- Industrial Manufacturing
- Energy and Power
- Aerospace and Defense
- Healthcare and Medical Devices
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific contributed 55.90% revenue in 2025 and is forecast to record a 10.62% CAGR to 2031. China's domestic foundries are scaling 28 nm and 14 nm lines under policy mandates, yet leading-edge constraints drive procurement from Taiwanese and South Korean fabs. India's production-linked incentive program has attracted multiple OSAT announcements, but logistics and skilled-labor gaps still temper near-term output. Japan maintains a critical role in photoresist, silicon-wafer, and deposition-tool supply, cushioning its transistor market relevance despite limited wafer-fab capacity. Emerging Southeast-Asian hubs such as Vietnam and Malaysia gain as second-source alternatives when multinationals diversify away from coastal China.
North America benefits from cloud-data-center expansion, electric-vehicle assembly growth, and defense-program mandates that prioritize domestic sourcing. The CHIPS Act's USD 52 billion allocation has unlocked multi-fab investments by TSMC, Samsung, and Intel, improving long-term supply security. Canada's focus on 5G infrastructure and battery-electric buses spurs specialized demand for RF and high-power devices, while Mexico's EMS clusters near the U.S. border attract transistor assembly lines that service automotive Tier-1 suppliers. Regional policy emphasis on supply-chain resilience supports a price premium that partially offsets elevated labor and construction costs.
Europe's transistor market gravitates around Germany's e-mobility shift, France's aerospace sector and the region-wide Green Deal that penalizes inefficient power conversion. Germany's OEMs are solo-sourcing SiC devices to stabilize inverter roadmaps, while French defense programs specify radiation-hardened transistors that endure harsh cosmic-ray environments. The European Chips Joint Undertaking funds advanced-node pilot lines with a dual objective: strategic autonomy and measurable carbon-footprint reduction. Brexit-related trade frictions prompt British OEMs to dual-source assemblies from continental OSATs, creating share opportunities for local suppliers in the Benelux corridor.
- onsemi Corporation
- Infineon Technologies AG
- STMicroelectronics N.V.
- Texas Instruments Incorporated
- Vishay Intertechnology, Inc.
- Diodes Incorporated
- NXP Semiconductors N.V.
- Renesas Electronics Corporation
- Linear Integrated Systems, Inc.
- ROHM Co., Ltd.
- Toshiba Electronic Devices and Storage Corporation
- Microchip Technology Inc.
- Broadcom Inc.
- Samsung Electronics Co., Ltd.
- Fuji Electric Co., Ltd.
- Mitsubishi Electric Corporation
- Alpha and Omega Semiconductor Limited
- Qorvo, Inc.
- Wolfspeed, Inc.
- Analog Devices, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging demand for power-efficient mobile SoCs
- 4.2.2 Rapid electrification of transportation and charging infrastructure
- 4.2.3 AI/ML inference at the edge driving discrete power devices
- 4.2.4 5G?to-6G RF front-end upgrades
- 4.2.5 Government incentives for wide-band-gap fabs (SiC, GaN)
- 4.2.6 Adoption of advanced packaging (chip-let, 3D stacking)
- 4.3 Market Restraints
- 4.3.1 Quantum-tunnelling limits below 3 nm nodes
- 4.3.2 Supply-chain concentration in Taiwan and South-China
- 4.3.3 Rising fab construction CAPEX amid talent shortages
- 4.3.4 High qualification cost for automotive-grade devices
- 4.4 Industry Supply Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Transistor Type
- 5.1.1 Bipolar Junction Transistors (BJT)
- 5.1.2 Field Effect Transistors (FET)
- 5.1.3 Insulated Gate Bipolar Transistors (IGBT)
- 5.1.4 Heterojunction Bipolar Transistors (HBT)
- 5.2 By Material
- 5.2.1 Silicon (Si)
- 5.2.2 Silicon Carbide (SiC)
- 5.2.3 Gallium Nitride (GaN)
- 5.2.4 Germanium (Ge)
- 5.3 By Technology Node
- 5.3.1 Greater than Equal to 65 nm
- 5.3.2 45 - 28 nm
- 5.3.3 22 - 16 nm
- 5.3.4 14 - 10 nm
- 5.3.5 Less than 10 nm
- 5.4 By Packaging Type
- 5.4.1 Through-Hole
- 5.4.2 Surface-Mount
- 5.4.3 Chip-Scale Package (CSP)
- 5.4.4 Wafer-Level Package (WLP)
- 5.5 By End-User Industry
- 5.5.1 Consumer Electronics
- 5.5.2 Information and Communication Technology
- 5.5.3 Automotive and Transportation
- 5.5.4 Industrial Manufacturing
- 5.5.5 Energy and Power
- 5.5.6 Aerospace and Defense
- 5.5.7 Healthcare and Medical Devices
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Colombia
- 5.6.2.4 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 South Korea
- 5.6.4.4 India
- 5.6.4.5 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Egypt
- 5.6.5.2.3 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 onsemi Corporation
- 6.4.2 Infineon Technologies AG
- 6.4.3 STMicroelectronics N.V.
- 6.4.4 Texas Instruments Incorporated
- 6.4.5 Vishay Intertechnology, Inc.
- 6.4.6 Diodes Incorporated
- 6.4.7 NXP Semiconductors N.V.
- 6.4.8 Renesas Electronics Corporation
- 6.4.9 Linear Integrated Systems, Inc.
- 6.4.10 ROHM Co., Ltd.
- 6.4.11 Toshiba Electronic Devices and Storage Corporation
- 6.4.12 Microchip Technology Inc.
- 6.4.13 Broadcom Inc.
- 6.4.14 Samsung Electronics Co., Ltd.
- 6.4.15 Fuji Electric Co., Ltd.
- 6.4.16 Mitsubishi Electric Corporation
- 6.4.17 Alpha and Omega Semiconductor Limited
- 6.4.18 Qorvo, Inc.
- 6.4.19 Wolfspeed, Inc.
- 6.4.20 Analog Devices, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


