

|
시장보고서
상품코드
2125609
유럽의 IT 서비스 시장 : 시장 점유율 분석, 산업 동향 및 통계 데이터, 성장 예측(2026-2031년)Europe IT Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 유럽의 IT 서비스 시장 규모는 2025년에 4,787억 2,000만 달러로 평가되었고, 2026년에 4,902억 2,000만 달러로 추정되고, 2031년까지 6,750억 8,000만 달러에 이를 것으로 예측되며, 2026-2031년 CAGR 6.61%로 성장할 전망입니다.
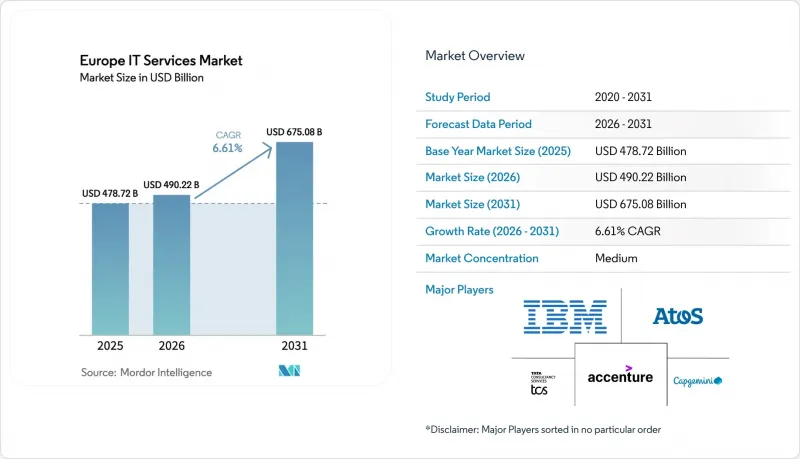
본 보고서는 서비스 유형별(IT 컨설팅·구현, IT 아웃소싱 등), 기업 규모별(중소기업, 대기업), 도입 모델별(온쇼어, 니어쇼어, 오프쇼어), 최종 사용자 산업별(은행, 금융서비스 및 보험(BFSI), 제조업, 정부 기관, 의료, 소매, 통신 등) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러)으로 표시되어 있습니다.
유럽의 IT 서비스 시장 동향 및 인사이트
기업 전반에 걸친 클라우드 전환의 급증
NIS2 지침에 따라 중요 사업자에게 대체 처리 사이트 유지가 의무화됨에 따라 클라우드 도입이 급증했습니다. 이에 따라 멀티클라우드를 통한 중복성은 단순한 모범 사례가 아닌 법적 요건이 되었습니다. 독일의 제조 기업들은 기밀성이 높은 워크로드를 Gaia-X 준수 소버린 클라우드로 이전하는 한편, 중요도가 낮은 데이터는 전 세계 하이퍼스케일러에 보관하고 있습니다. ‘디지털 디케이드(Digital Decade)’ 프로그램은 2030년까지 유럽 기업의 클라우드 이용률을 75%로 끌어올리는 것을 목표로 하고 있으며, 리프트 앤 시프트(Lift-and-Shift) 및 현대화 프로젝트의 파이프라인을 유지하고 있습니다. SAP의 전문 지식과 컨테이너 기반 마이크로서비스를 결합할 수 있는 벤더들이 대규모 변혁 프로젝트를 수주하고 있습니다. 또한 멀티클라우드의 복잡성 증가는 FinOps, 가시성(Observability), 클라우드 간 보안 게이트웨이에 대한 후속 수요를 창출하여 장기적인 매니지드 서비스 수익을 강화하고 있습니다.
EU 전역의 사이버 위협 대응 지침을 배경으로 한 매니지드 보안으로의 전환
NIS2 지침에 따라 2025년 1월, 규제 대상 조직의 범위가 약 2,000개 조직에서 16만 개 조직 이상으로 확대되었습니다. 24시간 이내 침해 보고 의무 및 공급망 위험 매핑으로 인해 사내 보안 팀은 과도한 부담을 떠안게 되었고, 구매자들은 24시간 SOC 모니터링 및 제로 트러스트 설계를 제공할 수 있는 관리형 보안 서비스 제공업체(MSSP)를 찾고 있습니다. 프랑스의 ANSSI와 독일의 BSI가 발행한 산업별 지침에 따라 입찰 사양이 표준화되고, 조달 프로세스의 모호성이 해소되며, 계약 체결이 가속화되었습니다. 정액제 ‘컴플라이언스 애즈 어 서비스(Compliance as a Service)’ 패키지는 최고정보보안책임자(CISO)를 두지 않은 중견 기업들로부터 지지를 얻고 있으며, 일회성 감사를 예측 가능한 구독형 서비스로 전환하고 있습니다.
주요 서비스 제공 거점에서의 인력 부족과 임금 상승
유로스타트(Eurostat)의 기록에 따르면, 2025년에는 50만 건의 ICT 관련 채용 공고가 채워지지 않을 것이며, 독일 개발자의 급여 중앙값은 전년 대비 8.2% 상승하여 니어쇼어(nearshore)의 비용 우위가 사라지고 있습니다. 폴란드와 루마니아에서 9%에 달하는 급격한 임금 상승은 저인플레이션 시대에 체결된 고정 가격 계약에 묶여 있는 공급업체들을 압박하고 있습니다. 북미로의 인재 유출이 인력 부족을 더욱 심화시키고 있어, 서비스 제공업체들은 생성형 AI 챗봇을 활용한 1단계 지원 자동화를 강요당하고 있으며, 수익성이 높은 컨설팅 업무를 우선시할 수밖에 없는 상황입니다. 그러나 이러한 임시방편은 구조적인 인력 부족을 부분적으로만 보완할 뿐이며, 유럽 IT 서비스 시장의 성장 가능성을 저해하고 있습니다.
부문 분석
2025년에는 클라우드 및 플랫폼 서비스가 유럽 IT 서비스 시장의 33.74% 점유율을 차지했으나, 매니지드 보안 서비스는 2031년까지 연평균 성장률(CAGR) 6.72%를 기록하며 성장 순위 1위를 차지하고 있습니다. NIS2 및 DORA에 기반한 위협 모니터링 의무화로 인해 연중무휴 24시간 SOC(보안 운영 센터) 체제가 경영진 수준의 관심사가 되었으며, 선택적이었던 보안 시범 프로젝트가 필수적인 운영 비용으로 전환되고 있습니다. ERP 도입 및 클라우드 전환에 지속적인 규정 준수 점검을 통합하는 벤더들은 시장 점유율을 서서히 확대되고 있습니다.
컨설팅 및 도입 관련 수익은 SAP S/4HANA로의 전환, CSRD와 관련된 ESG 플랫폼 구축, 그리고 유럽 헬스 데이터 스페이스(European Health Data Space)와의 통합에 의해 뒷받침되고 있습니다. 로보틱 프로세스 자동화(RPA) 및 AI를 활용한 문서 추출 기술이 백오피스 업무의 계약 형태를 재구성함에 따라, ITO(IT 아웃소싱)와 BPO(비즈니스 프로세스 아웃소싱)의 경계가 점차 모호해지고 있는 반면,확장형 감지 및 대응(EDR) 플랫폼의 보급으로 인해 보안 지출은 경계 방어에서 예측형 위협 감지로 전환되고 있습니다.
대기업은 수년에 걸친 세계 지원 계약 덕분에 2025년 매출의 60.36%를 차지했으나, 중소기업은 2031년까지 연평균 성장률(CAGR) 6.96%의 궤도에 올라 있습니다. EU의 ‘디지털 데케이드(Digital Decade)’ 기금과 독일의 ‘Digital Now’ 보조금은 대상 클라우드 비용의 최대 50%를 지원하여 도입 장벽을 낮추고 있습니다. 사전 구성된 SaaS 번들은 도입 주기를 단축하지만, 시스템 연동, 데이터 마이그레이션, 사이버 보안 태세 평가에는 여전히 외부 전문 지식이 필요하며, 이로 인해 모듈형 서비스 카탈로그의 비즈니스 기회가 확대되고 있습니다.
또 다른 성장 동력은 컨설팅 주도의 ‘디지털 성숙도’ 진단입니다. 이를 통해 공공 보조금을 활용할 수 있게 되며, 각국의 바우처 제도에서 이미 인증받은 솔루션 제공업체에 대한 지출이 촉진됩니다. 이로 인해 초기 도입 작업 외에도 지속적인 자문 업무의 기회가 창출됩니다.
기타 혜택 :
- Excel 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 분석 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장률 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the Europe IT services market size is projected to be USD 478.72 billion in 2025, USD 490.22 billion in 2026 and reach USD 675.08 billion by 2031, growing at a CAGR of 6.61% from 2026 to 2031.
This report is Segmented by Service Type (IT Consulting and Implementation, IT Outsourcing, and More), Enterprise Size (Small and Medium Enterprises and Large Enterprises), Deployment Model (Onshore, Nearshore, and Offshore), End-User Vertical (BFSI, Manufacturing, Government, Healthcare, Retail, Telecom, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Europe IT Services Market Trends and Insights
Surging Enterprise-Wide Cloud Migration
Cloud adoption jumped after the NIS2 Directive obliged essential entities to maintain alternate processing sites, making multi-cloud redundancy a legal necessity rather than a best practice. German industrial firms are moving sensitive workloads to Gaia-X-aligned sovereign clouds while keeping non-critical data on global hyperscalers. The Digital Decade program targets 75% cloud usage among European companies by 2030, sustaining a pipeline of lift-and-shift and modernization projects. Vendors able to combine SAP expertise with container-based microservices are winning large transformation mandates. Multi-cloud complexity also unlocks follow-on demand for FinOps, observability, and inter-cloud security gateways, strengthening long-term managed-services revenues.
Shift to Managed Security Amid EU-Wide Cyber-Threat Directives
The NIS2 Directive expanded the scope of regulated entities from roughly 2,000 to more than 160,000 organizations in January 2025. Mandatory 24-hour breach reporting and supply-chain risk mapping overloaded in-house security teams, pushing buyers toward Managed Security Service Providers that can deliver round-the-clock SOC monitoring and zero-trust design. Sector guides from France's ANSSI and Germany's BSI standardized tender specifications, cutting procurement ambiguity and accelerating deal closure. Fixed-fee "compliance-as-a-service" bundles appeal to mid-market firms that lack chief information-security officers, converting ad-hoc audits into predictable subscriptions.
Talent Scarcity and Wage Inflation in Key Delivery Hubs
Eurostat recorded 500,000 unfilled ICT posts in 2025 and median developer pay in Germany rose 8.2% year-on-year, eroding nearshore cost advantages. Wage spikes of 9% in Poland and Romania squeezed vendors locked into fixed-price contracts signed during the low-inflation era. Brain drain toward North America compounds shortages, forcing providers to automate tier-1 support through generative-AI chatbots and prioritize high-margin advisory work. These stopgaps, however, only partly offset the structural talent gap, trimming Europe IT services market growth potential.
Other drivers and restraints analyzed in the detailed report include:
- Corporate Urgency to Modernize SAP and Legacy ERP Before 2027 Support Sunset
- EU CSRD-Linked ESG-Reporting Services Boosting Consulting Demand
- Geopolitical Data-Sovereignty Barriers (Schrems II, AI Act)
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Managed Security Services sits atop growth rankings with a 6.72% CAGR to 2031 even though Cloud and Platform Services controlled a 33.74% Europe IT services market share in 2025. Mandatory threat-monitoring duties under NIS2 and DORA make 24x7 SOC coverage a board-level concern, converting discretionary security pilots into non-negotiable opex. Vendors that embed continuous compliance checks into ERP rollouts and cloud migrations capture incremental wallet share.
Consulting and Implementation revenue is buoyed by SAP S/4HANA conversions, CSRD-linked ESG platform buildouts, and European Health Data Space integrations. ITO and BPO lines are converging as robotic process automation and AI-driven document extraction reshape back-office deals, while Extended Detection and Response platforms push security spending from perimeter defense into predictive threat hunting.
Large Enterprises generated 60.36% of 2025 revenue thanks to multi-year global support deals, yet Small and Medium Enterprises are on course for a 6.96% CAGR through 2031. EU Digital Decade funds and Germany's Digital Now grants cover up to 50% of eligible cloud costs, lowering adoption hurdles. Pre-configured SaaS bundles shorten deployment cycles, but integrations, data migration and cyber-posture assessments still require external expertise, expanding opportunity for modular service catalogs.
A secondary growth lever is consultancy-led "digital maturity" diagnostics, which unlock public subsidies and channel spend toward solution providers already accredited under national voucher schemes. This creates recurring advisory assignments alongside initial implementation work.
Complete Report Scope:
- By Service Type
- IT Consulting and Implementation
- IT Outsourcing (ITO)
- Business Process Outsourcing (BPO)
- Managed Security Services
- Cloud and Platform Services
- By Enterprise Size
- Small and Medium Enterprises (SMEs)
- Large Enterprises
- By Deployment Model
- Onshore Delivery
- Nearshore Delivery
- Offshore Delivery
- By End-User Vertical
- BFSI
- Manufacturing
- Government and Public Sector
- Healthcare and Life-Sciences
- Retail and Consumer Goods
- Telecom and Media
- Logistics and Transport
- Energy and Utilities
- Other End-User Verticals
- By Country
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Europe
List of Companies Covered in this Report:
- Accenture plc
- Capgemini SE
- IBM Consulting
- Atos SE
- Tata Consultancy Services Ltd
- Cognizant Technology Solutions Corp.
- Infosys Ltd
- Wipro Ltd
- CGI Inc.
- Sopra Steria Group SA
- DXC Technology Co.
- NTT DATA Europe and LATAM
- Tietoevry Oyj
- EVRYTHNG Group AB
- Fujitsu Services Ltd
- Orange Business Services
- Swisscom Ltd (Enterprise Services)
- Telefonica Tech
- GFT Technologies SE
- Reply SpA
- Endava plc
- Luxoft (DXC Technology)
- Kyndryl Holdings Inc.
- HCLTech Ltd
- NCC Group plc
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging Enterprise-Wide Cloud Migration
- 4.2.2 Demand For Cost-Optimised ITO And BPO Contracts
- 4.2.3 Shift To Managed Security Amid EU-Wide Cyber-Threat Directives
- 4.2.4 AI-Driven Vendor-Selection Platforms Accelerating Outsourcing
- 4.2.5 Corporate Urgency To Modernise SAP And Legacy ERP Before 2027 Support Sunset
- 4.2.6 EU CSRD-Linked ESG-Reporting Services Boosting Consulting Demand
- 4.3 Market Restraints
- 4.3.1 Talent Scarcity And Wage Inflation In Key Delivery Hubs
- 4.3.2 Geopolitical Data-Sovereignty Barriers (Schrems II, AI Act)
- 4.3.3 Prolonged Client-Decision Cycles Owing To Macro-Uncertainty
- 4.3.4 Rising Carbon-Footprint Penalties On Energy-Intensive Data Centres
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Industry Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 IT Consulting and Implementation
- 5.1.2 IT Outsourcing (ITO)
- 5.1.3 Business Process Outsourcing (BPO)
- 5.1.4 Managed Security Services
- 5.1.5 Cloud and Platform Services
- 5.2 By Enterprise Size
- 5.2.1 Small and Medium Enterprises (SMEs)
- 5.2.2 Large Enterprises
- 5.3 By Deployment Model
- 5.3.1 Onshore Delivery
- 5.3.2 Nearshore Delivery
- 5.3.3 Offshore Delivery
- 5.4 By End-User Vertical
- 5.4.1 BFSI
- 5.4.2 Manufacturing
- 5.4.3 Government and Public Sector
- 5.4.4 Healthcare and Life-Sciences
- 5.4.5 Retail and Consumer Goods
- 5.4.6 Telecom and Media
- 5.4.7 Logistics and Transport
- 5.4.8 Energy and Utilities
- 5.4.9 Other End-User Verticals
- 5.5 By Country
- 5.5.1 United Kingdom
- 5.5.2 Germany
- 5.5.3 France
- 5.5.4 Italy
- 5.5.5 Spain
- 5.5.6 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level overview, Market-level overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Accenture plc
- 6.4.2 Capgemini SE
- 6.4.3 IBM Consulting
- 6.4.4 Atos SE
- 6.4.5 Tata Consultancy Services Ltd
- 6.4.6 Cognizant Technology Solutions Corp.
- 6.4.7 Infosys Ltd
- 6.4.8 Wipro Ltd
- 6.4.9 CGI Inc.
- 6.4.10 Sopra Steria Group SA
- 6.4.11 DXC Technology Co.
- 6.4.12 NTT DATA Europe and LATAM
- 6.4.13 Tietoevry Oyj
- 6.4.14 EVRYTHNG Group AB
- 6.4.15 Fujitsu Services Ltd
- 6.4.16 Orange Business Services
- 6.4.17 Swisscom Ltd (Enterprise Services)
- 6.4.18 Telefonica Tech
- 6.4.19 GFT Technologies SE
- 6.4.20 Reply SpA
- 6.4.21 Endava plc
- 6.4.22 Luxoft (DXC Technology)
- 6.4.23 Kyndryl Holdings Inc.
- 6.4.24 HCLTech Ltd
- 6.4.25 NCC Group plc
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


