

|
시장보고서
상품코드
2154521
표면 개질 화학제품 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Surface Modification Chemicals - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
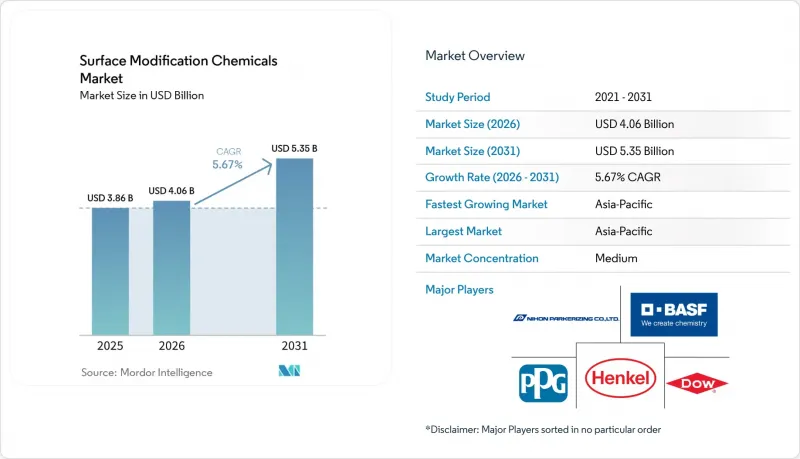
에 따르면 표면 개질용 화학제품 시장 규모는 2025년에 38억 6,000만 달러로 추정되며, 2026년 40억 6,000만 달러에서 2031년까지 53억 5,000만 달러로 확대되어, 예측 기간(2026-2031년) 동안 CAGR은 5.67%에 달할 것으로 전망됩니다.
전 세계 표면 개질용 화학제품 시장의 동향 및 인사이트
전기자동차(EV)의 경량화 및 다금속 전처리 : 바디 인 화이트(Body-in-White) 분야의 화학 기술 혁신
전기자동차 바디 인 화이트 제조에서는 고장력강, 알루미늄 합금, 마그네슘 다이캐스팅, 유리섬유 강화 플라스틱이 단일 조립 라인에서 결합됩니다. 이러한 조합으로 인해 표면 개질 화학제품 시장에서 화학 약품을 교체하지 않고도 단일 처리 탱크에서 서로 다른 기판에 대응할 수 있는 전처리 시스템에 대한 수요가 증가하고 있습니다. 지르코늄-실란계 하이브리드 변환 피막은 인산아연 처리보다 이러한 요건을 더 효과적으로 충족시킵니다. 이러한 처리는 더 낮은 온도에서 수행되며 인산염 슬러지 발생량도 적어, 자동차 업계의 1차 공급업체의 폐기물 처리 업무를 경감시킵니다. BASF Coatings 산하의 Chemetall사는 2025년 10월, 전기자동차 배터리용 구리박을 위한 크롬 및 불소 무함유 패시베이션 기술인 ‘Gardolene D’를 출시했습니다. 보고된 시험 조건 하에서, 25°C에서 1,000회의 충방전 사이클 후, 이 제품은 배터리 수명을 최대 6% 연장했습니다.
EU의 배터리 규정에 따르면, 2027년 이후 디지털 배터리 여권 및 유해 물질 신고가 의무화됩니다. 이러한 요건으로 인해 전기자동차 배터리 공급망 전반에 걸쳐 크롬 프리 표면 처리 기술에 대한 수요가 증가하고 있습니다. 이에 따라 각 OEM 업체들은 다중 금속 대응 라인의 개조 및 인산아연 시스템의 폐지를 가속화하고 있습니다. 이로 인해 단기적인 설비 투자는 범용 세정제 제조사가 아닌 실란 및 지르코늄계 변환제 공급업체로 향하게 될 것입니다. 표면 개질용 화학약품 시장에서는 공급업체가 혼합 금속의 성능 요건과 공식적인 화학제품 공개 요건을 모두 충족할 수 있는 경우 혜택을 받게 될 것입니다. 이미 자동차 생산 라인의 전환을 지원하고 있는 공급업체는 배터리 소재 처리가 차량 조립 요건과 더욱 밀접하게 연계됨에 따라 그 입지를 강화할 수 있을 것입니다.
전자 제품의 소형화 및 정밀 도금 : 5nm 미만이 화학적 특이성을 주도
5nm 이하의 반도체 공정 노드에서는 첨단 패키징의 각 표면 처리 단계에서 더 높은 순도와 더 많은 화학 약품의 투입이 요구됩니다. 이로 인해 구리 실리콘 관통 비아(TSV)의 메탈라이제이션 및 마이크로 범프 형성을 위한 표면 개질 화학 약품 시장이 뒷받침될 것입니다. 웨이퍼 레벨 패키징에는 10억 분의 1 이하의 정밀도로 일관성을 유지하는 서프레서, 레벨러, 브라이트너가 필요합니다. 칩렛 스택 내의 단일 실리콘 관통 비어에 결함이 발생하면 모듈 전체가 작동하지 않을 가능성이 있으므로, 화학 약품의 사양은 단순한 일상적인 비용 판단이 아닌 성능 요구 사항이 됩니다. 아미노실란 및 HMDS 기반의 접착 촉진제는 첨단 로직 및 메모리 제조를 위한 극자외선(EUV) 리소그래피의 기초 화학 분야에서 여전히 중요한 역할을 하고 있습니다.
애리조나주, 오하이오주, 텍사스주에서 ‘미국 CHIPS 및 과학법’의 지원을 받아 진행되고 있는 팹 확장으로 인해 2028년까지 웨이퍼 기반 생산능력이 증강되며, 신규 시설에서 고순도 공정용 화학제품에 대한 수요가 발생하고 있습니다. 2025년에 발표된 연구에서는 대규모 언어 모델(LLM) 에이전트를 활용하여 전기도금욕의 자율적 최적화가 입증되었습니다. 이 에이전트는 니켈 박막 증착을 위한 전류 밀도, 온도, 첨가제 농도를 선택함으로써, 첨단 시설에서 정밀한 도금 제어가 어떻게 개발될 수 있는지를 보여주었습니다. 또한, 5G의 확산에 따라 고전력 밀도 작동 조건에서 밀리미터파 주파수 대역에서 유전 안정성을 유지해야 하는 인쇄회로기판용 알콕시실란 개질 에폭시 수지에 대한 수요도 뒷받침되고 있습니다. 이러한 요건으로 인해 표면 개질용 화학약품 시장은 칩 패키징과 통신 하드웨어 모두에서 중요한 역할을 담당하게 될 것입니다.
6가 크롬 재인증 및 규정 준수 비용 : REACH 전환에 따른 불확실성
2025년 4월, 유럽화학제품청(ECHA)은 EU의 REACH 규정(EC No. 1907/2006)에 따라 13종의 6가 크롬 화합물에 대한 제한안을 공표했습니다. 이 제안에서는 영향을 받는 유럽 산업계의 규정 준수 비용을 대체 프로그램, 근로자 노출 관리, 그리고 시설 폐쇄 가능성 등을 포함하여 3억 1,400만 유로(약 3억 6,380만 달러)에서 32억 3,000만 유로(약 37억 4,000만 달러)로 추산하고 있습니다. 기존 REACH 부속서 XIV에 따른 승인 결정은 화학제품 사용자에게 더 이상 신뢰할 수 있는 계획 수립 도구가 되지 못하고 있습니다. 이는 법정 3개월 기간에 비해 승인 절차에 평균 14.5개월이 소요되기 때문입니다. 이로 인해 화학제품 교체 및 관련 설비 투자를 관리하는 조달 팀의 확실성이 저하되고 있으며, 결과적으로 표면 개질용 화학제품 시장에서 구매 결정이 지연될 가능성이 있습니다.
‘항공우주·방위용 크로메이트 재인가 컨소시엄’에 가입한 항공우주·방위 분야 사용자들은 2034년 12월까지 계속 사용 허가를 연장하는 승인을 획득하여, 전환 관리를 위한 시간을 확보했습니다. 이러한 컨소시엄에 가입하지 않은 중소 규모의 자동차 및 일반 산업 사용자들은 더욱 시급한 규정 준수 대응을 요구받고 있으며, 표면 처리 연구팀은 신제품 개발이 아닌 규제 관련 기록 작성 및 재인증 작업에 시간을 할애할 수밖에 없는 상황에 처해 있습니다. 이러한 상황은 확립된 규제 대응 자원을 보유한 대규모 다국적 배합 제조업체에 유리하게 작용하여, 표면 개질용 화학제품 시장의 업계 재편을 촉진할 가능성이 있습니다.
부문 분석
접착 촉진제는 2026년부터 2031년까지 연평균 성장률(CAGR) 6.45%로 확대될 것으로 예측되며, 가장 빠르게 성장하는 화학제품 유형이 될 것입니다. 이들은 자동차 차체 패널, 소비자용 전자기기 케이스, 구조용 어셈블리 등 접착이 어려운 폴리머 기판에 사용됩니다. 기존의 기계적 처리 방식으로는 요구되는 공차 범위 내에서 내구성 있는 계면 결합을 항상 확보할 수 있는 것은 아닙니다. 자동차 제조업체들이 저표면 에너지 폴리프로필렌 및 열가소성 폴리올레핀(TPO)의 사용을 확대함에 따라, 염소화 폴리올레핀 및 실란 개질 프라이머 시스템의 채택이 증가하고 있습니다. 2024년 연구에 따르면, 폴리올레핀용 공유 결합형 접착 프라이머는 플라즈마 처리된 기판에 대해 중첩 전단 강도를 10%에서 50%까지 향상시키며, 2개월간 보관 후에도 그 효과를 유지하는 것으로 밝혀졌습니다. 이러한 내구성은 조립 라인에서 사용할 때 분명한 의미를 갖습니다.
2025년, 실란 커플링제는 표면 개질용 화학약품 시장의 34.56%를 차지했습니다. 이러한 위상은 타이어와 필러의 접착, 첨단 인쇄회로기판 라미네이트, 자동차 및 산업용 부식 방지 전처리 등 폭넓은 기능성을 반영한 것입니다. 또한, 코팅 시스템이 용제형에서 수성형으로 전환됨에 따라 계면활성제 및 습윤제 시장도 확대되고 있습니다. 에보닉(Evonik)은 2025년 4월, 기존 습윤제에서는 보관 중에 효과가 상실될 가능성이 있는 수성 및 방사선 경화형 배합을 위해 ‘TEGO Wet 288’을 출시했습니다. 변환제, 에칭제, 산화제는 인산아연에서 지르코늄계 나노 변환층으로 전환되고 있습니다. 2025년 조사에서는 한 자동차용 도료 시설에서 12일 만에 인산계에서 지르코늄계로의 완전한 전환이 확인되었습니다.
지역별 분석
아시아태평양은 2025년 표면 개질용 화학제품 시장의 42.13%를 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 6.85%로 성장할 것으로 예측됩니다. 이 지역에는 반도체 제조, 자동차 조립 및 소비자용 전자기기 제조의 주요 거점이 있습니다. 중국은 산업 정책에서 전략적 전자부품 원자재의 자급자족을 중시하고 있어, 자동차 도장 라인을 인산염 기반에서 지르코늄 전환 전처리로 전환하는 동시에 국내 실란 및 특수 화학제품 공급을 확대하고 있습니다. 일본과 한국은 반도체 공정 및 디스플레이 패널 생산 분야에서 고순도 소재에 대한 프리미엄 수요를 주도하고 있습니다. 베트남, 태국, 말레이시아에서는 기업들이 공급망 다각화를 추진하는 가운데, 전자기기 조립 분야에 대한 투자가 유치되고 있습니다.
인도는 ‘생산 연계형 인센티브(PLI)’ 제도에 기반한 전자기기 조립 및 패키징 투자를 통해 새로운 수요 거점으로 발전하고 있습니다. 인도의 표면 처리용 화학약품 수요는 현재 대부분 수입에 의존하고 있으나, 현지에서의 혼합 능력도 서서히 갖춰지기 시작하고 있습니다. 일본, 미국, 독일산 고순도 배합 제품은 향후 수년간 계속해서 중요한 역할을 할 것입니다. 북미는 두 번째로 큰 지역 시장으로, 항공우주용 코팅, 첨단 반도체용 특수 화학약품, 자동차 OEM용 전처리 분야에서 고부가가치 수요가 있습니다. 애리조나주, 오하이오주, 텍사스주에 신설된 팹은 고순도 접착 촉진제, 도금 첨가제, 컨버전 화학약품에 대한 수요를 뒷받침하며, 표면 개질 화학약품 시장의 지역적 기반을 확대하고 있습니다.
유럽에서는 자동차, 항공우주, 해상 풍력발전 각 부문에서 규제에 따른 크롬 및 PFAS 무함유 제품에 대한 수요가 있습니다. REACH와 관련된 Cr(VI) 규정 준수 및 대체 프로그램 또한 생산 라인 전환에 비용을 발생시켜 지출 증가를 억제하는 요인이 될 수 있습니다. 남미는 여전히 소규모 시장이지만, 브라질과 아르헨티나에서는 자동차 화이트 바디 전처리 및 산업용 유지보수용 코팅에 대한 수요를 뒷받침하고 있습니다. 중동 및 아프리카에서는 사우디아라비아의 산업 다각화 프로그램과 지역 내 파이프라인 및 업스트림 석유 인프라 개발을 배경으로 수요가 증가하고 있습니다. 많은 지역 하위 시장에서 제품의 가용성보다 유통 네트워크의 역량이 여전히 주요 제약요인으로 작용하고 있어, 표면 개질 화학제품 시장에 진출하는 기업들에게는 현지 서비스망 구축이 중요해지고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
- 조사 가정과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 가치 및 공급망 분석
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 화학제품 유형별
- 기판 재료별
- 용도별
- 지역별
- 아시아태평양
- 중국
- 인도
- 일본
- 한국
- ASEAN 국가
- 기타 아시아태평양 국가
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 북유럽 국가
- 기타 유럽 국가
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 중동 및 아프리카
- 사우디아라비아
- 남아프리카공화국
- 기타 중동 및 아프리카 국가
- 아시아태평양
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율·순위 분석
- 기업 개요
- ALTANA
- BASF
- Dow
- Element Solutions Inc
- Evonik Industries AG
- Henkel AG and Co. KGaA
- JCU CORPORATION
- Lamberti S.p.A.
- Momentive
- Nihon Parkerizing Co., Ltd.
- NOF CORPORATION
- PPG Industries, Inc.
- Quaker Chemical Corporation
- Shin-Etsu Chemical Co., Ltd.
- Wacker Chemie AG
제7장 시장 기회와 향후 전망
KSM 26.10.29According to Mordor Intelligence, the surface modification chemicals market size was estimated at USD 3.86 billion in 2025 and is estimated to grow from USD 4.06 billion in 2026 to USD 5.35 billion by 2031, at a CAGR of 5.67% during the forecast period (2026-2031).
Global Surface Modification Chemicals Market Trends and Insights
EV Lightweighting and Multi-Metal Pretreatment: The Body-in-White Chemistry Shift
Electric vehicle body-in-white construction combines high-strength steel, aluminum alloys, magnesium die-castings, and glass-fiber-reinforced polymers on a single assembly line. This mix supports demand in the surface modification chemicals market for pretreatment systems that can handle different substrates in a single bath without chemistry changeovers. Zirconium-silane hybrid conversion coatings manage this requirement more effectively than zinc phosphating. They operate at lower temperatures and produce less phosphate sludge, which reduces waste-treatment work for automotive Tier 1 facilities. Chemetall, part of BASF Coatings, launched Gardolene D in October 2025 as a chromium-free and fluoride-free passivation technology for EV battery copper foils. The product delivered up to 6% longer battery life after 1,000 charge cycles at 25°C under the reported testing conditions.
The EU Battery Regulation requires digital battery passports and hazardous-substance declarations from 2027. These requirements increase the need for chromium-free surface chemistry across EV battery supply chains. OEMs are therefore moving more quickly to retrofit multi-metal lines and retire zinc-phosphate systems. This directs near-term capital spending toward silane and zirconium conversion chemical suppliers rather than commodity cleaning formulators. The surface modification chemicals market benefits where suppliers can meet both mixed-metal performance requirements and formal chemical disclosure needs. Suppliers that already support automotive line conversion can strengthen their position as battery material processing becomes more closely tied to vehicle assembly requirements.
Electronics Miniaturization and Precision Plating: Sub-5 nm Drives Chemistry Specificity
Semiconductor process nodes below 5 nm require higher purity and greater chemical input at every surface-treatment stage in advanced packaging. This supports the surface modification chemicals market for copper through-silicon-via metallization and micro-bump formation. Wafer-level packaging requires suppressors, levelers, and brighteners with sub-parts-per-billion consistency. A defect in a single through-silicon via within a chiplet stack can disable the entire module, making chemical specification a performance requirement rather than a routine cost decision. Aminosilane- and HMDS-based adhesion promoters remain important in the underlayer chemistry of extreme ultraviolet (EUV) lithography for advanced logic and memory production.
U.S. CHIPS and Science Act-supported fab expansions in Arizona, Ohio, and Texas are adding wafer-start capacity through 2028, creating demand for high-purity processing chemistries at new facilities. Research published in 2025 demonstrated autonomous optimization of an electroplating bath using a large language model (LLM) agent that selected current density, temperature, and additive concentration for nickel thin-film deposition, illustrating how precision plating control can be developed in advanced facilities. The 5G rollout also supports demand for alkoxysilane-modified epoxy resins in printed circuit boards that must retain dielectric stability at millimeter-wave frequencies under power-dense operation. These requirements give the surface modification chemicals market a role in both chip packaging and communications hardware.
Hexavalent Chromium Requalification and Compliance Costs: REACH Transition Uncertainty
In April 2025, the European Chemicals Agency published a restriction proposal for 13 hexavalent chromium compounds under the EU REACH Regulation EC No. 1907/2006. The proposal estimated compliance costs of EUR 314 million (~USD 363.80 million) to EUR 3.23 billion (~USD 3.74 billion) for affected European industries, covering substitution programs, worker exposure controls, and potential facility closures. Existing REACH Annex XIV authorization decisions have become less reliable planning tools for chemical users, with authorization processing averaging 14.5 months, compared with a statutory three-month period. This has reduced certainty for procurement teams managing chemistry changeovers and associated capital spending, which, in turn, can slow purchasing decisions in the surface-modification chemicals market.
Aerospace and defense users within the Aerospace and Defense Chromates Re-Authorization Consortium secured authorizations extending continued-use titles until December 2034, providing more time to manage the transition. Smaller automotive and general-industrial users outside such consortium arrangements face more immediate compliance needs, with surface-treatment research teams required to devote time to regulatory records and requalification work rather than new product development. This situation favors larger multinational formulators with established regulatory resources and may drive consolidation in the surface modification chemicals market.
Other drivers and restraints analyzed in the detailed report include:
- Infrastructure Corrosion Protection and Offshore Wind Expansion: Scale Drives Demand
- Chromium-Free and Low-VOC Formulation Innovation: Compliance as a Product Catalyst
- Specialty Raw-Material Price Volatility: Silicon Metal and Feedstock Concentration Risk
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Adhesion promoters are forecast to expand at a 6.45% CAGR from 2026 to 2031, making them the fastest-growing chemical type. They are used on difficult-to-bond polymer substrates in automotive body panels, consumer electronics housings, and structural assemblies. Conventional mechanical preparation cannot always provide durable interfacial bonds at the required tolerances. Chlorinated polyolefin and silane-modified primer systems are gaining use as automakers increase the use of low-surface-energy polypropylene and thermoplastic polyolefin (TPO). A 2024 study found that a covalent-bonding adhesion primer for polyolefins increased lap shear strength by 10% to 50% against plasma-treated substrates and remained effective after two months of storage. This durability has clear implications for assembly-line use.
Silane coupling agents accounted for 34.56% of the surface modification chemicals market share in 2025. Their position reflects functional versatility across tire-filler bonding, advanced printed circuit board laminates, and corrosion-inhibiting pretreatment for automotive and industrial applications. Surface-active and wetting agents are also expanding as coating systems shift from solventborne to waterborne formats. Evonik launched TEGO Wet 288 in April 2025 for waterborne and radiation-curing formulations where conventional wetting agents can lose effectiveness during storage. Conversion, etching, and oxidation chemicals are moving from zinc phosphate to zirconium-based nano-conversion layers. A 2025 study documented a complete phosphate-to-zirconium conversion at an automotive paint facility in 12 days.
Complete Report Scope:
- By Chemical Type
- Silane Coupling Agents
- Adhesion Promoters
- Surface-Active and Wetting Agents
- Conversion, Etching and Oxidation Chemicals
- Other Surface Modification Chemicals
- By Substrate Material
- Metals
- Plastics and Polymers
- Glass and Ceramics
- Composites
- Other Substrate Materials
- By Application
- Paints and Coatings
- Adhesives and Sealants
- Electronics and Semiconductors
- Automotive and Transportation Components
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 42.13% of the surface modification chemicals market share in 2025 and is forecast to grow at a 6.85% CAGR through 2031. The region has large bases for semiconductor fabrication, automotive assembly, and consumer electronics manufacturing. China is transitioning automotive coating lines from phosphate-based to zirconium-conversion pretreatment and expanding domestic silane and specialty chemical supply, as industrial policy emphasizes self-sufficiency in strategic electronics inputs. Japan and South Korea contribute premium demand for high-purity materials in semiconductor processing and display panel production. Vietnam, Thailand, and Malaysia are attracting investment in electronics assembly as companies diversify their supply chains.
India is developing as another demand center through investments in electronics assembly and packaging under the Production Linked Incentive scheme. Its surface-treatment chemical requirements are currently met largely through imports, although localized blending capacity is beginning to develop. High-purity formulations from Japan, the United States, and Germany will remain important for several years. North America is the second-largest regional market, with high-value demand in aerospace coatings, advanced semiconductor specialty chemicals, and automotive OEM pretreatment. New fabs in Arizona, Ohio, and Texas are supporting demand for high-purity adhesion promoters, plating additives, and conversion chemicals, broadening the regional base for the surface modification chemicals market.
Europe has regulation-driven demand for chromium- and PFAS-free products in the automotive, aerospace, and offshore wind sectors. REACH-related Cr(VI) compliance and substitution programs also create costs for line conversions and can restrain spending growth. South America remains a smaller market, with Brazil and Argentina supporting demand for automotive body-in-white pretreatment and industrial maintenance coatings. The Middle East and Africa are seeing increased demand driven by Saudi Arabia's industrial diversification programs and regional pipeline and upstream oil infrastructure development. In many regional submarkets, distribution-network capability, rather than product availability, remains the primary limitation, making local service coverage important for participants in the surface modification chemicals market.
- ALTANA
- BASF
- Dow
- Element Solutions Inc
- Evonik Industries AG
- Henkel AG and Co. KGaA
- JCU CORPORATION
- Lamberti S.p.A.
- Momentive
- Nihon Parkerizing Co., Ltd.
- NOF CORPORATION
- PPG Industries, Inc.
- Quaker Chemical Corporation
- Shin-Etsu Chemical Co., Ltd.
- Wacker Chemie AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 EV Lightweighting and Multi-Metal Pretreatment
- 4.2.2 Electronics Miniaturization and Precision Plating
- 4.2.3 Infrastructure Corrosion Protection and Offshore Wind Expansion
- 4.2.4 Additive Manufacturing Surface Finishing
- 4.2.5 Closed-Loop, AI-Controlled Bath Management
- 4.2.6 Chromium-Free and Low-VOC Formulation Innovation
- 4.3 Market Restraints
- 4.3.1 Hexavalent Chromium Requalification and Compliance Costs
- 4.3.2 Specialty Raw-Material Price Volatility
- 4.3.3 Captive-Line Total Cost and Waste-Management Burden
- 4.3.4 Qualification Gaps for Bio-Based and Nanostructured Alternatives
- 4.4 Value and Supply-Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Chemical Type
- 5.1.1 Silane Coupling Agents
- 5.1.2 Adhesion Promoters
- 5.1.3 Surface-Active and Wetting Agents
- 5.1.4 Conversion, Etching and Oxidation Chemicals
- 5.1.5 Other Surface Modification Chemicals
- 5.2 By Substrate Material
- 5.2.1 Metals
- 5.2.2 Plastics and Polymers
- 5.2.3 Glass and Ceramics
- 5.2.4 Composites
- 5.2.5 Other Substrate Materials
- 5.3 By Application
- 5.3.1 Paints and Coatings
- 5.3.2 Adhesives and Sealants
- 5.3.3 Electronics and Semiconductors
- 5.3.4 Automotive and Transportation Components
- 5.3.5 Other Applications
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 NORDIC Countries
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 ALTANA
- 6.4.2 BASF
- 6.4.3 Dow
- 6.4.4 Element Solutions Inc
- 6.4.5 Evonik Industries AG
- 6.4.6 Henkel AG and Co. KGaA
- 6.4.7 JCU CORPORATION
- 6.4.8 Lamberti S.p.A.
- 6.4.9 Momentive
- 6.4.10 Nihon Parkerizing Co., Ltd.
- 6.4.11 NOF CORPORATION
- 6.4.12 PPG Industries, Inc.
- 6.4.13 Quaker Chemical Corporation
- 6.4.14 Shin-Etsu Chemical Co., Ltd.
- 6.4.15 Wacker Chemie AG
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


