

|
시장보고서
상품코드
2154736
패시베이션용 화학제품 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Passivation Chemicals - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
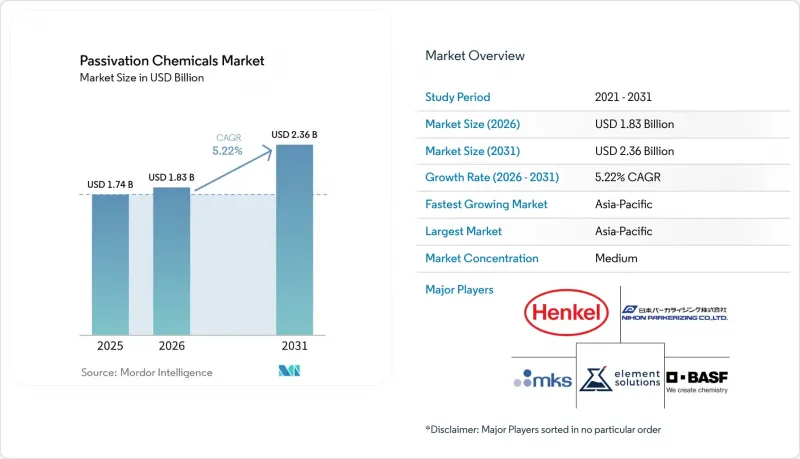
에 따르면 패시베이션용 화학제품 시장 규모는 2025년에 17억 4,000만 달러로 평가되며, 2026년 18억 3,000만 달러에서 2031년까지 23억 6,000만 달러에 달할 것으로 예측되며, 예측 기간(2026-2031년) 동안 CAGR은 5.22%가 될 전망입니다.
전 세계 패시베이션용 화학제품 시장의 동향 및 인사이트
스테인리스강 및 합금 부품에 대한 부식 방지 요건
스테인리스강은 식품, 의약품 및 산업용 장비 분야에서 여전히 중요한 역할을 하고 있으며, 이에 따라 부품의 전체 수명주기 동안 패시베이션은 공급업체의 적격성 요건에 포함됩니다. 미국 재료시험협회(ASTM)의 규격 A967(2025년판)에서는 질산법 5종과 구연산법 5종을 포함한 총 10종의 처리 방법이 규정되어 있습니다. 또한, 이 표준에서는 황산구리 시험, 염수 분무 시험, 고습도 노출 시험 등을 통한 검증도 요구하고 있습니다. 이러한 관리 기준에 따라, 가혹한 사용 환경에서 예측 가능한 내식성이 필요한 구매자에게 있어 표면 처리의 성능은 중요한 요소가 되고 있습니다. 식품 가공, 의약품 제조, 석유·가스 인프라 각 분야에서는 긴 수명이 요구되는 스테인리스강 설비가 계속해서 사용되고 있습니다. 이에 따라 패시베이션용 화학제품 시장에는 안정적인 수요 기반이 확보되어 있는 반면, 화학 조성은 폐기물을 줄이고 고객의 사양을 충족하는 배합으로 전환되고 있습니다. 그러나 이러한 변화로 인해 확립된 검증 방법의 필요성이 사라지는 것은 아닙니다. 구매자는 여전히 자사의 재료 등급, 사용 조건 및 문서화된 품질 요건에 부합하는 처리를 필요로 하기 때문입니다.
EV의 경량화 및 배터리 케이스 보호
전기자동차 배터리 팩에는 저밀도, 열전도성, 내식성을 겸비한 알루미늄 케이스가 사용되고 있습니다. 알루미늄 케이스는 동등한 강철 케이스에 비해 최대 50% 가벼워 차량의 주행 거리 목표 달성에 기여하고 있습니다. 또한, 배터리 팩에는 버스바, 냉각판, 체결 부품 등 이종 금속 접합부가 포함되어 있으며, 이러한 부위에서는 갈바닉 부식을 방지하기 위해 전기화학적 조건에 대해 검증된 처리가 요구됩니다. BASF는 Chemetall을 통해 2025년 10월, 전기자동차용 구리박을 위한 크롬 및 불화물 무첨가 패시베이션 솔루션을 발표했습니다. 이 회사에 따르면, Gardolene D로 처리된 배터리는 25°C에서 1,000회 충방전 후, 6가 크롬 처리 대비 최대 6% 더 긴 수명을 달성했다고 합니다. 따라서 중국, 유럽, 북미에서의 전기자동차 생산 확대는 패시베이션 처리제 시장에서 알루미늄용 처리에 대한 수요를 뒷받침하는 요인이 되며, 공급업체는 배터리 어셈블리에서 볼 수 있는 다양한 합금, 접합부 및 작동 조건에서 이러한 처리가 유효함을 입증해야 합니다.
유해 산 취급 및 폐수 규제 준수에 따른 비용
질산에 의한 패시베이션 처리에서는 질소산화물 연기가 발생할 가능성이 있어, 전용 환기 설비와 관리된 취급이 필요합니다. 또한, 사용 후 처리액에는 용해된 금속이 포함되어 있을 수 있으므로, 미국 환경보호청(EPA)의 요건에 따라 배출 전에 처리를 수행해야 합니다. EPA가 제안한 2026년판 ‘다부문 일반 허가(Multi-Sector General Permit)’에는 산업 폐수의 방류 및 관련 규정 준수 의무에 대해 규정되어 있습니다. 직업안전보건청(OSHA)의 ‘위험 정보 전달 기준’에서는 위험 정보 전달, 개인보호구 및 근로자 교육에 관한 요건이 추가되었습니다. 구연산은 공정 재인증이 가능한 경우 폐기 처리 부담을 줄일 수 있지만, 기존 질산 처리 라인에는 설비 투자나 새로운 승인이 필요할 수 있습니다. 이러한 비용은 소규모 금속 가공 업체들이 패시베이션용 화학제품 시장에서 대체 화학제품을 채택하는 속도를 제한할 가능성이 있으며, 특히 기존 고객의 도면에 질산 처리가 지정되어 있어 다른 공정을 채택하기 위해 고객의 새로운 승인이 필요한 경우 그 부담은 더욱 커집니다.
부문 분석
2025년, 질산은 패시베이션용 화학제품 시장에서 35.23%의 점유율을 차지했습니다. 이러한 위상은 확립된 항공우주 분야의 인증 문서, 기존의 산업용 도면 및 OEM(주문자 상표 제조업체)의 공정 기준을 반영한 것입니다. 2025년 5월 SAE International이 발행한 AMS 2700G에서는 관련 항공우주 분야의 패시베이션 절차에서 질산이 ‘방법 1’로 기재되었습니다. 인산은 산도가 낮아 기판의 부식을 방지할 수 있기 때문에 특수 알루미늄 및 연질 합금 용도에 사용됩니다. 그 밖의 제품 유형으로는 전기자동차 배터리 및 전자기기 용도에 사용되는 독자적인 산화제 혼합물과 크로메이트 프리 시스템 등이 있습니다. 따라서 제품 구성은 서서히 변화하고 있지만, 인증된 용도에서는 기존의 화학 성분이 여전히 중요한 역할을 하고 있습니다.
구연산은 2026년부터 2031년까지 연평균 성장률(CAGR) 6.34%로 시장이 확대될 것으로 예측됩니다. 구연산의 채택은 성능 특성뿐만 아니라 환경에 대한 배려도 반영하고 있습니다. ASTM A967 시험 조건 하에서 구연산 처리는 질산 처리보다 높은 크롬 대 철 표면 비율을 실현할 수 있습니다. 이러한 관계는 식품 장비, 선박용 금속 부품, 제약 가공 등 염화물에 노출되는 용도에서 중요합니다. 또한 구연산은 질소산화물 발생을 방지하고 클린룸 문서화를 지원하기 때문에 임플란트 제조에도 사용되고 있습니다. 스코프 3 배출량 감축을 공약한 주요 제조사들은 폐기물 발생을 줄이는 배합에 더욱 주목하고 있습니다.
지역별 분석
아시아태평양은 2025년 패시베이션용 화학제품 시장 규모의 39.71%를 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 6.48%로 확대될 것으로 예측됩니다. 중국의 양쯔강 삼각주, 주강 삼각주 및 보하이 경제권에는 자동차, 전자기기, 항공우주 부품의 제조 거점이 집중되어 있습니다. 인도에서는 ‘생산 연계형 인센티브(PLI) 제도’에 따른 자동차 부품 생산 확대가 1차 공급업체들의 표면 처리 투자를 유도하며 수요를 견인하고 있습니다. 또한, 인도의 상용 MRO(유지보수·수리·정비) 부문도 AMS 2700을 준수하는 패시베이션 역량을 구축하고 있습니다. 일본과 한국은 반도체 등급의 가공 및 첨단 전자기기용 상호연결 기술에 기여하고 있습니다.
베트남, 태국, 인도네시아를 포함한 동남아시아 국가들은 전자기기 및 자동차 부품의 새로운 제조 거점으로 부상하고 있습니다. 이러한 분야에 대한 외국인 직접 투자는 표면 처리 공정에 대한 수요 증가로 이어지고 있습니다. 북미와 유럽은 확립된 항공우주 및 의료기기 생산 거점이 있기 때문에 패시베이션 약품 시장에서 규제 준수가 더욱 엄격한 지역입니다. 북미의 항공우주 공급업체들은 AMS 2700G 인증을 획득한 약품을 사용하고 있는 반면, 의료기기 제조업체들은 미국 식품의약국(FDA)의 지침에 따라 약품의 추적성을 강화하고 있습니다. 미국 환경보호청(EPA)이 제안한 2026년판 ‘다부문 일반 허가(Multi-Sector General Permit)’는 미국 내 산업 폐수 관리에 대한 더욱 적극적인 노력을 뒷받침하는 것입니다.
유럽의 ‘화학제품의 등록, 평가, 허가 및 제한(REACH)’ 및 ‘유해물질 사용 제한(RoHS)’ 요건은 6가 크롬의 단계적 폐지를 촉진하고 있습니다. 독일, 프랑스, 이탈리아는 유럽의 핵심 소비 기반을 형성하고 있으며, 이 지역에서는 자동차 OEM과의 인증 관계가 화학제품 선정에 영향을 미치고 있습니다. 남미, 중동 및 아프리카에서는 자동차 조립, 석유·가스 인프라, 금속 가공과 관련된 수요 기반이 확대되고 있습니다. 브라질은 상파울루주 및 미나스제라이스주에서의 자동차 조립, 농업 관련 장비, 산업 제조를 통해 남미의 수요를 뒷받침하고 있습니다. 남아프리카공화국은 해당 하위 지역에서 산업 다각화가 가장 잘 이루어진 시장이며, 자동차 조립 수요는 국제적인 OEM 품질 기준을 준수하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
- 조사 가정과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 밸류체인 분석
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 제품 유형별
- 적용 재료별
- 최종 이용 산업별
- 지역별
- 아시아태평양
- 중국
- 인도
- 일본
- 한국
- ASEAN 국가
- 기타 아시아태평양 국가
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 북유럽 국가
- 기타 유럽 국가
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 중동 및 아프리카
- 사우디아라비아
- 남아프리카공화국
- 기타 중동 및 아프리카 국가
- 아시아태평양
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율·순위 분석
- 기업 개요
- Asterion LLC
- BASF
- Birchwood Laboratories LLC
- Brulin
- Delmet srl
- Element Solutions Inc
- Henkel AG & Co. KGaA
- Hubbard-Hall Inc.
- JAYCO Chemical Solutions
- MKS Inc.
- Nihon Parkerizing Co., Ltd.
- Poligrat GmbH
- Quaker Houghton
- TIB Chemicals AG
제7장 시장 기회와 향후 전망
KSM 26.10.29According to Mordor Intelligence, the passivation chemicals market size was valued at USD 1.74 billion in 2025 and is estimated to grow from USD 1.83 billion in 2026 to reach USD 2.36 billion by 2031, at a CAGR of 5.22% during the forecast period (2026-2031).
Global Passivation Chemicals Market Trends and Insights
Corrosion-Control Requirements for Stainless Steel and Alloy Components
Stainless steel remains important in food-grade, pharmaceutical, and industrial equipment, which places passivation within supplier qualification requirements across the component lifecycle. American Society for Testing and Materials (ASTM) A967, updated in its 2025 edition, sets out 10 treatment methods, including 5 nitric acid and 5 citric acid methods. The standard also requires verification through tests such as copper sulfate, salt spray, and high-humidity exposure. These controls make surface treatment performance relevant to buyers who need predictable corrosion resistance in demanding service environments. Food processing, pharmaceutical production, and oil and gas infrastructure continue to use stainless steel equipment with long service-life requirements. This gives the passivation chemicals market a stable base of demand while the chemistry mix shifts toward formulations that reduce waste and meet customer specifications. The shift does not remove the need for established verification methods, because buyers still need treatments that fit their material grades, operating conditions, and documented quality requirements.
EV Lightweighting and Battery-Enclosure Protection
Electric vehicle battery packs use aluminum enclosures because aluminum combines low density, thermal conductivity, and corrosion resistance. Aluminum enclosures can weigh up to 50% less than comparable steel enclosures, supporting vehicle-range objectives. Battery packs also contain dissimilar-metal joints, including busbars, cooling plates, and fasteners, where galvanic corrosion requires treatments validated for electrochemical conditions. BASF, through Chemetall, introduced a chromium-free and fluoride-free passivation solution for electric vehicle copper foils in October 2025. The company reported that batteries treated with Gardolene D achieved up to 6% longer life after 1,000 cycles at 25 °C than hexavalent chromium treatments. Expanding electric vehicle output in China, Europe, and North America, therefore, supports demand for aluminum-compatible treatments in the passivation chemicals market, and suppliers must also demonstrate that these treatments work across the varied alloys, joints, and operational conditions found in battery assemblies.
Hazardous-Acid Handling and Wastewater Compliance Costs
Nitric acid passivation can generate nitrogen oxide fumes, which require dedicated ventilation and controlled handling. Spent treatment baths can also contain dissolved metals that require treatment before discharge under U.S. Environmental Protection Agency (EPA) requirements. The EPA's proposed 2026 Multi-Sector General Permit addressed industrial stormwater discharges and related compliance obligations. The Occupational Safety and Health Administration Hazard Communication Standard adds requirements for hazard communication, personal protective equipment, and worker training. Citric acid can reduce disposal burdens where process requalification is feasible, but existing nitric acid lines may require capital investment and new approvals. These costs can limit the pace at which smaller metal fabricators adopt alternative chemistries within the passivation chemicals market, and the burden is particularly relevant where existing customer drawings specify nitric acid treatment and a different process needs fresh customer approval.
Other drivers and restraints analyzed in the detailed report include:
- Medical-Device Biocompatibility and Implantable-Alloy Demand
- Aerospace Production, MRO and Certified Surface Treatment
- Qualification Time for Substituting Established Chemistries
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Nitric acid held 35.23% of the passivation chemicals market share in 2025. Its position reflected established aerospace qualification documents, legacy industrial drawings, and original equipment manufacturer (OEM) process standards. AMS 2700G, issued by SAE International in May 2025, listed nitric acid as Method 1 for relevant aerospace passivation procedures. Phosphoric acid serves specialized aluminum and softer-alloy applications where lower acidity helps avoid substrate attack. Other product types include proprietary oxidizing blends and chromate-free systems used in electric vehicle battery and electronics applications. The product mix is therefore changing gradually, while established chemistries retain a role in certified applications.
Citric acid is projected to advance at a 6.34% CAGR from 2026 to 2031. Its adoption reflects performance characteristics as well as environmental considerations. Citric acid treatment can provide a higher chromium-to-iron surface ratio than nitric acid treatment under ASTM A967 test conditions. This relationship is relevant in chloride-exposed uses such as food equipment, marine hardware, and pharmaceutical processing. Citric acid is also used in implant manufacturing because it avoids nitrogen oxide fumes and supports cleanroom documentation. Large manufacturers with Scope 3 emissions commitments are placing greater attention on formulations that reduce waste streams.
Complete Report Scope:
- By Product Type
- Nitric Acid
- Citric Acid
- Phosphoric Acid
- Other Product Types
- By Application Material
- Stainless Steel
- Aluminum
- Titanium
- Other Application Materials
- By End-Use Industry
- Automotive
- Aerospace
- Medical Devices
- Electronics
- Other End-Use Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 39.71% of the passivation chemicals market size in 2025 and is projected to advance at a 6.48% CAGR through 2031. China's Yangtze River Delta, Pearl River Delta, and Bohai Economic Rim contain concentrations of automotive, electronics, and aerospace component manufacturing. India is driving demand because automotive component expansion under the Production-Linked Incentive scheme is attracting Tier-1 surface treatment investment. India's commercial MRO sector is also building AMS 2700-compliant passivation capability. Japan and South Korea contribute to semiconductor-grade processing and advanced electronics interconnects.
Southeast Asian countries, including Vietnam, Thailand, and Indonesia, are becoming additional manufacturing locations for electronics and automotive components. Foreign direct investment in these activities adds incremental demand for surface treatment processes. North America and Europe are more compliance-intensive areas of the passivation chemicals market because of their established aerospace and medical device production bases. North American aerospace suppliers use AMS 2700G-certified chemistry, while medical device manufacturers are strengthening chemistry traceability in response to Food and Drug Administration guidance. The EPA's proposed 2026 Multi-Sector General Permit supports greater attention to industrial wastewater management in the United States.
European requirements under Registration, Evaluation, Authorisation and Restriction of Chemicals (REACH) and Restriction of Hazardous Substances (RoHS) have supported the phaseout of hexavalent chromium. Germany, France, and Italy form a core European consumption base, where automotive OEM qualification relationships influence chemistry selection. South America, and Middle East and Africa are expanding demand bases tied to automotive assembly, oil and gas infrastructure, and metal fabrication. Brazil supports South American demand through vehicle assembly, agribusiness equipment, and industrial manufacturing in Sao Paulo and Minas Gerais. South Africa is the most industrially diversified market in its sub-region, with vehicle assembly demand aligned with international OEM quality standards.
- Asterion LLC
- BASF
- Birchwood Laboratories LLC
- Brulin
- Delmet srl
- Element Solutions Inc
- Henkel AG & Co. KGaA
- Hubbard-Hall Inc.
- JAYCO Chemical Solutions
- MKS Inc.
- Nihon Parkerizing Co., Ltd.
- Poligrat GmbH
- Quaker Houghton
- TIB Chemicals AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Corrosion-Control Requirements for Stainless Steel and Alloy Components
- 4.2.2 Aerospace Production, MRO and Certified Surface Treatment
- 4.2.3 EV Lightweighting and Battery-Enclosure Protection
- 4.2.4 Medical-Device Biocompatibility and Implantable-Alloy Demand
- 4.2.5 Electronics Miniaturization and High-Purity Metal Processing
- 4.3 Market Restraints
- 4.3.1 Hazardous-Acid Handling and Wastewater Compliance Costs
- 4.3.2 Qualification Time for Substituting Established Chemistries
- 4.3.3 Raw-Material Price Volatility and Supply Disruption
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Nitric Acid
- 5.1.2 Citric Acid
- 5.1.3 Phosphoric Acid
- 5.1.4 Other Product Types
- 5.2 By Application Material
- 5.2.1 Stainless Steel
- 5.2.2 Aluminum
- 5.2.3 Titanium
- 5.2.4 Other Application Materials
- 5.3 By End-Use Industry
- 5.3.1 Automotive
- 5.3.2 Aerospace
- 5.3.3 Medical Devices
- 5.3.4 Electronics
- 5.3.5 Other End-Use Industries
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 NORDIC Countries
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Asterion LLC
- 6.4.2 BASF
- 6.4.3 Birchwood Laboratories LLC
- 6.4.4 Brulin
- 6.4.5 Delmet srl
- 6.4.6 Element Solutions Inc
- 6.4.7 Henkel AG & Co. KGaA
- 6.4.8 Hubbard-Hall Inc.
- 6.4.9 JAYCO Chemical Solutions
- 6.4.10 MKS Inc.
- 6.4.11 Nihon Parkerizing Co., Ltd.
- 6.4.12 Poligrat GmbH
- 6.4.13 Quaker Houghton
- 6.4.14 TIB Chemicals AG
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


