

|
시장보고서
상품코드
2124166
유럽의 레저용 차량 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Europe Recreational Vehicle - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 유럽 레저용 차량(RV) 시장 규모는 2025년 333억 8,000만 달러에서 2026년에는 370억 7,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 11.08%로 성장을 지속하여, 2031년에는 626억 9,000만 달러에 이를 것으로 예측됩니다.
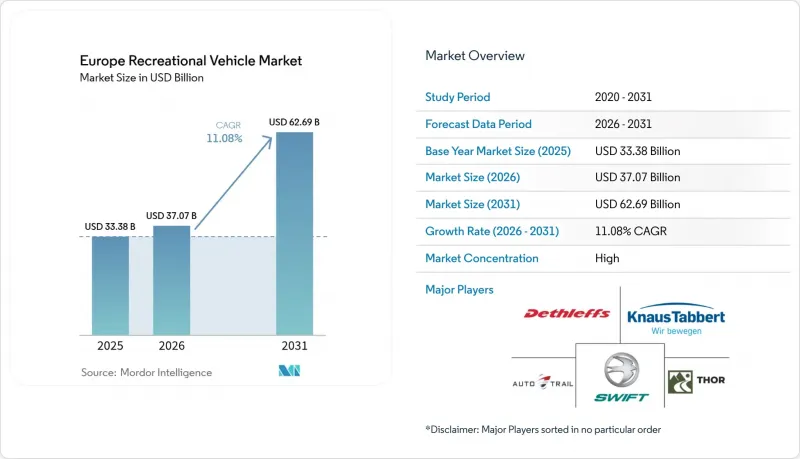
본 보고서는 유형(견인식 RV, 모터홈), 추진 방식 및 연료(디젤 내연기관, 가솔린 내연기관, 하이브리드 전기, 배터리 전기),소유 형태(개인 소유자, 렌탈 및 공유 차량), 판매 채널(OEM 프랜차이즈 딜러 등), 국가(독일, 영국 등)별로 분류되어 있습니다. 시장 전망은 금액(달러) 및 판매 대수(대)로 제시되어 있습니다.
유럽 레저용 차량 시장 동향 및 인사이트
팬데믹 이후 국내 및 유럽 내 관광의 급증
유럽의 캠핑 활동은 전례 없는 수준에 도달했으며, 독일에서는 2024년에 4,290만 박의 캠핑 숙박 건수가 기록되어, 이는 팬데믹 이전인 2019년과 비교해 19.9% 증가한 수치입니다. 이러한 국내 관광의 지속적인 증가는 유럽의 여가 선호도에 근본적인 변화가 있음을 반영하며, 근거리 여행은 팬데믹 당시의 필요성에서 선호하는 라이프스타일 선택지로 진화하고 있습니다. 이러한 추세는 독일에만 국한되지 않고, 노르웨이의 캠핑장에서도 숙박객 수가 증가하고 있으며 전년 대비 현저한 성장세를 보이고 있습니다. 2025년에 들어서도 캠핑 활동의 높은 수준이 지속되고 있는 것은 이것이 일시적인 팬데믹에 따른 행동이 아니라 구조적인 수요임을 시사합니다. 특히, 과거 수준과 비교했을 때 독일의 숙박객 수 중 캠핑이 큰 비중을 차지하고 있다는 점이 그 근거가 됩니다. 이러한 관광의 재편은 도시 근교 탐방을 가능하게 하는 소형 캠핑카부터 장기 국내 여행에 적합한 대형 모터홈에 이르기까지, 모든 차종 부문에서 RV 수요에 지속적인 호재를 가져오고 있습니다.
RV 공유 및 렌탈 플랫폼의 급속한 확대
유럽의 RV 공유 생태계는 빠르게 성숙하고 있습니다. 이 부문의 성장 가속화는 2025년 4월 Roadsurfer가 Avellinia Capital로부터 3,000만 유로의 자금 조달에 성공했으며, 특히 차량 대수를 8,500대에서 1만 대로 확대하는 데 이 자금이 사용되었습니다는 사실에서도 분명하게 드러납니다. 이러한 자금 투자는 P2P(개인 간) RV 플랫폼이 초기 신뢰의 장벽을 극복하고 사업 규모를 확대했다는 점을 기관 투자자들이 인정한 것을 반영합니다. 특히 주목할 점은 플랫폼이 동유럽으로 확장되고 있다는 것입니다. Ruuts는 API 연동을 통해 동유럽 시장을 타겟으로 하고 있으며, 유럽 주요 국가의 RV 접근성을 제공함으로써 그동안 서비스가 미치지 못했던 지역을 공략하고 있습니다. 공유 경제가 RV 소유 형태에 스며들면서 두 가지 시장 효과가 나타나고 있습니다. 그것은 처음 이용하는 사용자에 대한 접근성을 민주화하는 동시에, 개인 소유주에게 이용 기반의 수익원을 창출하여 기존의 소유 모델을 넘어선 잠재 시장을 효과적으로 확대하고 있다는 점입니다.
높은 초기 구매 비용과 보험료
유럽의 RV 가격은 급등하고 있어, 모든 시장 세분화에서 구매 부담이 증가하고 있습니다. 이러한 가격 상승은 밸류체인의 혼란, 섀시 부족, 그리고 팬데믹으로 인한 수요를 배경으로 제조업체들이 가격을 인상하고 있기 때문입니다. 또한, 재취득 가격의 상승과 전문적인 수리 수요로 인해 보험료가 급등하고 있는 점도 경제적 부담을 더욱 가중시키고 있습니다. 중산층 구매자들은 중고차나 렌탈을 선택하는 경향이 강해지는 반면, 젊은 층이나 첫 구매자들은 진입 장벽에 직면하고 있어, 수요가 견조함에도 불구하고 시장 성장은 제한되고 있습니다. 재고 조정이 이루어지더라도 높은 수준을 유지하는 가격은 구조적인 비용 인플레이션을 여실히 드러내고 있으며, 시장 접근성을 유지하기 위해서는 소득 증가나 대안적인 소유 모델이 필수적입니다.
부문 분석
2025년, 모터홈은 유럽 레저용 차량 시장에서 53.72%의 점유율을 차지하며 여전히 지배적인 위치를 유지했습니다. 이는 외부 의존 없이 종합적인 설비를 제공하는 자립형 이동식 주거 솔루션을 유럽 소비자들이 선호하고 있음을 반영합니다. 이 부문이 주도적인 위치를 차지하는 것은 이동의 제약보다 편안함과 편의성을 우선시하는 55세에서 75세 사이의 부유층에게 지지를 받고 있기 때문입니다. 한편, 캠핑밴은 2031년까지 연평균 성장률(CAGR)이 11.62%로 가장 빠른 성장세를 보이고 있으며, 이는 ‘밴 라이프’ 문화를 받아들이는 젊은 층과 유연한 업무·여행 솔루션을 추구하는 도시 지역의 전문직 계층에 의해 주도되고 있습니다. 여행용 트레일러와 피프스 휠 트레일러는 규모는 작지만 안정적인 틈새 시장을 차지하고 있으며, 일상적인 사용을 위해 견인 차량을 별도로 보유하기를 선호하는 소비자들에게 지지를 받고 있습니다. 팝업식이나 접이식 캠핑카는 엔트리 레벨 부문을 형성하고 있으며, 가격에 민감한 구매자나 계절적으로 이용하는 이용자들을 끌어모으고 있습니다.
규제 환경 또한 이러한 세분화의 진화를 뒷받침하고 있으며, 규정 2018/858에 기반한 EU의 형식 인증 체계는 안전 기준을 유지하면서 캠핑카로의 개조를 용이하게 하는 다단계 차량 인증을 위한 명확한 로드맵을 제공합니다. 클래스 A 모터홈은 프리미엄 가격대를 차지하고 있지만, 도시 지역의 저배출 구역 규제로 인해 역풍에 직면한 반면, 클래스 B 캠핑카는 도시 접근성 향상 및 주차 유연성 증대라는 이점을 누리고 있습니다.
2025년 현재, 유럽의 레저용 차량 시장에서 디젤 내연기관(ICE) 파워트레인은 91.10%의 점유율을 차지하고 있으며, 이는 이 부문이 전통적으로 대형 차량 용도에서 디젤의 뛰어난 토크 특성과 연비 효율에 의존해 왔음을 반영합니다. 가솔린 내연기관(ICE) 모델은 주로 중량 제약으로 인해 가솔린 엔진이 적합한 경량 캠핑카 용도에서 비교적 낮은 점유율을 유지하고 있습니다. 그러나 EU의 배기가스 규제 강화와 충전 인프라 확충을 배경으로, 배터리식 전기차(BEV) 모델은 2031년까지 연평균 성장률(CAGR) 36.91%로 급성장하고 있습니다. 하이브리드 전기차는 과도기적인 위치를 차지하고 있으며, 주행 거리에 대한 불안을 가진 소비자에게 타협안을 제시하는 동시에, 도심 접근 시 배기가스 감축이라는 이점도 제공합니다.
노르웨이는 승용차 부문에서 BEV 점유율이 96%에 달하며 전동화 도입을 주도하고 있으며, 그 파급 효과가 상용차 및 레저용 차량 부문까지 미치고 있습니다. 각 제조업체는 전동화 솔루션에 막대한 투자를 하고 있으며, 트루마(Truma)사는 보쉬(Bosch)의 Electric Solutions 부서에서 요아힘 베크벨트(Joachim Weckwert) 박사를 제품 개발 책임자로 임명함으로써 전동화에 대한 전략적 노력을 분명히 보여주고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
JHS 26.09.11According to Mordor Intelligence, the Europe recreational vehicle market size is expected to grow from USD 33.38 billion in 2025 to USD 37.07 billion in 2026 and is forecast to reach USD 62.69 billion by 2031 at 11.08% CAGR over 2026-2031.
This report is Segmented by Type (Towable RVs, Motorhomes), Propulsion and Fuel (Diesel ICE, Petrol ICE, Hybrid-Electric, Battery-Electric), Ownership Model (Private Owners, Rental and Sharing Fleets), Sales Channel (OEM-Franchised Dealers, and More), and Country (Germany, United Kingdom, and More). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Europe Recreational Vehicle Market Trends and Insights
Post-pandemic Surge in Domestic and Intra-Europe Tourism
European camping activity has reached unprecedented levels, with Germany recording 42.9 million camping overnight stays in 2024, representing a 19.9% increase compared to 2019 pre-pandemic levels. This sustained elevation in domestic tourism reflects a fundamental shift in European leisure preferences, where proximity-based travel has evolved from pandemic necessity to preferred lifestyle choice. The trend extends beyond Germany, with Norway's camping sites witnessing a rise in guest nights, marking significant year-over-year growth. The persistence of elevated camping activity well into 2025 suggests this represents structural demand rather than temporary pandemic-driven behavior, particularly as camping accounts for most German guest overnight stays compared to historical levels. This tourism reorientation creates sustained tailwinds for RV demand across vehicle segments, from compact campervans enabling urban-adjacent exploration to larger motorhomes supporting extended domestic touring.
Rapid Expansion of RV-sharing and Rental Platforms
The European RV-sharing ecosystem has matured rapidly. The sector's growth acceleration is evidenced by Roadsurfer securing EUR 30 million from Avellinia Capital in April 2025, specifically for fleet expansion from 8,500 to 10,000 vehicles. This capital deployment reflects institutional recognition that peer-to-peer RV platforms have overcome initial trust barriers and achieved operational scale. Notably, platforms are expanding eastward, with Ruuts targeting Eastern European markets through API integrations, providing access to major European RVs, and addressing previously underserved regions. The sharing economy's penetration into RV ownership patterns creates dual market effects: democratizing access for first-time users while generating utilization-based revenue streams for private owners, effectively expanding the addressable market beyond traditional ownership models.
High Upfront Purchase and Insurance Costs
European RV prices have surged, straining affordability across market segments. This increase stems from supply chain disruptions, chassis shortages, and manufacturers leveraging pandemic-driven demand. Rising insurance premiums, driven by higher replacement values and specialized repair needs, add to the financial burden. Middle-market buyers increasingly opt for used vehicles or rentals, while younger and first-time buyers face barriers, limiting market growth despite strong demand. Even with inventory corrections, persistent high prices highlight structural cost inflation, necessitating income growth or alternative ownership models to sustain accessibility.
Other drivers and restraints analyzed in the detailed report include:
- Ageing but Affluent 55 to 75 Cohort Boosting Premium Demand
- EU B-license Weight Limit Rising to 4.25 t Enabling Larger Floorplans
- Volatile Interest-rate-driven Financing Squeeze
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Motorhomes maintained their dominant position with a 53.72% share of the Europe recreational vehicle market in 2025, reflecting European consumers' preference for self-contained mobile living solutions that provide comprehensive amenities without external dependencies. The segment's leadership stems from its appeal to the affluent 55-75 demographic, prioritizing comfort and convenience over mobility constraints. However, campervans are experiencing the fastest growth at 11.62% CAGR through 2031, driven by younger demographics embracing van life culture and urban professionals seeking flexible work-travel solutions. Travel and fifth-wheel trailers occupy smaller but stable niches, appealing to consumers who prefer to maintain separate towing vehicles for daily use. Pop-up and folding campers represent the entry-level segment, attracting price-sensitive buyers and seasonal users.
The regulatory environment supports this segmentation evolution, with EU type-approval frameworks under Regulation 2018/858 providing clear pathways for multi-stage vehicle approvals that facilitate campervan conversions while maintaining safety standards. Class A motorhomes command premium pricing but face headwinds from urban low-emission zone restrictions, while Class B campervans benefit from improved urban accessibility and parking flexibility.
Diesel ICE powertrains command 91.10% share of the Europe recreational vehicle market in 2025, reflecting the segment's traditional reliance on diesel's superior torque characteristics and fuel efficiency for heavy vehicle applications. Petrol ICE variants maintain a smaller presence, primarily in lighter campervan applications where weight considerations favor gasoline engines. However, battery-electric variants are surging at a 36.91% CAGR through 2031, driven by tightening EU emission regulations and expanding charging infrastructure. Hybrid-electric solutions occupy a transitional position, offering compromise solutions for range-anxious consumers while providing emission benefits for urban access.
Norway leads electric adoption with 96% BEV share in passenger cars, creating spillover effects into commercial and recreational vehicle segments. Manufacturers are investing heavily in electric solutions, with Truma appointing Dr. Joachim Weckwerth from Bosch's Electric Solutions division to lead product development, signaling a strategic commitment to electrification.
Complete Report Scope:
- By Type
- Towable RVs
- Travel Trailers
- Fifth-Wheel Trailers
- Pop-up/Folding Campers
- Motorhomes
- Class A
- Class B (Campervans)
- Class C
- Towable RVs
- By Propulsion and Fuel
- Diesel Internal Combustion Engine
- Petrol Internal Combustion Engine
- Hybrid-Electric
- Battery-Electric
- By Ownership Model
- Private Owners
- Rental and Sharing Fleets
- By Sales Channel
- OEM-Franchised Dealers
- Direct-to-Consumer Online
- Rental Agency Networks
- By Country
- Germany
- United Kingdom
- France
- Italy
- Spain
- Netherlands
- Norway
- Rest of Europe
List of Companies Covered in this Report:
- Erwin Hymer Group (Thor Industries)
- Trigano SA
- Auto Trail VR LTD
- Knaus Tabbert AG
- Hobby-Fendt Caravan GmbH
- Swift Group Ltd.
- Rapido Group
- Adria Mobil d.o.o.
- Dethleffs GmbH & Co. KG
- Rimor Motorhomes
- Eura Mobil GmbH
- Burstner GmbH
- Laika Caravans S.p.A.
- Westfalia Mobil GmbH
- Globe-Traveller RV Sp. z O.o.
- Malibu GmbH & Co. KG
- Benimar SL
- Challenger (Trigano)
- Possl Group
- Pilote Groupe
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Post-Pandemic Surge In Domestic And Intra-Europe Tourism
- 4.2.2 Rapid Expansion Of RV-Sharing And Rental Platforms
- 4.2.3 Ageing But Affluent 55 to 75 Cohort Boosting Premium Demand
- 4.2.4 Upgrade Of More Than 3,000 EU Campsites To "Connected-Stay" Standards
- 4.2.5 EU B-License Weight Limit Rising To 4.25 t Enabling Larger Floorplans
- 4.2.6 Emergence Of "Work-From-Anywhere" Digital-Nomad Van Conversions
- 4.3 Market Restraints
- 4.3.1 High Upfront Purchase And Insurance Costs
- 4.3.2 Volatile Interest-Rate-Driven Financing Squeeze
- 4.3.3 Oversupply-Led Price Depreciation Of 2021-22 Inventory
- 4.3.4 Urban Low-Emission Zones Curbing Diesel RV Access
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size and Growth Forecast (Value (USD) and Volume (Units))
- 5.1 By Type
- 5.1.1 Towable RVs
- 5.1.1.1 Travel Trailers
- 5.1.1.2 Fifth-Wheel Trailers
- 5.1.1.3 Pop-up/Folding Campers
- 5.1.2 Motorhomes
- 5.1.2.1 Class A
- 5.1.2.2 Class B (Campervans)
- 5.1.2.3 Class C
- 5.1.1 Towable RVs
- 5.2 By Propulsion and Fuel
- 5.2.1 Diesel Internal Combustion Engine
- 5.2.2 Petrol Internal Combustion Engine
- 5.2.3 Hybrid-Electric
- 5.2.4 Battery-Electric
- 5.3 By Ownership Model
- 5.3.1 Private Owners
- 5.3.2 Rental and Sharing Fleets
- 5.4 By Sales Channel
- 5.4.1 OEM-Franchised Dealers
- 5.4.2 Direct-to-Consumer Online
- 5.4.3 Rental Agency Networks
- 5.5 By Country
- 5.5.1 Germany
- 5.5.2 United Kingdom
- 5.5.3 France
- 5.5.4 Italy
- 5.5.5 Spain
- 5.5.6 Netherlands
- 5.5.7 Norway
- 5.5.8 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Erwin Hymer Group (Thor Industries)
- 6.4.2 Trigano SA
- 6.4.3 Auto Trail VR LTD
- 6.4.4 Knaus Tabbert AG
- 6.4.5 Hobby-Fendt Caravan GmbH
- 6.4.6 Swift Group Ltd.
- 6.4.7 Rapido Group
- 6.4.8 Adria Mobil d.o.o.
- 6.4.9 Dethleffs GmbH & Co. KG
- 6.4.10 Rimor Motorhomes
- 6.4.11 Eura Mobil GmbH
- 6.4.12 Burstner GmbH
- 6.4.13 Laika Caravans S.p.A.
- 6.4.14 Westfalia Mobil GmbH
- 6.4.15 Globe-Traveller RV Sp. z O.o.
- 6.4.16 Malibu GmbH & Co. KG
- 6.4.17 Benimar SL
- 6.4.18 Challenger (Trigano)
- 6.4.19 Possl Group
- 6.4.20 Pilote Groupe


