

|
시장보고서
상품코드
2121308
이탈리아의 공장 자동화 및 산업 제어 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Italy Factory Automation And Industrial Controls - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
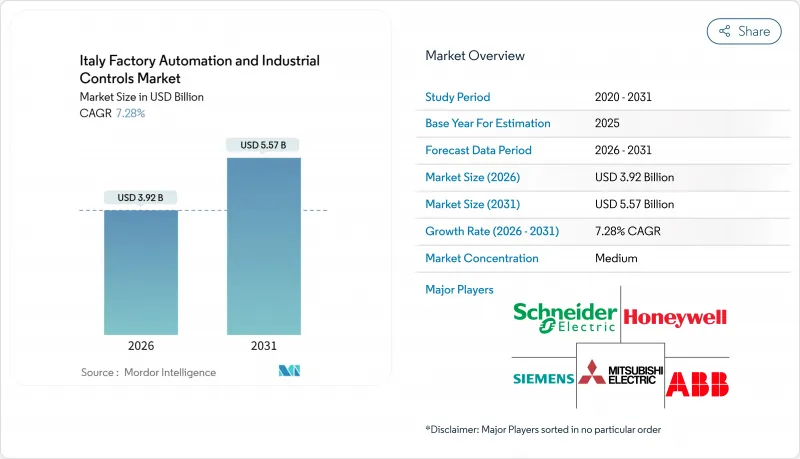
에 따르면 이탈리아의 공장 자동화 및 산업 제어 시장 규모는 2026년에 39억 2,000만 달러이며, 2031년까지 55억 7,000만 달러에 달할 것으로 예측되며, 예측 기간 동안 CAGR 7.28%로 성장할 것으로 전망됩니다.
본 보고서는 제품별(산업 제어 시스템, 필드 디바이스, 산업용 소프트웨어·서비스), 구성요소별(하드웨어, 소프트웨어, 서비스), 배포 방식별(온프레미스, 클라우드, 엣지), 최종사용자 산업별(전력·공익사업, 자동차·운송 산업, 섬유, 식음료, 기타)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
이탈리아 공장 자동화 및 산업 제어 시장의 동향 및 인사이트
‘Transition 4.0’ 및 ‘Transition 5.0’ 세제 혜택의 지속
2025년에 도입된 ‘Transition 5.0’에서는 시설 수준에서 3%, 공정 수준에서 5%의 에너지 절감 달성에 따라 35%에서 45%의 환급이 적용되며, 자동화가 탈탄소화의 원동력이 되고 있습니다. 지속적인 에너지 절감 효과를 기록하는 폐쇄 루프형 엣지 게이트웨이가 현재 구매 후보 목록 상위를 차지하고 있으며, Comau의 보고서에 따르면 2025년 로봇 수주의 63%에 에너지 모니터링 모듈이 포함되었습니다. 2026년도 예산에 따라 적용 대상 기간이 2027년까지 연장됨에 따라 기업들은 구매를 앞당기게 되었고, 주기적인 수주 급증이 발생했습니다. 이에 따라 각 벤더사는 크레딧 승인을 확실하게 하기 위해 감사 대응이 완료된 문서를 하드웨어에 동봉하고 있습니다. 잦은 재검토로 인해 수요 변동이 발생하고 있지만, 이 인센티브 제도는 이탈리아의 공장 자동화 및 산업용 제어 시장에 있어 여전히 가장 큰 성장 촉진요인으로 작용하고 있습니다.
숙련된 제조업 인력의 부족 심화
2025년, 이탈리아 제조업 종사자 수의 31%를 55세 이상 근로자가 차지하고 있으며, 이는 G7 국가 중 가장 높은 비율입니다. 북부 지역에서는 기계공 및 기술자 분야의 미충원 구인 건수가 1만 8,000건을 넘어섰으며, 이로 인해 협동 로봇 출하대수가 전년 대비 27% 증가했습니다. 야스카와(Yaskawa)의 볼로냐 교육 센터는 협업 로봇 셀의 도입 기간을 절반으로 단축하여, 기업이 표준화된 디지털 워크플로우를 통해 상실된 암묵적 지식을 보완할 수 있도록 지원하고 있습니다. 은퇴가 가속화되는 가운데, 제조업체들은 암묵적 지식을 머신비전이나 디지털 트윈 시스템에 체계화하여 전문성이 낮은 직원도 모니터링할 수 있도록 하고 있습니다. 따라서 노동력 부족은 자율 시스템 및 예측 분석으로의 전환을 구조적으로 뒷받침하고 있습니다.
빈번한 정책 변경으로 인한 투자 전망의 불투명화
2020년부터 2025년에 걸친 기준치 개정(2024년 에너지 절약 기준이 0%에서 3%로 급격히 상향 조정된 것을 포함)으로 인해 계획 기간을 단축할 수밖에 없게 되었으며, 조사 대상 기업의 48%가 규제가 확정될 때까지 프로젝트를 연기했습니다. 신용 자격이 취소될 가능성이 있는 상황에서는 여러 해에 걸친 소프트웨어 구독 계약이 높은 위험으로 간주되므로, 구매자는 단기적인 투자 회수가 기대되는 개별 하드웨어를 선호하는 경향이 있습니다. 화학 산업 등 에너지 집약적 부문에서는 공정 변경 검증에 18-24개월이 소요되기 때문에 급격한 규제 변경은 특히 큰 부담이 됩니다. 슈나이더 일렉트릭(Schneider Electric)은 고객들이 클라우드 호스팅형 분석에 대한 명확한 지침을 기다리는 가운데, 2025년 초 수주 전망이 19% 축소되었다고 지적했습니다. 따라서 정책의 예측 불가능성은 이탈리아의 공장 자동화 및 산업용 제어 시장에 여전히 걸림돌로 작용하고 있습니다.
부문 분석
산업 제어 시스템 부문은 2025년 매출의 45.78%를 차지하며, 화학, 전력, 석유·가스 시설에서의 기존 분산 제어 및 SCADA 기반을 뒷받침하고 있습니다. 산업용 소프트웨어 및 서비스는 규모는 작지만 연평균 성장률(CAGR) 7.81%로 성장하고 있으며, 이는 이탈리아의 공장 자동화 및 산업용 제어 시장에서 가장 빠른 성장 속도입니다. CINECA가 레오나르도 슈퍼컴퓨터의 처리 능력 중 20%를 제조 워크로드에 할당함에 따라, 중소기업은 설비 투자 없이도 전산유체역학(CFD) 시뮬레이션을 수행할 수 있게 되었습니다. Siemens의 MindSphere와 AVEVA PI System이 제공하는 구독형 분석은 2025년에 ISO 27001 인증을 획득하여 일반 데이터 보호 규정(GDPR)에 따른 우려를 해소했습니다.
소프트웨어의 성장은 가상 센서 및 디지털 트윈의 한계 비용이 낮다는 점도 반영하고 있으며, 플랫폼이 일단 구축되면 그 증분 비용은 0에 가까워집니다. Rockwell Automation의 ‘FactoryTalk Design Studio’는 엔지니어링 시간을 30% 단축하여, 통합업체가 영구 라이선스에서 지속적인 수익 모델로 전환하는 것을 촉진하고 있습니다. 에너지 모니터링 의무화로 인해 라인당 센서 밀도가 높아지고 있어 현장 장치에 대한 수요는 견조한 추세를 보이고 있지만, 그 성장률은 이탈리아의 공장 자동화 및 산업용 제어 시장 전체의 성장률을 상회하지 못하며 시장 전반의 동향을 따르고 있습니다. 이러한 변화하는 구성은 가치가 하드웨어에서 가동 시간과 규제 준수를 향상시키는 데이터가 풍부한 플랫폼으로 이동하고 있음을 보여줍니다.
2025년 매출에서 하드웨어가 차지하는 비중은 여전히 56.19%였지만, NIS2에 따라 엣지 분석, 사이버 보안 오버레이, 디지털 트윈 엔진이 필수화됨에 따라 소프트웨어는 연평균 성장률(CAGR) 7.93%라는 가장 빠른 속도로 성장하고 있습니다. ABB Ability의 구독은 2025년에 41% 증가했으며, 신규 계약의 3분의 2를 예측 유지보수 모듈이 차지했습니다. 서비스 수익은 현재 소프트웨어와 함께 제공되고 있습니다. 에머슨의 DeltaV 플랫폼에는 패치 적용 및 운영자 교육을 포함하는 5년간의 관리형 서비스 계약이 포함되어 있습니다.
하드웨어 시장은 양극화되고 있습니다. 기존 릴레이 기반 컨트롤러는 점차 도태되고 있는 반면, 로봇 공학 및 반도체 제조 장비용 고성능 모션 제어 기술은 여전히 필수적입니다. 베크호프의 EtherCAT 컨트롤러는 소프트웨어 중심 아키텍처를 활용하여 시장 점유율을 12%까지 확대했습니다. 그 결과, 소프트웨어의 견인 효과로 서비스가 확대되어 이탈리아의 공장 자동화 및 산업용 제어 시장에서 벤더의 장기적인 이익률을 뒷받침하는 기반이 되고 있습니다.
기타 혜택
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSM 26.09.03According to Mordor Intelligence, the Italy factory automation and Industrial Controls Market size was USD 3.92 billion in 2026 and is projected to reach USD 5.57 billion by 2031, growing at a 7.28% CAGR over the forecast period.
This report is Segmented by Product (Industrial Control Systems, Field Devices, Industrial Software and Services), Component (Hardware, Software, Services), Deployment Mode (On-Premises, Cloud, Edge), End-User Industry (Power and Utilities, Automotive and Transportation, Textile, Food and Beverage, and More). The Market Forecasts are Provided in Terms of Value (USD).
Italy Factory Automation And Industrial Controls Market Trends and Insights
Continuation of Transition 4.0 and 5.0 Tax Incentives
Transition 5.0, introduced in 2025, ties a 35% to 45% rebate to a 3% facility-level or 5% process-level energy reduction, turning automation into a lever for decarbonization. Closed-loop edge gateways that document continuous savings now dominate purchasing shortlists, and Comau reported that energy-monitoring modules accompanied 63% of 2025 robot orders. The 2026 budget extended eligibility to 2027, prompting firms to front-load purchases and creating cyclical order spikes. Vendors, therefore, bundle audit-ready documentation with hardware to assure credit approval. Although frequent revisions create demand lumpiness, the incentive framework remains the single largest growth catalyst for the Italy factory automation and industrial controls market.
Rising Labor Shortages in Skilled Manufacturing Roles
Workers aged 55 and older accounted for 31% of Italy's manufacturing headcount in 2025, the highest ratio among G7 economies. Unfilled machinist and technician vacancies exceeded 18,000 in northern districts, driving a 27% year-over-year increase in collaborative-robot shipments. Yaskawa's Bologna training center compresses cobot-cell deployment time by half, allowing firms to offset lost tribal knowledge with standardized digital workflows. As retirements accelerate, manufacturers codify tacit knowledge into machine-vision and digital-twin systems that less specialized staff can supervise. Labor scarcity, therefore, structurally supports a shift toward autonomous systems and predictive analytics.
Frequent Policy Changes Reduce Investment Visibility
Threshold revisions in 2020-2025, including a sudden energy-saving jump from 0% to 3% in 2024, shortened planning horizons and caused 48% of surveyed firms to defer projects until regulations were finalized. Multi-year software subscriptions appear risky when credit eligibility can be revoked, so buyers prefer discrete hardware with near-term payback. Energy-intensive sectors such as chemicals need 18-24 months to validate process changes, making abrupt rule shifts especially burdensome. Schneider Electric noted a 19% contraction in its pipeline in early 2025, as clients waited for clarity on cloud-hosted analytics. Policy predictability, therefore, remains a drag on the Italy factory automation and industrial controls market.
Other drivers and restraints analyzed in the detailed report include:
- Accelerating Automotive Electrification Investments
- Expansion of 5G and Fiber Industrial IoT Connectivity
- Persistent Shortage of Automation-Cybersecurity Engineers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The industrial control systems segment generated 45.78% of the 2025 revenue, underpinning legacy distributed-control and SCADA footprints across chemicals, power, and oil and gas sites. Industrial software and services, although smaller, are growing at a 7.81% CAGR, the swiftest pace within the Italy factory automation and industrial controls market. CINECA's allocation of 20% of the Leonardo supercomputer's capacity to manufacturing workloads enabled small and medium-sized enterprises to perform computational fluid dynamics simulations without incurring capital outlay. Subscription-based analytics from Siemens MindSphere and AVEVA PI System achieved ISO 27001 certification in 2025, alleviating concerns under the General Data Protection Regulation.
Software growth also reflects the marginal economics of virtual sensors and digital twins, whose incremental cost approaches zero once the platform exists. Rockwell Automation's FactoryTalk Design Studio reduces engineering time by 30%, encouraging integrators to transition from perpetual licenses to recurring revenue. Field devices retain steady demand because energy-monitoring mandates lift sensor density per line, yet their growth tracks the overall Italy factory automation and industrial controls market rather than outpacing it. The evolving mix shows value migrating from hardware toward data-rich platforms that improve uptime and regulatory compliance.
Hardware still contributed 56.19% of 2025 sales, but software is rising fastest at a 7.93% CAGR as edge analytics, cybersecurity overlays, and digital twin engines become mandatory under NIS2. ABB Ability subscriptions grew 41% in 2025, with predictive-maintenance modules comprising two-thirds of new contracts. Service revenues are now bundled with software; Emerson's DeltaV platform includes five-year managed-service contracts covering patching and operator training.
The hardware market is bifurcating. Legacy relay-based controllers face retirement, while high-performance motion controls for robotics and semiconductor tools remain indispensable. Beckhoff EtherCAT controllers have expanded their share to 12% by leveraging a software-centric architecture. Consequently, software pull-through boosts services, anchoring long-term vendor margins within the Italy factory automation and industrial controls market industry.
Complete Report Scope:
- By Product
- Industrial Control Systems
- Field Devices
- Industrial Software and Services
- By Component
- Hardware
- Software
- Services
- By Deployment Mode
- On-premises
- Cloud
- Edge
- By End-user Industry
- Oil and Gas
- Chemical and Petrochemical
- Power and Utilities
- Automotive and Transportation
- Textile
- Food and Beverage
- Electronics and Semiconductor
- Other End-user Industries
List of Companies Covered in this Report:
- ABB Ltd
- Siemens AG
- Schneider Electric SE
- Rockwell Automation Inc.
- Mitsubishi Electric Corp.
- Honeywell International Inc.
- Emerson Electric Co.
- Omron Corp.
- Yokogawa Electric Corp.
- Fanuc Corp.
- Yaskawa Electric Corp.
- Nidec Corp.
- Fuji Electric Co. Ltd
- Bosch Rexroth AG
- Comau SpA
- Danfoss A/S
- Delta Electronics Inc.
- Renishaw plc
- AVEVA Group plc
- Beckhoff Automation GmbH
- Lenze SE
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Industry Value Chain Analysis
- 4.3 Market Drivers
- 4.3.1 Continuation of Transition 4.0 and 5.0 Tax Incentives
- 4.3.2 Rising Labor Shortages in Skilled Manufacturing Roles
- 4.3.3 Accelerating Automotive Electrification Investments
- 4.3.4 Expansion of 5G and Fiber Industrial IoT Connectivity
- 4.3.5 Surge in Modular DC Power Distribution Retrofits
- 4.3.6 Integration of Leonardo Supercomputer for SME Simulation
- 4.4 Market Restraints
- 4.4.1 Frequent Policy Changes Reducing Investment Visibility
- 4.4.2 Persistent Shortage of Automation-Cybersecurity Engineers
- 4.4.3 High Up-Front Costs Limiting SME Adoption
- 4.4.4 EU Data-Residency Rules Restricting Non-EU ICS SaaS
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Regulatory Landscape
- 4.7 Technology Snapshot
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Consumers
- 4.8.3 Threat of New Entrants
- 4.8.4 Intensity of Competitive Rivalry
- 4.8.5 Threat of Substitutes
- 4.9 Impact of Covid-19 on the Industry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product
- 5.1.1 Industrial Control Systems
- 5.1.2 Field Devices
- 5.1.3 Industrial Software and Services
- 5.2 By Component
- 5.2.1 Hardware
- 5.2.2 Software
- 5.2.3 Services
- 5.3 By Deployment Mode
- 5.3.1 On-premises
- 5.3.2 Cloud
- 5.3.3 Edge
- 5.4 By End-user Industry
- 5.4.1 Oil and Gas
- 5.4.2 Chemical and Petrochemical
- 5.4.3 Power and Utilities
- 5.4.4 Automotive and Transportation
- 5.4.5 Textile
- 5.4.6 Food and Beverage
- 5.4.7 Electronics and Semiconductor
- 5.4.8 Other End-user Industries
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 ABB Ltd
- 6.4.2 Siemens AG
- 6.4.3 Schneider Electric SE
- 6.4.4 Rockwell Automation Inc.
- 6.4.5 Mitsubishi Electric Corp.
- 6.4.6 Honeywell International Inc.
- 6.4.7 Emerson Electric Co.
- 6.4.8 Omron Corp.
- 6.4.9 Yokogawa Electric Corp.
- 6.4.10 Fanuc Corp.
- 6.4.11 Yaskawa Electric Corp.
- 6.4.12 Nidec Corp.
- 6.4.13 Fuji Electric Co. Ltd
- 6.4.14 Bosch Rexroth AG
- 6.4.15 Comau SpA
- 6.4.16 Danfoss A/S
- 6.4.17 Delta Electronics Inc.
- 6.4.18 Renishaw plc
- 6.4.19 AVEVA Group plc
- 6.4.20 Beckhoff Automation GmbH
- 6.4.21 Lenze SE
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


