

|
시장보고서
상품코드
2121827
북미의 공장 자동화 및 산업 제어 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)North America Factory Automation And Industrial Controls - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
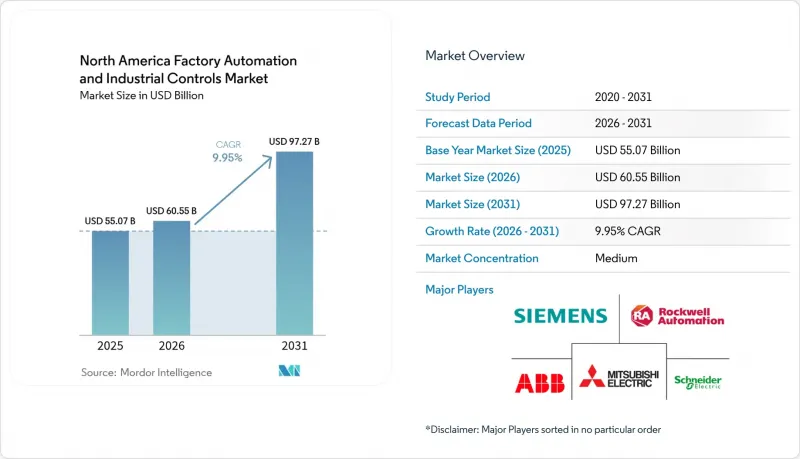
에 따르면 북미의 공장 자동화 및 산업 제어 시장 규모는 2025년에 550억 7,000만 달러로 평가되며, 2026년 605억 5,000만 달러에서 2031년까지 972억 7,000만 달러에 달할 것으로 예측되고 있으며, 예측 기간(2026-2031년)에 CAGR은 9.95%에 달할 전망입니다.
이 보고서는 유형별(산업 제어 시스템 및 필드 디바이스), 구성 요소별(하드웨어, 소프트웨어, 서비스), 배포 방식별(온프레미스, 클라우드, 엣지), 최종사용자 산업별(석유 및 가스, 화학·석유화학, 전력·공공사업, 기타), 국가별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
북미 공장 자동화 및 산업 제어 시장의 동향과 인사이트
에너지 효율적인 제조 운영에 대한 수요 급증
북미 전역의 제조업체들은 주 및 지방 정부의 엄격한 효율성 규제를 충족하고 유틸리티 비용을 절감하기 위해 고급 제어 루프, 부하 분산, 실시간 에너지 대시보드를 도입하고 있습니다. 기존 생산 라인에 가변 주파수 드라이브와 지능형 스케줄링 모듈을 사후 설치함으로써 일반적으로 총 전력 소비량을 20%에서 30%까지 절감할 수 있습니다. 이러한 절감 효과는 생산성 향상을 통한 투자 회수보다 빠르게 나타나기 때문에 추가 자동화 프로젝트에 대한 이사회 승인이 가속화됩니다. 현장 재생 가능 에너지와 스마트 컨트롤러를 통합한 시설은 새로운 수입원이 되는 송전망 안정화 프로그램에 참여하고 있습니다. 플랜트 팀에는 하드웨어뿐만 아니라 포괄적인 로드맵이 필요하므로 시운전 서비스와 ISO 50001 관련 자문 서비스를 패키지로 제공하는 공급업체가 계약을 수주하고 있습니다. 워싱턴과 오타와에서 탄소 가격 책정에 대한 논의가 재점화되는 가운데, 선구자들은 시간이 지남에 따라 증폭되는 지속가능한 비용 우위를 확보하고 있습니다.
중소기업 공장에서의 협동 로봇의 급속한 도입
중소기업은 11만-20만 달러 가격대의 협업 로봇을 도입하고 있습니다. 이는 이러한 로봇이 최소한의 안전 조치만으로도 충분하고, 기존 기술자에 의해 재배치가 가능하기 때문입니다. 협동 로봇은 반복적인 픽 앤 플레이스, 기계 조작, 경량 조립 작업을 담당하므로, 직원들은 부가가치가 높은 검사 업무에 집중할 수 있습니다. 초과 근무 수당 및 불량품 감소를 고려하면, 투자 회수 기간은 대부분의 경우 18개월 이하입니다. 생산 라인 전체를 재설계하지 않고도 SKU를 전환할 수 있는 유연성은 북미 중소기업에 전형적인 ‘소량 다품종 생산’의 요구에 부합합니다. 지역 제조업 협회를 통해 성공 사례가 확산됨에 따라 동종 업계의 지지를 받아 도입이 가속화되고 있으며, 북미의 공장 자동화 및 산업 제어 시장은 더욱 확대되고 있습니다.
레거시 제어 시스템의 사이버 보안 취약점
사이버보안 및 인프라 보안국(CISA)은 2024년에 널리 도입된 PLC 및 HMI 플랫폼에서 여러 가지 원격 코드 실행 취약점을 공개했습니다. 원격 모니터링을 위해 격리된 네트워크 접속을 서둘러 도입한 공장들은 현재 공격 표면의 확대라는 문제에 직면해 있습니다. 패치 적용에는 대개 막대한 비용이 드는 가동 중단이나 컨트롤러 교체가 필요하므로 유지보수 예산에 부담을 주고 있습니다. 보험사가 운영 기술(OT)의 위험을 재평가함에 따라 보험료는 상승하고 있습니다. 일부 시설에서는 제로 트러스트 아키텍처가 성숙해질 때까지 새로운 디지털화를 연기하고 있으며, 이로 인해 북미의 공장 자동화 및 산업 제어 시장은 일시적으로 둔화되고 있습니다.
부문 분석
2025년에는 산업 제어 시스템이 북미 공장 자동화 및 산업 제어 시장에서 가장 큰 수익을 창출하며 시장 점유율의 58.15%를 차지했습니다. 필드 디바이스는 더 강력한 성장 모멘텀을 보이며 연평균 성장률(CAGR) 10.85%를 기록했고, 이는 센서 및 비전 시스템 공급업체의 실적을 끌어올리고 있습니다. 중앙 집중식 컨트롤러와 급증하는 엣지 디바이스 간의 통합이 복잡해짐에 따라 구매자들은 통합형 엔지니어링 제품군을 선호하는 추세입니다. 분산 제어 시스템 및 PLC 업그레이드와 관련된 북미 공장 자동화 및 산업 제어 시장의 규모는 공장이 레거시 코드를 현대화하고 컨텍스트 데이터 계층을 추가함에 따라 계속해서 확대되고 있습니다.
필드 디바이스의 성장은 품질 보증 및 처리량을 강화하는 협동 로봇, 첨단 머신 비전, 다축 모션 키트에 기인합니다. 주요 제어 플랫폼에 즉시 사용 가능한 연동 기능을 제공하는 벤더는 프로젝트 주기를 단축하고 있으며, 이는 모델 출시 기간 단축을 목표로 하는 Tier 1 자동차 제조사의 생산 라인에 있으며, 중요한 요소가 되고 있습니다. 디바이스 데이터가 분석 허브로 지속적으로 스트리밍됨에 따라 AI 모델에도 데이터가 공급되어 사이클 타이밍 및 예측 유지보수 규칙의 최적화가 이루어지고 있습니다. 그 결과, 하드웨어에 번들로 제공되는 소프트웨어 라이브러리 및 프로토콜 변환기는 현재 북미의 공장 자동화 및 산업 제어 시장 전체에서 높은 이익률을 창출하고 있습니다.
하드웨어는 2025년 매출의 60.05%를 차지하고 있으며, 이는 수천 개의 공장에 설치된 물리적 자산을 반영한 것입니다. 그러나 공장이 생산성 및 지속가능성 향상을 위해 잠재적인 데이터 활용을 추진함에 따라 소프트웨어는 연평균 성장률(CAGR) 10.98%로 성장하고 있습니다. 클라우드 히스토리안,AI 툴키트, 디지털 트윈이 드라이브나 센서와 세트로 제공되는 사례가 증가하고 있으며, 가치 창출이 코드로 이동하고 있음을 입증하고 있습니다. 산업용 소프트웨어 구독과 관련된 북미 공장 자동화 및 산업 제어 시장 규모는 2031년까지 개별 하드웨어 지출과 맞먹을 것으로 전망됩니다.
엣지-투-클라우드 아키텍처를 통해 공장에서는 고주파 신호를 로컬에서 수집하는 동시에, 요약된 인사이트를 중앙 대시보드로 전송할 수 있게 됩니다. 시뮬레이션 패키징은 엔지니어가 레시피 변경 사항을 오프라인에서 테스트하는 데 도움이 되어, 가동 초기 불량품을 줄여줍니다. 증강현실(AR)을 활용한 작업 지침서는 기술자의 작업 정확도를 높이고 숙련 기간을 단축합니다. 표준 라이선스에 사이버 보안 모듈을 통합함으로써, 위험 감소를 요구하는 이사회와 보험사의 요청에도 부응하며, 소프트웨어를 단순한 옵션 추가 기능에서 전략적 요건으로 격상시킵니다.
기타 혜택
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.03According to Mordor Intelligence, the North America factory automation and industrial controls market size was valued at USD 55.07 billion in 2025 and estimated to grow from USD 60.55 billion in 2026 to reach USD 97.27 billion by 2031, at a CAGR of 9.95% during the forecast period (2026-2031).
This report is Segmented by Type (Industrial Control Systems and Field Devices), Component (Hardware, Software, and Services), Deployment Mode (On-Premise, Cloud, and Edge), End-User Industry (Oil and Gas, Chemical and Petrochemical, Power and Utilities, and More), and Country. The Market Forecasts are Provided in Terms of Value (USD).
North America Factory Automation And Industrial Controls Market Trends and Insights
Surge in demand for energy-efficient manufacturing operations
Manufacturers across North America implement advanced control loops, load balancing, and real-time energy dashboards to meet strict state and provincial efficiency rules and to cut utility costs. Retrofitting variable-frequency drives and intelligent scheduling modules into legacy lines typically lowers total electricity consumption by 20% to 30%. Savings arrive faster than productivity-led paybacks, which accelerates board approval for additional automation projects. Facilities integrating on-site renewable power with smart controllers participate in grid-stabilization programs that offer new revenue streams. Vendors that package commissioning services with ISO 50001 advisory win contracts because plant teams need holistic road maps, not just hardware. As carbon pricing discussions resurface in Washington and Ottawa, early movers lock sustainable cost advantages that compound over time.
Rapid adoption of collaborative robots in SME factories
Small and mid-size enterprises adopt collaborative robots priced between USD 110,000 and USD 200,000 because the units require minimal guarding and can be re-tasked by existing technicians. Cobots handle repetitive pick-and-place, machine tending, and light assembly while employees focus on value-added inspection. Payback periods often fall below 18 months when overtime premiums and scrap reductions are considered. The flexibility to shift between SKUs without re-engineering entire lines aligns with the low-volume, high-variety production typical of North American SMEs. As success stories spread through regional manufacturing associations, peer endorsement accelerates wider deployments, further enlarging the North America factory automation and industrial controls market.
Cybersecurity vulnerabilities in legacy control systems
The Cybersecurity and Infrastructure Security Agency disclosed multiple remote-code-execution flaws in widely deployed PLC and HMI platforms during 2024. Plants that rushed to connect isolated networks for remote monitoring now face expanded attack surfaces. Patching often requires costly downtime or controller replacement, which stretches maintenance budgets. Insurance premiums climb as underwriters reassess operational-technology risk. Some facilities delay new digitization until zero-trust architectures mature, temporarily slowing the North America factory automation and industrial controls market.
Other drivers and restraints analyzed in the detailed report include:
- Federal incentives accelerating on-shoring of electronics production
- AI-driven predictive maintenance reducing unplanned downtime
- Supply-chain volatility for critical automation components
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Industrial control systems generated the largest revenue in 2025 with a 58.15% share of the North America factory automation and industrial controls market. Field devices displayed stronger momentum, recording an 10.85% CAGR that is lifting sensor and vision-system suppliers. Integration complexity between centralized controllers and proliferating edge devices motivates buyers to favor unified engineering suites. The North America factory automation and industrial controls market size attached to distributed control systems and PLC upgrades continues to rise as plants modernize legacy code and add contextual data layers.
Growth in field devices stems from collaborative robotics, advanced machine vision, and multi-axis motion kits that bolster quality assurance and throughput. Vendors offering out-of-the-box links to major control platforms shorten project cycles, a key factor for tier-one automotive lines targeting shorter model launches. Continuous streaming of device data into analytics hubs also feeds AI models that refine cycle timing and predictive maintenance rules. As a result, software libraries and protocol converters bundled with hardware now command premium margins across the North America factory automation and industrial controls market.
Hardware still contributed 60.05% of 2025 revenue, reflecting the physical assets installed across thousands of factories. Software, however, advances at an 10.98% CAGR as plants unlock latent data for productivity and sustainability gains. Cloud historians, AI toolkits, and digital twins increasingly ship alongside drives and sensors, proving that value creation has migrated toward code. The North America factory automation and industrial controls market size linked to industrial-software subscriptions is on track to rival discrete hardware outlays by 2031.
Edge-to-cloud architectures let plants collect high-frequency signals locally while pushing summarized insights to central dashboards. Simulation packages help engineers test recipe changes offline, reducing scrap at launch. Augmented-reality work instructions improve technician accuracy and shorten training curves. Integration of cybersecurity modules within standard licenses also answers board and insurer demands for risk mitigation, elevating software from an optional add-on to a strategic requirement.
Complete Report Scope:
- By Type
- Industrial Control Systems
- Distributed Control System (DCS)
- Programmable Logic Controller (PLC)
- Supervisory Control and Data Acquisition (SCADA)
- Product Lifecycle Management (PLM)
- Human Machine Interface (HMI)
- Manufacturing Execution System (MES)
- Field Devices
- Machine Vision Systems
- Robotics (Industrial)
- Sensors and Transmitters
- Motors and Drives
- Other Field Devices
- Industrial Control Systems
- By Component
- Hardware
- Software
- Services
- By Deployment Mode
- On-premise
- Cloud
- Edge
- By End-user Industry
- Oil and Gas
- Chemical and Petrochemical
- Power and Utilities
- Food and Beverages
- Automotive
- Metals and Mining
- Pharmaceuticals
- Other Industries
- By Country
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- Rockwell Automation Inc.
- Siemens AG
- Mitsubishi Electric Corporation
- ABB Ltd.
- Schneider Electric SE
- Honeywell International Inc.
- Emerson Electric Company
- Omron Corporation
- Yokogawa Electric Corporation
- Yaskawa Electric Corporation
- KUKA AG
- Fanuc Corporation
- Beckhoff Automation GmbH and Co. KG
- Schneider Electric Motion USA Inc.
- Regal Rexnord Corporation
- Nidec Motor Corporation
- Basler AG
- Cognex Corporation
- Bosch Rexroth AG
- Parker Hannifin Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in demand for energy-efficient manufacturing operations
- 4.2.2 Rapid adoption of collaborative robots in SME factories
- 4.2.3 Federal incentives accelerating on-shoring of electronics production
- 4.2.4 Integration of 5G-enabled industrial IoT networks
- 4.2.5 Shortage of skilled labor spurring autonomous material handling
- 4.2.6 AI-driven predictive maintenance reducing unplanned downtime
- 4.3 Market Restraints
- 4.3.1 Cybersecurity vulnerabilities in legacy control systems
- 4.3.2 Capex freeze among mid-tier manufacturers amid high interest rates
- 4.3.3 Supply-chain volatility for critical automation components
- 4.3.4 Fragmented North American interoperability standards
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Type
- 5.1.1 Industrial Control Systems
- 5.1.1.1 Distributed Control System (DCS)
- 5.1.1.2 Programmable Logic Controller (PLC)
- 5.1.1.3 Supervisory Control and Data Acquisition (SCADA)
- 5.1.1.4 Product Lifecycle Management (PLM)
- 5.1.1.5 Human Machine Interface (HMI)
- 5.1.1.6 Manufacturing Execution System (MES)
- 5.1.2 Field Devices
- 5.1.2.1 Machine Vision Systems
- 5.1.2.2 Robotics (Industrial)
- 5.1.2.3 Sensors and Transmitters
- 5.1.2.4 Motors and Drives
- 5.1.2.5 Other Field Devices
- 5.1.1 Industrial Control Systems
- 5.2 By Component
- 5.2.1 Hardware
- 5.2.2 Software
- 5.2.3 Services
- 5.3 By Deployment Mode
- 5.3.1 On-premise
- 5.3.2 Cloud
- 5.3.3 Edge
- 5.4 By End-user Industry
- 5.4.1 Oil and Gas
- 5.4.2 Chemical and Petrochemical
- 5.4.3 Power and Utilities
- 5.4.4 Food and Beverages
- 5.4.5 Automotive
- 5.4.6 Metals and Mining
- 5.4.7 Pharmaceuticals
- 5.4.8 Other Industries
- 5.5 By Country
- 5.5.1 United States
- 5.5.2 Canada
- 5.5.3 Mexico
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Rockwell Automation Inc.
- 6.4.2 Siemens AG
- 6.4.3 Mitsubishi Electric Corporation
- 6.4.4 ABB Ltd.
- 6.4.5 Schneider Electric SE
- 6.4.6 Honeywell International Inc.
- 6.4.7 Emerson Electric Company
- 6.4.8 Omron Corporation
- 6.4.9 Yokogawa Electric Corporation
- 6.4.10 Yaskawa Electric Corporation
- 6.4.11 KUKA AG
- 6.4.12 Fanuc Corporation
- 6.4.13 Beckhoff Automation GmbH and Co. KG
- 6.4.14 Schneider Electric Motion USA Inc.
- 6.4.15 Regal Rexnord Corporation
- 6.4.16 Nidec Motor Corporation
- 6.4.17 Basler AG
- 6.4.18 Cognex Corporation
- 6.4.19 Bosch Rexroth AG
- 6.4.20 Parker Hannifin Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need assessment


