

|
시장보고서
상품코드
2121602
독일의 공장 자동화 및 산업용 제어 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Germany Factory Automation And Industrial Controls - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
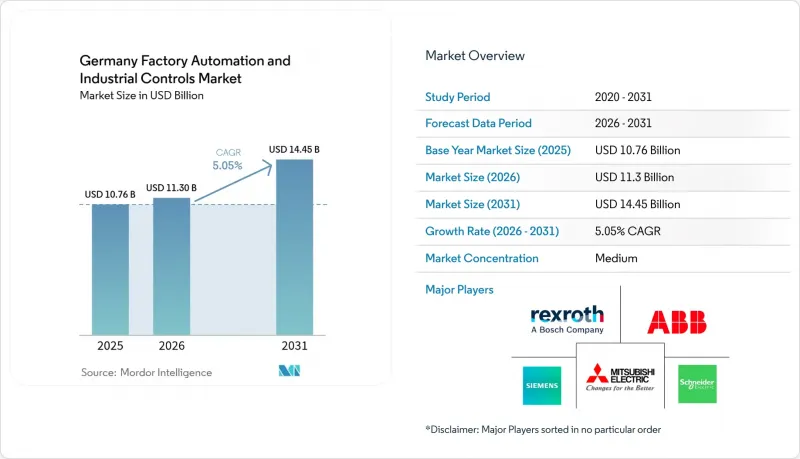
에 의하면, 독일의 공장 자동화 및 산업용 제어 시장 규모는 2025년 107억 6,000만 달러에서 2026년에는 113억 달러로 성장하고, 2026-2031년 CAGR 5.05%로 성장을 지속하여 2031년에는 144억 5,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 구성 요소별(컨트롤러, 구동 장치), 제어 시스템 유형별(디스크리트 제어 시스템, 공정 제어 시스템 등), 최종 사용자 산업별(자동차, 기계·설비 등), 배포 모델별(On-Premise형 제어 시스템, 하이브리드 아키텍처 등) 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
독일의 공장 자동화 및 산업용 제어 시장 동향과 인사이트
독일 제조업의 인더스트리 4.0 도입 현황
Plattform Industrie 4.0의 보고서에 따르면, 2024년 말까지 대규모 공장의 78% 및 중소기업의 54%가 적어도 하나의 디지털 이용 사례를 도입할 것으로 보이며, 이는 2020년의 41%에서 증가한 수치입니다. 현재 Asset Administration Shell(AAS) 및 OPC UA 표준이 기계 간 데이터 교환의 기반이 되어, 벤더 종속성 없이 이종 혼합 설비군 간의 상호 운용성을 가능하게 하고 있습니다. 1차 자동차 부품 공급업체는 프로그래머블 로직 컨트롤러(PLC) 코드 내에 디지털 트윈을 통합하고, 전환 작업을 가상으로 테스트함으로써 가동 중단 시간을 며칠에서 몇 시간으로 단축하고 있습니다. 기계 제조업체들은 엔지니어링 작업을 최대 40% 줄이고, 1교대 근무 시간 내에 생산 라인을 재구성할 수 있게 해주는 ‘플러그 앤 프로듀스(Plug-and-Produce)’ 모듈을 표준화하고 있습니다. 제조업체들이 엣지 측에서 머신 러닝 추론을 실행하여 지연을 방지하고 On-Premise에서 지적 재산을 보호함에 따라, 멀티코어 프로세서 및 FPGA를 탑재한 산업용 PC에 대한 수요가 증가하고 있습니다.
인건비 급등과 숙련된 노동자 부족이 자동화를 촉진
2024년, 제조업 시간당 임금 중앙값은 47.30유로(53.45달러)에 달하고, 유럽연합(EU) 내에서 최고 수준을 기록했습니다. 독일에서는 2030년까지 기술직 근로자가 120만 명 부족할 것으로 예측됩니다. 안전 케이지가 없는 협업 로봇의 2024년 출하 대수는 전년 대비 22% 증가했으며, 특히 크기가 다른 제품을 취급하는 식품 및 음료 포장 업체 수요가 높아졌습니다. 제약 위탁업체는 자동 운반차(AGV)를 창고 관리 소프트웨어와 통합하여 처리 능력을 18% 향상시키고, 부상 건수를 35% 줄였습니다. 2020년 이후 견습 교육 수료율이 9% 하락하고, 작업자의 이직률이 연평균 14%에 달함에 따라 자동화는 급증하는 인재 양성 비용을 상쇄하고 있습니다.
중소기업의 높은 초기 설비 투자
독일 제조업 인력의 60%를 중소기업이 고용하고 있지만, 공장 한 곳당 80만-150만 유로(90만 4,000-170만 달러)에 달하는 초기 설비 갱신 비용에 직면해 있으며, 이익률이 낮은 분야에서는 투자 회수 기간이 5년에 이릅니다. ‘Digital Now’ 보조금은 이 비용의 절반을 충당해 주지만, 신청자는 에너지 감사 보고서나 사이버 보안 계획서를 제출해야 하며, 중소기업들은 이를 외부에 위탁하는 경우가 많아 보조금 지급이 6-9개월 지연될 수 있습니다. 리스나 ‘Automation-as-a-Service(AaaS)’ 모델을 이용하면 비용을월사용료로 분산할 수 있지만, 데이터 소유권이나 벤더 락인(vendor lock-in)에 대한 우려로 인해 VDMA의 도입은 더딘 임베디드니다.
부문 분석
2025년, 독일의 공장 자동화 및 산업용 제어 장비 시장에서 컨트롤러는 66.31%라는 최대 점유율을 차지할 것으로 보이며, 2031년까지 연평균 성장률(CAGR) 5.55%로 성장할 것으로 전망됩니다. 프로그래머블 로직 컨트롤러(PLC)는 이산형 작업에서 여전히 필수적인 반면, 검증된 감사 추적이 요구되는 공정 환경에서는 분산 제어 시스템(DCS)이 주도적인 위치를 차지하고 있습니다. 산업용 PC는 고속 비전 및 AI 워크로드를 확대하고 있으며, 특히 전자기기 조립 분야에서는 2024년 출하 대수가 19% 증가했습니다.
드라이브, 모터, 센서, 로봇 공학이 나머지 지출을 차지하며 컨트롤러 시장의 성장을 주도하고 있습니다. 인코더가 내장된 서보 모터가 포장 분야에서 스테핑 모터를 대체하며 0.01mm의 정밀도를 실현하고 있습니다. IO-Link 센서는 시운전 시간을 25% 단축했으며, 임베디드 딥러닝 카메라는 자동차 최종 검사에서 99.5%의 결함 검출률을 달성하고 있습니다. 세척 대응 사양의 협동 로봇은 음료 팔레타이징 라인에서 점유율을 확대되고 있습니다.
자동차 및 기계 업계 고객들이 고속 로직을 우선시하는 가운데, 이산 제어 시스템은 2025년 매출의 39.46%를 차지했습니다. 공정 제어는 온도, 압력, 유량을 조절함으로써 화학·제약 업계를 주도하고 있습니다.
SCADA는 이력 관리 및 시각화 기능을 제공하지만, 연평균 성장률(CAGR)은 4.05%에 그치고 있습니다. PLC, PC, 게이트웨이를 통합한 IoT 지원 엣지 플랫폼은 5.9%의 성장률로 확대되고 있으며, 독자적인 데이터를 퍼블릭 클라우드에 공개하지 않고도 예측 정비를 위한 응답성이 높은 계층을 구축하고 있습니다. 1밀리초 미만의 지연을 보장하는 타임 센시티브 네트워킹 스위치에 대한 수요는 아키텍처 전환을 뒷받침하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.02According to Mordor Intelligence, the Germany factory automation and industrial controls market size is expected to grow from USD 10.76 billion in 2025 to USD 11.3 billion in 2026 and is forecast to reach USD 14.45 billion by 2031 at 5.05% CAGR over 2026-2031.
This report is Segmented by Component (Controllers, and Drives), Control System Type (Discrete Control Systems, Process Control Systems, and More), End-User Industry (Automotive, Machinery and Equipment, and More), Deployment Model (On-Premises Control Systems, Hybrid Architectures, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Germany Factory Automation And Industrial Controls Market Trends and Insights
Industry 4.0 Adoption Across German Manufacturing
Plattform Industrie 4.0 reported that by end-2024, 78% of large plants and 54% of SMEs had implemented at least one digital use case, up from 41% in 2020. Asset Administration Shell and OPC UA standards now underpin machine-to-machine data exchange, letting heterogeneous fleets interoperate without vendor lock-in. Tier-one automotive suppliers embed digital twins inside programmable logic controller code to test changeovers virtually, shrinking downtime from days to hours. Machinery builders have standardized on plug-and-produce modules that reduce engineering effort by up to 40%, enabling line re-configuration within a single shift. Demand for industrial PCs with multi-core processors and FPGAs is rising as manufacturers run machine-learning inference at the edge, bypassing latency and safeguarding intellectual property on-premises.
Rising Labor Costs and Skilled Labor Shortage Driving Automation
Median hourly manufacturing wages climbed to EUR 47.30 (USD 53.45) in 2024, the highest in the European Union. Germany faces a projected 1.2 million technical-worker shortfall by 2030. Collaborative robots without safety cages shipped 22% more units in 2024, especially to food and beverage packagers that handle variable-size products. Pharmaceutical contractors integrated automated guided vehicles with warehouse-management software, boosting throughput 18% and cutting injuries 35%. Automation offsets spiraling onboarding costs as apprenticeship completion rates declined 9% since 2020 and operator turnover averages 14% annually.
High Initial Capital Expenditure for SMEs
SMEs employ 60% of Germany's manufacturing workforce yet face upfront retrofit costs of EUR 800,000 to 1.5 million (USD 904,000 to 1.70 million) per plant, extending payback to five years in low-margin segments. The Digital Now subsidy covers half the spend, but applicants must supply energy audits and cybersecurity plans that small firms often outsource, delaying disbursements six to nine months. Leasing and automation-as-a-service models spread expenses over monthly fees, though concerns about data ownership and vendor lock-in temper adoption VDMA.
Other drivers and restraints analyzed in the detailed report include:
- Government Incentives for Energy-Efficient Smart Factories
- Increasing Demand for Mass Customization and Flexible Production
- Integration Complexity With Legacy Brownfield Equipment
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Controllers held the largest slice of the Germany factory automation and industrial controls market size at 66.31% in 2025 and will grow at a 5.55% CAGR to 2031. Programmable logic controllers remain indispensable for discrete tasks, while distributed control systems lead in process environments that demand validated audit trails. Industrial PCs are seizing high-speed vision and AI workloads, particularly in electronics assembly, where shipments jumped 19% in 2024.
Drives, motors, sensors and robotics comprise the balance of spending and track controller growth. Servo motors with integrated encoders replace steppers in packaging, offering 0.01 millimeter precision. IO-Link sensors reduce commissioning by 25%, and embedded deep-learning cameras deliver 99.5% defect detection in automotive final inspection. Collaborative robots with wash-down ratings are gaining share in beverage palletizing lines.
Discrete control systems secured 39.46% of 2025 revenue as automotive and machinery customers prioritize high-speed logic. Process control dominates chemicals and pharmaceuticals by regulating temperature, pressure and flow.
SCADA provides historian and visualization functions but lags at 4.05% CAGR. IoT-enabled edge platforms, integrating PLCs, PCs and gateways, advance at 5.9%, establishing a responsive layer for predictive maintenance without exposing proprietary data to public clouds. Demand for time-sensitive networking switches that guarantee sub-1 millisecond latency underscores the architectural transition.
Complete Report Scope:
- By Component
- Controllers
- Programmable Logic Controllers (PLCs)
- Distributed Control Systems (DCS)
- Industrial PCs (IPCs)
- Drives
- Motors
- Sensors
- Machine Vision
- Robotics
- Other Drives
- Controllers
- By Control System Type
- Discrete Control Systems
- Process Control Systems
- Supervisory Control and Data Acquisition (SCADA)
- IoT-Enabled Edge Control Platforms
- By End-User Industry
- Automotive
- Machinery and Equipment
- Electronics and Semiconductors
- Food and Beverage
- Pharmaceuticals and Chemicals
- Metals and Mining
- Other End-User Industries
- By Deployment Model
- On-Premises Control Systems
- Cloud-Based Control Platforms
- Hybrid (Edge + Cloud) Architectures
List of Companies Covered in this Report:
- Siemens AG
- Bosch Rexroth AG
- ABB Ltd
- Schneider Electric SE
- Mitsubishi Electric Corporation
- Rockwell Automation Inc.
- Honeywell International Inc.
- Emerson Electric Co.
- Omron Corporation
- Fanuc Corporation
- Yaskawa Electric Corporation
- KUKA AG
- Beckhoff Automation GmbH and Co. KG
- B and R Industrial Automation GmbH
- Festo SE and Co. KG
- Phoenix Contact GmbH and Co. KG
- WAGO Kontakttechnik GmbH and Co. KG
- Lenze SE
- SEW-Eurodrive GmbH and Co. KG
- Danfoss A/S
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Industry 4.0 Adoption Across German Manufacturing
- 4.2.2 Rising Labor Costs and Skilled Labor Shortage Driving Automation
- 4.2.3 Government Incentives for Energy-Efficient Smart Factories
- 4.2.4 Increasing Demand for Mass Customization and Flexible Production
- 4.2.5 Emphasis on Cyber-Physical Security Standards Boosting Control System Upgrades
- 4.2.6 Reshoring of Critical Supply Chains Stimulating Domestic Automation Capex
- 4.3 Market Restraints
- 4.3.1 High Initial Capital Expenditure for SMEs
- 4.3.2 Integration Complexity with Legacy Brownfield Equipment
- 4.3.3 Semiconductor Supply Chain Volatility Delaying Controller Deliveries
- 4.3.4 Stringent Data Sovereignty Regulations Hindering Cloud-Based Control Platforms
- 4.4 Impact of Macroeconomic Factors
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Threat of Substitutes
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Bargaining Power of Suppliers
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Controllers
- 5.1.1.1 Programmable Logic Controllers (PLCs)
- 5.1.1.2 Distributed Control Systems (DCS)
- 5.1.1.3 Industrial PCs (IPCs)
- 5.1.2 Drives
- 5.1.2.1 Motors
- 5.1.2.2 Sensors
- 5.1.2.3 Machine Vision
- 5.1.2.4 Robotics
- 5.1.2.5 Other Drives
- 5.1.1 Controllers
- 5.2 By Control System Type
- 5.2.1 Discrete Control Systems
- 5.2.2 Process Control Systems
- 5.2.3 Supervisory Control and Data Acquisition (SCADA)
- 5.2.4 IoT-Enabled Edge Control Platforms
- 5.3 By End-User Industry
- 5.3.1 Automotive
- 5.3.2 Machinery and Equipment
- 5.3.3 Electronics and Semiconductors
- 5.3.4 Food and Beverage
- 5.3.5 Pharmaceuticals and Chemicals
- 5.3.6 Metals and Mining
- 5.3.7 Other End-User Industries
- 5.4 By Deployment Model
- 5.4.1 On-Premises Control Systems
- 5.4.2 Cloud-Based Control Platforms
- 5.4.3 Hybrid (Edge + Cloud) Architectures
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Siemens AG
- 6.4.2 Bosch Rexroth AG
- 6.4.3 ABB Ltd
- 6.4.4 Schneider Electric SE
- 6.4.5 Mitsubishi Electric Corporation
- 6.4.6 Rockwell Automation Inc.
- 6.4.7 Honeywell International Inc.
- 6.4.8 Emerson Electric Co.
- 6.4.9 Omron Corporation
- 6.4.10 Fanuc Corporation
- 6.4.11 Yaskawa Electric Corporation
- 6.4.12 KUKA AG
- 6.4.13 Beckhoff Automation GmbH and Co. KG
- 6.4.14 B and R Industrial Automation GmbH
- 6.4.15 Festo SE and Co. KG
- 6.4.16 Phoenix Contact GmbH and Co. KG
- 6.4.17 WAGO Kontakttechnik GmbH and Co. KG
- 6.4.18 Lenze SE
- 6.4.19 SEW-Eurodrive GmbH and Co. KG
- 6.4.20 Danfoss A/S
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


