

|
시장보고서
상품코드
2125506
유럽의 인트라로지스틱스 자동화 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Europe Intralogistics Automation - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 유럽의 인트라로지스틱스 자동화 시장 규모는 2025년 68억 4,000만 달러로 평가되었고, 2026년에는 77억 2,000만 달러로 추정되고, 2031년까지 128억 9,000만 달러에 이를 것으로 전망되며, 2026-2031년 CAGR 10.79%를 나타낼 것으로 예측됩니다.
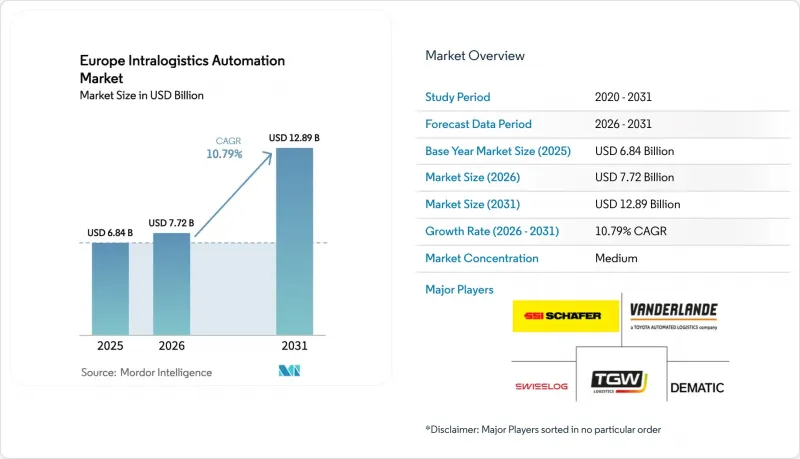
본 보고서는 제품 유형별(모바일 로봇, 자동 분류 시스템, 기타), 최종 사용자 산업별(공항, 우편·소포, 일반 제조업, 자동차, 기타), 구성 요소별(하드웨어, 소프트웨어, 서비스), 기능별(보관, 주문 피킹 및 상품 출고, 기타), 지역별(영국, 독일, 기타)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
유럽의 인트라로지스틱스 자동화 시장 동향 및 인사이트
전자상거래의 급속한 성장과 옴니채널 주문 처리 압박
2025년에는 서유럽 총 매출에서 온라인 소매가 차지하는 비중이 18.3%를 나타낼 것으로 예측되며, 수요가 집중되는 지역으로부터 20km 반경 내에 재고를 확보하려는 경쟁이 격화되고 있습니다. 마이크로 풀필먼트 센터에서는 ‘상품에서 사람으로’ 방식의 셔틀 시스템을 채택하여 주문 처리 시간을 90초로 단축하고 보관 밀도를 4배 높임으로써, 5,000m2 규모의 다크 스토어 한 곳에서 하루 1만 건의 주문을 발송할 수 있게 되었습니다. 까르푸(Carrefour) 등 대형 식품 소매업체들은 인구 밀집 도시 지역에 큐브형 보관 그리드를 도입하여, 제한된 바닥 면적을 라스트 마일 배송의 집적 공간으로 확보했습니다. 고속 분류기는 현재 시간당 최대 5만 개의 소포를 처리할 수 있으며, 2025년에 국경을 넘는 소포 처리량이 전년 대비 23% 증가한 점을 고려할 때, 이러한 처리 능력은 매우 중요합니다. 옴니채널 워크플로우에는 자동화 오케스트레이션 플랫폼만이 대규모로 실행 가능한 실시간 슬롯 할당 알고리즘이 필수적입니다.
EU 27개국의 노동력 부족과 임금 상승
2025년에는 물류 종사자가 210만 명 부족하다는 구조적인 문제로 인해, 19개 회원국에서 FTE(전일제 환산)당 총 인건비가 3만 5,000유로(3만 9,550달러)를 초과했습니다. 독일에서만 2025년 4분기에 38만 7,000건의 구인 부족이 보고되었습니다. 자율 주행 로봇을 도입함으로써 한 명의 작업자가 8-12곳의 작업 스테이션을 감독할 수 있게 되어 생산성이 실질적으로 4배 향상됩니다. 임금 수렴으로 인해 동유럽의 인건비 경쟁력이 사라지면서, 폴란드의 3PL 기업들은 2025년에 로봇 군단을 활용한 검사 운영을 시작했습니다. 유럽연합 집행위원회는 2030년까지 물류 부문의 노동력 공급이 연평균 0.3% 감소할 것으로 예측하고 있어, 자동화의 필요성은 더욱 커지고 있습니다.
막대한 설비 투자와 장기적인 투자 회수 기간
3만m² 규모의 물류 센터용 턴키 방식 AS/RS 프로젝트는 800만-1,200만 유로(904만-1,356만 달러)의 비용이 소요되며, 투자 회수에는 4.5-6년이 걸립니다. 유럽 창고 용량의 64%를 차지하는 중소기업은 대개 3% 미만의 금리로 대출을 이용할 수 없어, 인건비 절감 효과가 현저함에도 불구하고 도입이 지연되고 있습니다. 로봇 1대당 월 2,500-4,000유로(2,825-4,520달러)의 ‘Robotics-as-a-Service(RaaS)’ 리스는 진입 장벽을 낮추지만, 여전히 3년의 계약 기간과 시설 개조가 요구됩니다. 2025년 유럽투자은행(EIB)의 조사에 따르면, 사업자의 41%가 자동화 도입을 미루는 이유로 ‘ 수요의 불확실성’을 꼽았습니다. 남유럽에서는 소유 구조가 세분화되어 있어 이사회 차원의 승인이 지연되면서, 보급률이 북유럽에 비해 30-40% 뒤처져 있습니다.
부문 분석
2025년, 자동 창고 시스템(AS/RS)은 유럽 내 인트라로지스틱스 자동화 시장 점유율의 26.71%를 차지했습니다. 이는 도시 지역의 마이크로 풀필먼트 센터에서 공간 효율을 4배로 높이는 확고히 자리 잡은 큐브형 보관 그리드를 반영한 것입니다. 그러나 이 부문은 단일 용도로 사용되기 때문에 취급 제품 프로파일이 변경될 경우 재배치에 대한 유연성이 제한됩니다. 모바일 로봇은 2031년까지 연평균 성장률(CAGR) 11.91%로 성장하여 유럽 내 인트라로지스틱스 자동화 시장 전체를 상회할 것으로 예측됩니다. 이는 사업자가 계절에 따라 차량을 확대하거나 몇 주 만에 시설 간 자산을 이동시킬 수 있는 임대 기반 모델에 힘입은 것입니다. 구독형 가격 책정은 이사회 승인 절차를 간소화하고 사업 확장을 위한 자본을 확보해 줍니다.
또한 모바일 로봇은 VDA 5050에 따른 상호 운용성의 이점도 누리고 있으며, 이를 통해 이종 혼합 차량이 공존할 수 있게 되어, 과거 모놀리식 AS/RS 투자를 촉진했던 벤더 락인 위험을 최소화할 수 있습니다. 자동 분류 시스템은 사이버위크 성수기에 시간당 5만 개의 소포를 처리해야 하는 소포 허브에서 주류를 이루고 있으며, 비전 가이드 방식 그리퍼를 갖춘 팔레타이징 셀은 케이스 처리 주기를 8초로 단축하고 있습니다. 장거리 내부 운송의 기반은 여전히 자동 컨베이어이지만, 사업자들은 고정 궤도를 모바일 로봇으로 보완하고, 신제품 출시에 맞추어 하룻밤 사이에 재구성할 수 있는 유연한 ‘매트릭스 레이아웃’을 구축하는 경향이 강해지고 있습니다.
소매, 창고, 유통 부문은 2025년 매출의 29.43%를 차지한 것으로 평가되었으며, 밀집된 도시 지역에서 2시간 내 배송을 목표로 하는 옴니채널 비즈니스의 견인에 힘입어 연평균 성장률(CAGR) 12.02%로 성장을 주도할 전망입니다. 이 부문이 ‘단품 단위 피킹’에 의존하고 있다는 점은 모바일 로봇의 강점과 부합하며, 유럽 인트라로지스틱스 자동화 시장에서 이 부문이 차지하는 기여도가 매우 크다는 사실을 뒷받침합니다. 우편 및 소포 사업자들은 크로스벨트 소터에 대한 투자를 지속하고 있으며, 이로 인해 매년 휴가 시즌마다 유럽 내 intra-logistics 자동화 시장 규모가 확대되고 있습니다.
자동차 부품 공급업체는 매출에서 차지하는 비중은 작지만, 유럽에서 가장 첨단인 저스트-인-시퀀싱 시스템의 일부를 도입하고 있으며, 수동식 태거로는 도저히 달성할 수 없는 99.8%의 납기 준수율을 요구하고 있습니다. 식품 및 음료 시설에서는 냉장 구역을 주행하기 위한 스테인리스제 이동형 로봇을 도입하고 있으며, 이로 인해 단가는 상승하지만 규정 준수 리스크는 감소하고 있습니다. 일반 제조업에서는 4년 미만의 투자 회수가 예상되는 원자재 순서 배열 솔루션이 선호되고 있습니다. 한편, 공항 수하물 처리 업무는 여전히 고부가가치의 틈새 시장이며, 2028년 여행 수요의 급증에 앞서 유럽의 허브 공항 각사는 수하물 오처리율을 3분의 1로 줄이기 위해 경쟁하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the Europe intralogistics automation market size is expected to increase from USD 6.84 billion in 2025 to USD 7.72 billion in 2026 and reach USD 12.89 billion by 2031, growing at a CAGR of 10.79% over 2026-2031.
This report is Segmented by Product Type (Mobile Robots, Automated Sorting Systems, and More), End-User Industry (Airport, Post and Parcel, General Manufacturing, Automotive, and More), Component (Hardware, Software, and Services), Function (Storage, Order Picking and Retrieval, and More), and Geography (United Kingdom, Germany, and More). The Market Forecasts are Provided in Terms of Value (USD).
Europe Intralogistics Automation Market Trends and Insights
E-Commerce Boom And Omnichannel Fulfilment Pressure
Online retail penetration reached 18.3% of total Western European sales in 2025, intensifying the race to keep inventory within 20 kilometers of demand hotspots. Micro-fulfillment centers rely on goods-to-person shuttles that cut order cycle time to 90 seconds and raise storage density fourfold, enabling a single 5,000 m2 dark store to ship 10,000 daily orders. Grocery leaders such as Carrefour adopted cube-storage grids in dense urban nodes, freeing scarce floor space for last-mile staging. High-speed sorters now process up to 50,000 parcels per hour, a capability vital as cross-border parcel volumes grew 23% year-on-year in 2025. Omnichannel workflows require real-time slotting algorithms that only automated orchestration platforms can execute at scale.
Labour Shortages And Wage Inflation Across EU27
A structural shortfall of 2.1 million logistics workers in 2025 pushed fully loaded labor costs per FTE to over EUR 35,000 (USD 39,550) in 19 member states. Germany alone reported 387,000 vacancies in Q4 2025. Autonomous mobile robots allow one worker to supervise 8-12 stations, effectively quadrupling productivity. Wage convergence eroded Eastern Europe's labor arbitrage, prompting Polish 3PLs to pilot robot fleets in 2025. The European Commission projects logistics labor supply to contract 0.3% annually through 2030, widening the automation imperative.
High Capex And Long ROI Horizons
Turnkey AS/RS projects for a 30,000 m2 DC cost EUR 8-12 million (USD 9.04-13.56 million) and repay in 4.5-6 years. SMEs, which control 64% of European warehouse capacity, often lack access to sub-3% financing, delaying adoption despite strong labor-saving cases. Robotics-as-a-Service leases at EUR 2,500-4,000 (USD 2,825-4,520) per robot per month reduce barriers but still demand three-year commitments and facility retrofits. Forty-one percent of operators cited "uncertain demand" when deferring automation in the 2025 EIB survey. Southern Europe trails Northern peers by 30-40 percentage points in penetration as fragmented ownership structures slow board-level approvals.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Advances In AI-Powered Mobile Robotics And IoT
- 5G And Private-LTE Roll-Outs Enabling Real-Time Orchestration
- Legacy IT And OT Integration Complexity
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Automated storage and retrieval systems delivered 26.71% of Europe intralogistics automation market share in 2025, reflecting entrenched cube-storage grids that quadruple space efficiency in urban micro-fulfillment centers. Yet the segment's single-purpose nature limits redeployability when product profiles shift. Mobile robots are projected to surpass the overall Europe intralogistics automation market at an 11.91% CAGR through 2031, buoyed by lease-based models that let operators scale fleets seasonally and move assets between facilities in weeks. Subscription pricing simplifies board approvals and preserves capital for expansion initiatives.
Mobile robots also benefit from VDA 5050-driven interoperability, which allows heterogeneous fleets to coexist, minimizing the vendor-lock risk that once favored monolithic AS/RS investments. Automated sorting systems dominate parcel hubs that must process 50,000 parcels per hour during Cyber Week peaks, while palletizing cells with vision-guided grippers cut case cycle times to eight seconds. Although automated conveyors remain the backbone for long-haul internal transport, operators increasingly supplement fixed tracks with mobile robots to create flexible "matrix layouts" capable of overnight reconfiguration for new product launches.
Retail, warehousing, and distribution accounted for 29.43% of revenue in 2025 and will lead growth at a 12.02% CAGR, driven by omnichannel businesses striving for two-hour delivery in dense urban areas. The segment's dependence on piece-level picking aligns with mobile-robot advantages, reinforcing its outsized contribution to the Europe intralogistics automation market. Post-and-parcel operators continue to invest in cross-belt sorters that push Europe intralogistics automation market size upward each holiday season.
Automotive suppliers, while representing a smaller revenue slice, deploy some of the continent's most sophisticated just-in-sequence systems, demanding 99.8% on-time accuracy that manual tuggers cannot match. Food and beverage facilities add stainless-steel mobile robots to navigate chilled zones, raising unit-cost premiums but trimming compliance risk. General manufacturing favors raw-material sequencing solutions with sub-four-year paybacks, whereas airport baggage handling remains a high-value niche, as European hubs race to cut mishandled-bag rates by one-third ahead of the 2028 travel surge.
Complete Report Scope:
- By Product Type
- Mobile Robots
- Automated Storage and Retrieval Systems (AS/RS)
- Automated Sorting Systems
- Palletising and De-Palletising Systems
- Automated Conveyors
- Order-Picking Systems
- By End-User Industry
- Airport
- Post and Parcel
- General Manufacturing
- Automotive
- Food and Beverage
- Retail, Warehousing and Distribution
- Other End-User Industries
- By Component
- Hardware
- Software
- Services
- By Function
- Storage
- Order Picking and Retrieval
- Sorting and Consolidation
- Packaging and Palletising
- Transportation and Conveyance
- By Country
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Europe
List of Companies Covered in this Report:
- Swisslog Holding AG
- TGW Logistics Group GmbH
- Vanderlande Industries B.V.
- SSI Schafer AG
- Dematic GmbH (KION Group)
- Daifuku Co., Ltd.
- Exotec SAS
- AutoStore ASA
- ABB Ltd.
- Honeywell International Inc.
- Interroll Holding AG
- Jungheinrich Aktiengesellschaft
- Kardex Holding AG
- BEUMER Group GmbH and Co. KG
- KNAPP AG
- KUKA Aktiengesellschaft
- Linde Material Handling GmbH
- Murata Machinery, Ltd.
- Ocado Group plc
- Toyota Industries Corporation
- Viastore Systems GmbH
- WITRON Logistik + Informatik GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Impact of Macroeconomic Factors on the Market
- 4.3 Industry Value / Supply-Chain Analysis
- 4.4 Market Drivers
- 4.4.1 E-Commerce Boom and Omnichannel Fulfilment Pressure
- 4.4.2 Labour Shortages and Wage Inflation Across EU27
- 4.4.3 Rapid Advances in AI-Powered Mobile Robotics and IoT
- 4.4.4 5G and Private-LTE Roll-Outs Enabling Real-Time Orchestration
- 4.4.5 EU Green Deal Incentives for Low-Carbon Intralogistics
- 4.4.6 Interoperability Standards (VDA 5050) Enabling Multi-Vendor Integration
- 4.5 Market Restraints
- 4.5.1 High Capex and Long ROI Horizons
- 4.5.2 Legacy IT and OT Integration Complexity
- 4.5.3 Rising Cyber-Security Threats to Networked Robotics
- 4.5.4 Grid Power Availability Bottlenecks in Logistics Hubs
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Adjacent Market Influence Analysis
- 4.9.1 Stretch-Wrapping Machines Market
- 4.9.2 Goods Elevator Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Mobile Robots
- 5.1.2 Automated Storage and Retrieval Systems (AS/RS)
- 5.1.3 Automated Sorting Systems
- 5.1.4 Palletising and De-Palletising Systems
- 5.1.5 Automated Conveyors
- 5.1.6 Order-Picking Systems
- 5.2 By End-User Industry
- 5.2.1 Airport
- 5.2.2 Post and Parcel
- 5.2.3 General Manufacturing
- 5.2.4 Automotive
- 5.2.5 Food and Beverage
- 5.2.6 Retail, Warehousing and Distribution
- 5.2.7 Other End-User Industries
- 5.3 By Component
- 5.3.1 Hardware
- 5.3.2 Software
- 5.3.3 Services
- 5.4 By Function
- 5.4.1 Storage
- 5.4.2 Order Picking and Retrieval
- 5.4.3 Sorting and Consolidation
- 5.4.4 Packaging and Palletising
- 5.4.5 Transportation and Conveyance
- 5.5 By Country
- 5.5.1 United Kingdom
- 5.5.2 Germany
- 5.5.3 France
- 5.5.4 Italy
- 5.5.5 Spain
- 5.5.6 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Swisslog Holding AG
- 6.4.2 TGW Logistics Group GmbH
- 6.4.3 Vanderlande Industries B.V.
- 6.4.4 SSI Schafer AG
- 6.4.5 Dematic GmbH (KION Group)
- 6.4.6 Daifuku Co., Ltd.
- 6.4.7 Exotec SAS
- 6.4.8 AutoStore ASA
- 6.4.9 ABB Ltd.
- 6.4.10 Honeywell International Inc.
- 6.4.11 Interroll Holding AG
- 6.4.12 Jungheinrich Aktiengesellschaft
- 6.4.13 Kardex Holding AG
- 6.4.14 BEUMER Group GmbH and Co. KG
- 6.4.15 KNAPP AG
- 6.4.16 KUKA Aktiengesellschaft
- 6.4.17 Linde Material Handling GmbH
- 6.4.18 Murata Machinery, Ltd.
- 6.4.19 Ocado Group plc
- 6.4.20 Toyota Industries Corporation
- 6.4.21 Viastore Systems GmbH
- 6.4.22 WITRON Logistik + Informatik GmbH
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


